

Reviewed August 2026 against the USDA Farm Service Agency and Mossy Oak Properties.
Try it: Enter your numbers above to see the estimated payment. →
As of August 2026, USDA Farm Service Agency (FSA) Direct Operating Loans carry a 5.25% interest rate and Direct Farm Ownership Loans carry 6.00%, while commercial and seller-financed farmland loans run considerably higher — 6.5% to 12% depending on the lender. That gap is the single most important fact for anyone comparing agriculture loans in Bloomington, Millington, or Washington: FSA financing is usually the cheaper option if you qualify, but it comes with more paperwork and narrower eligibility than a bank or seller note.
This article walks through what’s actually available in 2026 — federal rates you can verify today, commercial land-financing ranges, USDA grant ceilings for women and beginning farmers, and where “lot loans” and rural banking programs fit into the picture. Every figure below carries a source and a date so you can check it yourself before applying.
Current Agriculture Loan Interest Rates
“Ag loan interest rates” and “land interest rates” are moving targets, so start with where the numbers actually live rather than a snapshot that will be stale by the time you read this. The USDA Farm Service Agency publishes new lending rates on the first business day of every month at fsa.usda.gov/tools/informational/rates, and the rates move with Treasury note pricing — they are not set once a year and left alone.
The August 2026 rate announcement from the USDA Farm Service Agency set the following FSA lending rates:
- Direct Farm Operating Loans: 5.25%
- Direct Farm Ownership Loans: 6.00%
- Joint Financing Farm Ownership Loans: 4.00%
- Commodity Loans (under one year): 5.00%, down from 4.625% in January 2026 — a reminder that these figures move both directions month to month
On the commercial side, Mossy Oak Properties reports that bank-financed farmland loans in 2026 typically price between 6.5% and 10%, while seller-financed land contracts run from 8% to 12% — both ranges reflecting the risk premium a private lender charges relative to a government-backed program. If you’re comparing “agriculture loans” against a straight “land interest rate” quote from a realtor or seller, this is the band to check it against.
Scale matters too. FSA disbursed $6.7 billion across roughly 28,000 direct and guaranteed farm loans in fiscal year 2025, per the USDA Farm Service Agency’s farm loan data — but FSA financing still covers an estimated 10% or less of all US farms carrying debt. The other 90%+ is commercial banks, Farm Credit System associations, and seller financing, which is exactly the territory where interest rates in this article’s second table apply.



Agriculture Loans in Bloomington
Bloomington-area farms financing corn, soybean, and specialty-crop operations sit in the same national rate environment described above: FSA Direct Operating Loans at 5.25% and Direct Ownership Loans at 6.00% as of August 2026, versus commercial bank land loans in the 6.5%-10% range. A local bank or credit union sets its own operating-loan rate off its cost of funds and the borrower’s credit profile — there is no single published “Bloomington rate,” so the way to get a real quote is to call at least two local lenders (a community bank and a Farm Credit System association office) and compare their current sheet against the FSA number above.
What a Bloomington-area application typically needs to show a lender: a farm operating plan, recent financial statements, and proof of land tenure. Verifiable, up-to-date field data — crop health imagery, input records, yield history — strengthens that package regardless of which lender you approach.
Discover how Farmonaut’s Crop Loan & Insurance Verification solutions can help financial institutions and lenders verify farming activities via satellite monitoring—accelerating approval while reducing fraud risks for agriculture loans in Bloomington, Millington, and Washington.

Agriculture Loans in Millington
Millington’s livestock and crop operations — poultry, cattle, and row crops — draw on the same FSA and commercial lending menu, with two categories worth calling out specifically: facility-expansion financing for barns and biosecurity infrastructure, and short-term feedstock loans that bridge cash flow between input purchase and sale. FSA’s under-one-year Commodity Loan rate, set at 5.00% in August 2026 (down from 4.625% in January), is the closest published benchmark for this kind of short-cycle borrowing — check the current figure at FSA’s rate page before assuming either number still holds.
For facility and equipment purchases with a longer horizon, the FSA Direct Farm Ownership rate of 6.00% and the Joint Financing Ownership rate of 4.00% are the two federal benchmarks to compare against whatever a local bank or Farm Credit association quotes. Bridge and biosecurity loans large enough to require real estate collateral will typically land closer to the 6.5%-10% commercial land-loan band reported by Mossy Oak Properties for 2026.

If you manage multiple assets or need logistics optimization for your livestock and crops, leverage Farmonaut’s Fleet Management tools for precise tracking and efficient operation of machinery and vehicles across expansive Millington farms.
Agriculture Loans and Farm Loans in Washington
Washington’s horticulture, orchard, and specialty-crop growers — including vineyards and tree-nut operations — face capital needs concentrated in orchard establishment, irrigation upgrades, and pest management technology. The federal benchmark rates apply the same way here: 5.25% on FSA Direct Operating, 6.00% on FSA Direct Ownership, both current as of the August 2026 FSA rate announcement and subject to change on the first business day of next month.
“Washington farm loans” and “agriculture loans washington” searches often mean two different things in practice: operating capital for an existing orchard versus land acquisition for a new one. For land acquisition, the 6.5%-10% bank-financed range and 8%-12% seller-financed range reported by Mossy Oak Properties for 2026 are the numbers to weigh against any FSA Farm Ownership or Joint Financing offer — the FSA route is cheaper on paper but has income and entity-structure eligibility limits that a large commercial vineyard or orchard operation may not meet.


Interested in sustainability certification or reducing environmental impact? Explore Farmonaut’s Carbon Footprinting Tools for real-time satellite monitoring and emissions tracking—ideal for farmers pursuing sustainability-linked agriculture loans in Washington.
Land and Lot Loans: Washington, Missouri, and Beyond
A search for “lot loans” (as in Washington, Missouri, a small city roughly an hour southwest of St. Louis) usually means financing a vacant parcel or acreage without a working farm operation attached — distinct from an operating loan or an FSA Farm Ownership Loan, both of which assume an active agricultural enterprise. Raw land and lot purchases fall under the same commercial land-financing bands cited above: 6.5% to 10% through a bank, 8% to 12% through a seller-financed contract, per Mossy Oak Properties’ 2026 figures.
If the parcel will become a working farm, an FSA Direct Farm Ownership Loan (6.00%) or Joint Financing Ownership Loan (4.00%, combined with a commercial or cooperative lender) may apply once there’s a farm operating plan attached to the purchase — FSA does not lend on land with no agricultural use plan. For a lot purchase with no farming plan, expect to work with a local bank, credit union, or seller note at the commercial rates above rather than through FSA.
Grants for Female Farmers and Veteran Farmers
“Grants for female farmers” and “veteran farm grants” both point to real, named USDA programs rather than a single blanket grant — here’s what’s actually funded for fiscal year 2026:
- Value-Added Producer Grant (VAPG), working-capital category: up to $200,000, available to women farmers among other applicant classes, per USDA’s FY2026 program guidance.
- Value-Added Producer Grant, planning category: up to $50,000 for planning activities.
- Beginning Farmer and Rancher Development Program: $10,000,000 allocated for FY2026 with outreach targeted at women and other underrepresented groups entering farming.
These figures come from USDA’s FY2026 grant guidance as summarized by Career Ahead Online’s review of USDA’s 2026 grants and loans. There is no dedicated, separately-branded “veteran farm grant” program identified in USDA’s current published guidance distinct from these — veteran farmers apply through the same VAPG and Beginning Farmer and Rancher channels, plus FSA loan programs that carry veteran-specific down-payment and guarantee terms. Confirm current eligibility and application windows directly at your local USDA Service Center before assuming any dollar figure above still applies, since VAPG ceilings and BFRDP allocations are set annually through the federal budget process.
Young Farmer Loan Programs and Rural/Agribusiness Banking
“Young farmer loan programs” and rural/agribusiness banking overlap heavily with the Beginning Farmer and Rancher Development Program cited above ($10,000,000 allocated for FY2026), plus FSA’s Direct and Guaranteed loan categories, which carry lower down-payment and first-time-borrower terms for beginning farmers and ranchers. Of the roughly 28,000 direct and guaranteed loans FSA issued in fiscal year 2025 totaling $6.7 billion, a meaningful share goes to beginning-farmer designations — but FSA’s public reporting (linked above) does not break that share out by age or years-farming at the national summary level, so a farm-specific answer requires pulling the FSA Program Data report for your state and year rather than a national estimate.
Rural and agribusiness banking beyond FSA runs through the Farm Credit System, a network of borrower-owned cooperative lenders that publishes its own regional rates quarterly, and through commercial banks tracked in aggregate by the American Bankers Association. Neither publishes a single “young farmer rate” — the discount, where it exists, usually comes structured as a reduced down payment or an FSA guarantee on a commercial loan rather than a separate interest rate line, so ask your local Farm Credit office or bank specifically whether a beginning-farmer program applies to your application.
Loan Payment Calculator
Use the current FSA and commercial rate ranges above to estimate your own monthly payment before you apply.
Enter your numbers above to see the estimated payment.
Assumes a standard fixed-rate amortizing loan with equal monthly payments and no fees, points, balloon payment, or prepayment. Does not include property taxes, insurance, or origination costs. Selecting a rate benchmark from the dropdown fills in that rate — you can still edit it directly to test your own quote.
Satellite Data and Loan-Readiness
Whichever program you pursue — FSA, a commercial bank, Farm Credit, or a VAPG grant — the underlying application still runs on the same evidence: an operating plan, financial history, and verifiable proof of what’s actually growing on the land. Farmonaut’s satellite monitoring tools are built to strengthen that evidence base rather than replace the lending process itself.
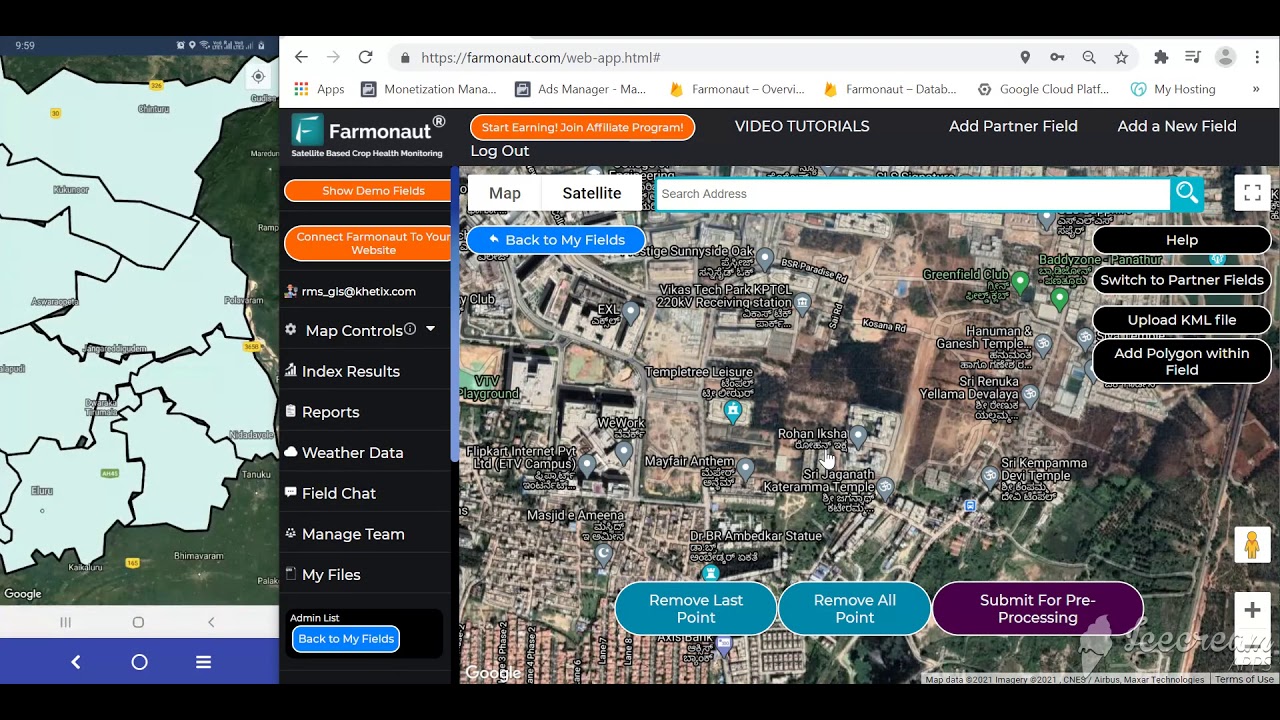
- Real-Time Farm Monitoring: Satellite-based assessment of crop health (NDVI), soil condition, and water usage.
- AI Advisory for Loan-Readiness: Our Jeevn AI delivers monitoring and diagnostic insights to help farmers optimize productivity and build loan applications backed by verifiable field data.
- Blockchain Traceability: End-to-end resource validation, enhancing creditworthiness and transparency for both borrowers and lenders.
- Resource & Fleet Management: Scalable tools reduce operational costs, improving the return on borrowed capital.
- Environmental Impact Tracking: Carbon footprint analytics for producers pursuing sustainability-linked loan products.
Loan application and resource-allocation transparency benefits from traceability tools that document how borrowed capital is actually used across a season.
Farmonaut’s Product Traceability Suite supports that documentation for lenders who want it.
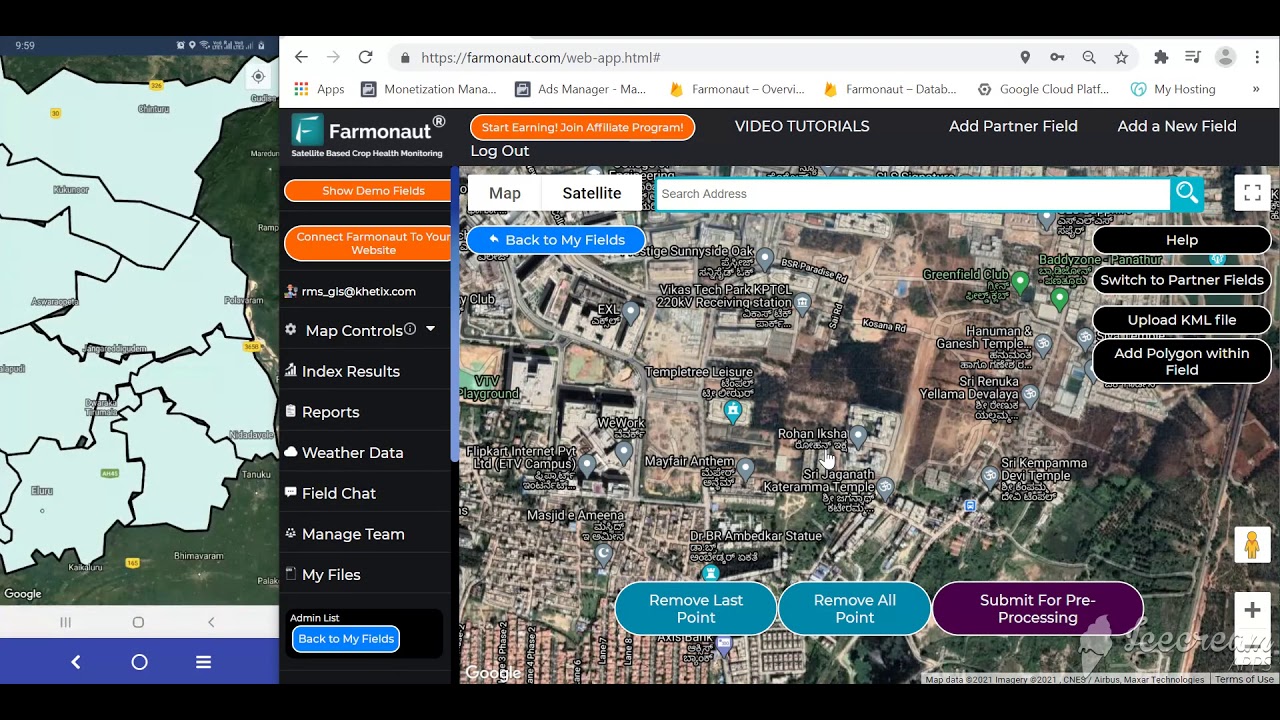
For those managing large acreages or multiple properties, our Large Scale Farm Management solution gives crop monitoring control that helps justify investment or support agriculture loan applications in Bloomington, Millington, and Washington with up-to-date farm data.
Planning for new plantations or sustainable forest projects? Visit Farmonaut’s Crop Plantation & Forest Advisory for science-backed decision making leveraged by AI and satellite data—useful supporting material for an agriculture loan application.
Developers and lenders interested in custom integrations or large-scale data access can explore our
public API
and
API developer documentation
for seamless connectivity to Farmonaut’s monitoring, traceability, and reporting tools.
Frequently Asked Questions
What is the current FSA interest rate for agriculture loans?
As of the August 2026 USDA Farm Service Agency rate announcement, Direct Operating Loans are 5.25%, Direct Farm Ownership Loans are 6.00%, and Joint Financing Ownership Loans are 4.00%. These rates reset on the first business day of every month based on Treasury note pricing — check FSA’s current rates page for the figure in effect when you apply.
How do commercial and seller-financed land loan rates compare to FSA rates?
Mossy Oak Properties reports 2026 bank-financed farmland loans in the 6.5%-10% range and seller-financed contracts at 8%-12% — both higher than FSA’s federal programs, which is the trade-off for FSA’s stricter eligibility and paperwork requirements.
Are there grants specifically for female or veteran farmers in 2026?
USDA’s FY2026 Value-Added Producer Grant offers up to $200,000 for working capital and up to $50,000 for planning, both open to women farmers among other applicant categories, alongside a $10,000,000 Beginning Farmer and Rancher Development Program allocation with outreach to women and other underrepresented groups. There is no separately branded veteran-specific grant in current USDA guidance; veteran farmers apply through these same programs plus FSA loan terms carrying veteran-specific guarantees. Confirm current details at your local USDA Service Center.
What documentation do I need for an agriculture loan?
Standard documents include an operating plan, financial statements, and proof of land tenure or rental. Satellite imagery reports or blockchain traceability records are increasingly requested as supporting evidence of what’s actually under cultivation.
Can I apply for FSA or commercial agriculture loans online?
FSA loan applications are handled through local USDA Service Centers; commercial banks and Farm Credit System associations increasingly support digital applications and document uploads alongside in-person underwriting.





Conclusion
Agriculture financing for Bloomington, Millington, and Washington farms comes down to two tracks: federal FSA programs at 4.00%-6.00% depending on loan type (August 2026), and commercial or seller-financed land loans at 6.5%-12%. Layer in USDA grant programs — up to $200,000 in VAPG working capital, up to $50,000 in VAPG planning funds, and a $10,000,000 Beginning Farmer and Rancher Development Program allocation for FY2026 — and there’s a real menu of options beyond a single bank quote.
None of these numbers are fixed for the year: FSA resets its rates monthly, and grant ceilings are set through the annual federal budget process. Bookmark the FSA rates page and your local USDA Service Center contact rather than this article’s snapshot, and use verifiable field data — the kind satellite monitoring platforms like Farmonaut generate — to strengthen whichever application you file.
Ready to strengthen your loan application with verifiable farm data? Read more on agriculture lending trends and explore Farmonaut’s tools for Bloomington, Millington, and Washington farms.

 Godrej Agrovet
 Hayleys Agriculture
 Linx Agritech
 Adinet
 Save Your Soils
 GalaxEye Space
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 DnCubed
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroRisk
 Oath Inc
 Esri North East Africa
 MDCV UK
 Etech Consulting Madagascar
 Vestlandsforsking
 WB Dev
 Sama Premium
 Tres Valles
 Blickwinkel
 Agricultural Credit Policy Council
 eKGIS
 Mostas Tech
 Andex
 Deluxe Conseil
 WICO
 Chimera Innovation
 SkyHarvest
 Teledarbas
 Exurbia Geospatial
 FieldZero

