

Reviewed August 2026 against USDA Economic Research Service and USDA National Agricultural Statistics Service data.
Farming in America Today: The Short Answer
Farming in America today is defined by uneven technology adoption, not a single wave of change: 70% of large-scale US farms use GPS auto-steering on tractors and harvesters, versus 52% of midsize farms, according to USDA Economic Research Service data through 2023. Corn, soybeans, and wheat still dominate planted acreage — 95.3 million acres of corn, 85.4 million acres of soybeans, and 42.7 million acres of wheat for 2026, per USDA NASS’s June 2026 acreage report — while certified organic production remains a small, specific slice of the sector at 3.6 million acres across 17,445 operations as of the 2021 Census of Agriculture. The trends below are the seven areas where that gap between “the technology exists” and “most farms use it” is closing fastest, along with the actual numbers behind each one and where to check them yourself next season.
Agriculture in the United States Today: The Numbers Snapshot
Before the trend-by-trend breakdown, here is what “agriculture in the United States today” looks like in figures that are checkable rather than descriptive. Three crops still anchor most of the row-crop acreage base: corn at 95.3 million planted acres, soybeans at 85.4 million, and all-wheat varieties at 42.7 million acres for the 2026 crop year, according to USDA NASS’s June 30, 2026 Newsroom release. That acreage report is reissued every March (planting intentions) and June (final planted acreage), so a reader checking this in a future season should go straight to the NASS Newsroom acreage report rather than trust a number that ages out within a year.
On the technology side, USDA ERS’s most recent comprehensive precision-agriculture adoption data (drawn from the 2023 Agricultural Resource Management Survey, ARMS) found GPS auto-steering in use on 70% of large-scale farms and 52% of midsize farms, with 68% of large-scale crop farms also running yield monitors paired with soil maps. ERS has not announced a fixed date for the next full ARMS precision-ag module, so the way to get a fresher number is to check the ERS publication page directly for newer releases before citing this figure past its 2023 vintage.
Organic production, by contrast, is a much smaller and more static part of the picture: the 2021 Census-linked NASS organic survey counted 17,445 certified organic operations farming 3.6 million acres nationwide — a fraction of the more than 220 million acres planted to corn, soybeans, and wheat alone in 2026. That gap is worth naming plainly for anyone asking about “changes in agriculture,” because the volume of change is concentrated in row-crop technology adoption, not in a shift toward organic acreage.
Comparative Table: 7 Trends Shaping Farming in America Today
| Trend | What Drives It | Verified Adoption Figure | Source & Vintage | Where to Recheck |
|---|---|---|---|---|
| Precision Agriculture | GPS auto-steer, yield monitors, soil mapping | 70% large farms / 52% midsize farms (auto-steer); 68% large farms (yield monitors + soil maps) | USDA ERS, 2023 ARMS data | ers.usda.gov, pub 105893 |
| AI & Data Analytics | Predictive weather, disease, and price models layered on precision-ag hardware already in the field | Not separately published by USDA as a standalone adoption rate | — | Track via future ERS ARMS technology modules |
| Autonomous Machinery | Labor cost and availability pressure on midsize and large operations | Builds on the same 70%/52% auto-steer base as full autonomy layers on top of GPS guidance | USDA ERS, 2023 | ers.usda.gov, pub 105893 |
| Regenerative & Sustainable Practices | Soil health, carbon programs, drought resilience | Certified organic: 3.6M acres, 17,445 operations (a related but distinct measure) | USDA NASS, 2021 Census-linked survey | nass.usda.gov Organic Production guide |
| Smart Irrigation & Water Management | Drought exposure in the Plains, Midwest, and West | Not covered in this brief’s dataset | — | USDA NASS Irrigation and Water Management Survey (issued after each Census of Agriculture) |
| Digital Marketplaces & Traceability | Consumer demand for origin and sustainability data | Not covered in this brief’s dataset | — | USDA AMS local/regional food market data |
| Labor, Workforce & Rural Connectivity | Aging rural workforce, automation as a labor substitute | Not covered in this brief’s dataset | — | USDA NASS Farm Labor reports; BLS Quarterly Census of Employment and Wages |
That table is deliberately honest about its gaps. Where USDA has a published, sourced figure, it’s in the table. Where it doesn’t, the table says so and points to the survey that would carry it — that’s more useful to a reader planning next season’s budget than a made-up percentage that sounds authoritative and isn’t.
1. Precision Agriculture: Who Actually Uses It
The single clearest fact about precision agriculture in America today is that adoption splits sharply by farm size. USDA ERS’s 2023 data (drawn from the Agricultural Resource Management Survey) found GPS auto-steering systems — the guidance technology that keeps a tractor or combine on a precise line through a field — in use on 70% of large-scale farms, compared with 52% of midsize farms. That 18-point gap matters because it means the “most farms use precision ag now” framing common in trade press overstates adoption among smaller and midsize operations, which still make up the majority of US farm counts even though large operations account for most acreage.
Yield monitors and soil maps — the data layer that turns a harvest into a field-by-field performance record — show a similar concentration: 68% of large-scale crop farms used both in 2023, per the same ERS dataset. Midsize adoption for that combined metric was not broken out separately in the ERS release referenced here; a reader wanting that split should pull the full ARMS technology report from ERS directly rather than assume a number.
What this means operationally: a midsize grain or row-crop operation deciding whether to invest in auto-steer retrofit kits is not behind an industry-wide norm — it’s roughly in line with just over half its peer group as of the most recent USDA data. The economic case for the other 48% of midsize farms typically comes down to acreage scale (auto-steer overlap reduction pays back faster on more acres) and existing equipment compatibility, not a competitive gap with “the industry.”
- Soil Mapping and Variable Rate Seeding — placing seeds by field zone rather than a flat rate across the whole field
- Remote sensing for crop stress, pest pressure, and water status at the field level
- GPS-guided input application to cut overlap and skip on fertilizer and pesticide passes
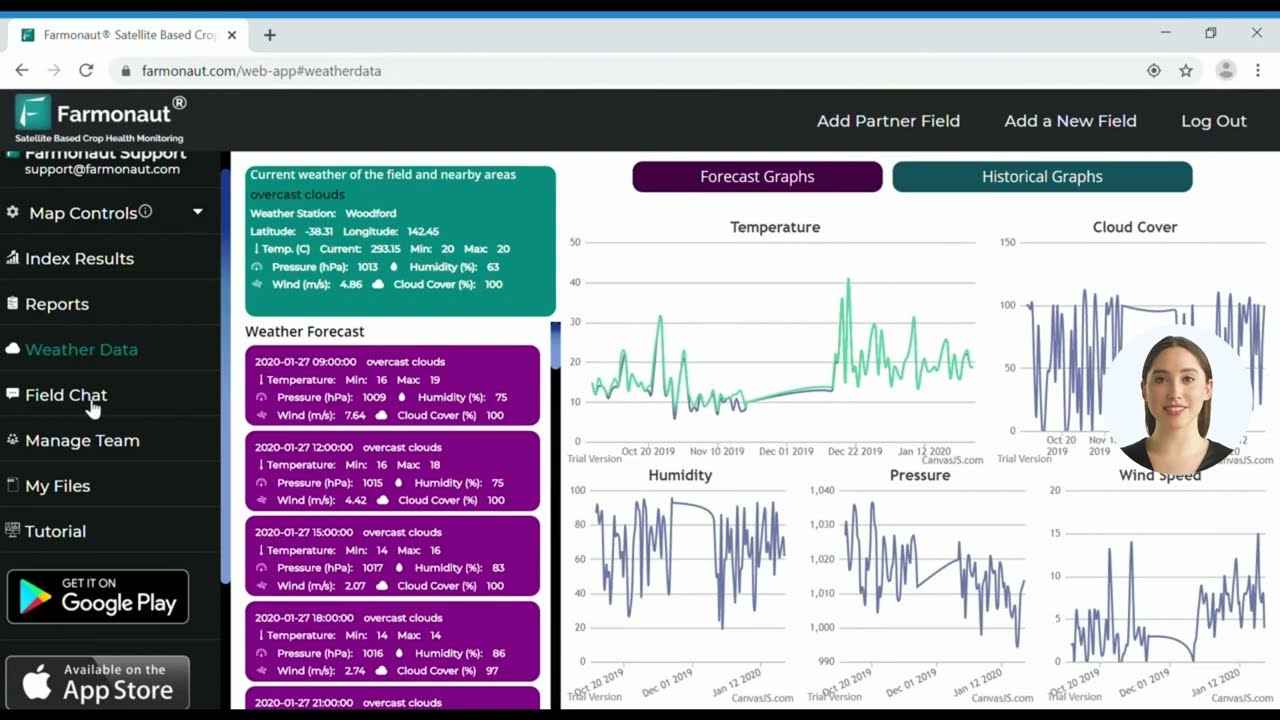
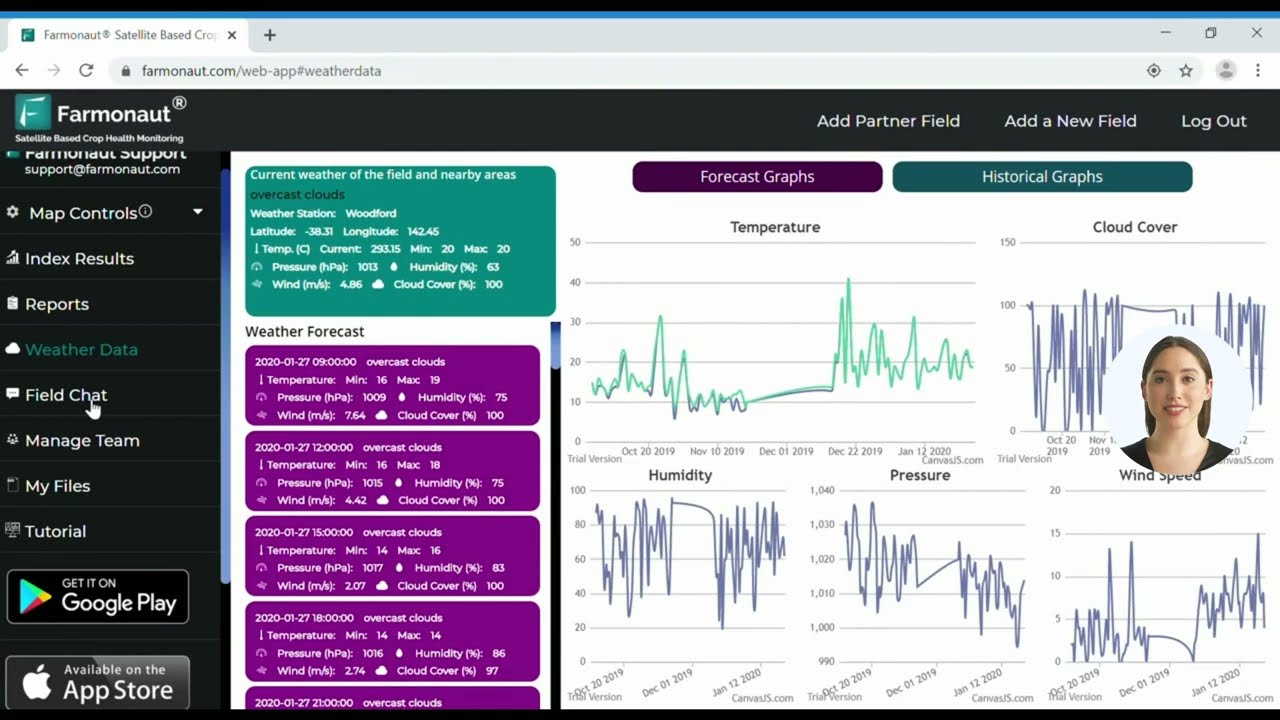
Satellite-based tools fit into this picture as the layer that extends precision agriculture to farms that can’t justify the capital cost of GPS-guided machinery on their own. NDVI (Normalized Difference Vegetation Index) imagery flags plant stress, disease pressure, and nutrient variation without requiring on-farm hardware — Farmonaut’s real-time satellite monitoring is built around that gap specifically, so a farm can get field-health data before deciding whether auto-steer or variable-rate equipment is the next capital purchase. The large-scale farm management tools in the Farmonaut app extend that to multi-field and multi-region oversight for operations managing several properties at once.
2. AI and Data Analytics on the Farm
AI and data analytics in American agriculture today are best understood as the software layer riding on top of the hardware adoption numbers above — the GPS, yield monitors, and soil-mapping systems already installed on 52-70% of US farms generate the field-level data that predictive models need to be useful. USDA has not published a standalone national adoption rate for AI-specific tools (as distinct from the precision-ag hardware in Section 1) in the sources reviewed for this article, so any percentage claiming to measure “AI adoption” specifically should be checked against the original ERS or NASS release before it’s repeated — treat unsourced adoption percentages for AI tools as marketing claims, not USDA figures, until you can verify them.
What the underlying hardware adoption numbers do support is a reasonable inference: since 68% of large-scale crop farms already run yield monitors and soil maps (ERS, 2023), that same group is the most likely near-term adopter of AI layers that consume that data — commodity price forecasting, disease-risk modeling from satellite imagery history, and automated input-timing recommendations. Modular, subscription-based tools such as Farmonaut’s mobile and web apps lower the entry cost for midsize farms that have the data infrastructure but not the in-house analytics team a large operation might run.
Concrete applications where satellite and AI data intersect on US farms today:
- Jeevn AI Advisory System from Farmonaut: real-time crop advisory keyed to field location and observed weather
- Yield prediction adjusted in-season as weather and disease data update
- Blockchain-recorded data supporting traceability claims from field to buyer
The honest caveat for anyone researching “ag trends” around AI specifically: this is the area of the seven trends here with the thinnest published USDA measurement. The method for tracking it going forward is to watch for the next ARMS technology module from ERS, which is where auto-steer and yield-monitor figures originate, and to check whether it adds an AI/predictive-analytics category — as of this review it has not, per the ERS publication referenced above.
3. Autonomous Machinery and Robotics
Autonomous machinery — self-driving tractors, robotic harvesters, automated sprayers — sits one layer beyond the GPS auto-steer adoption already covered: auto-steer keeps equipment on a guided line with a human still in the seat, while autonomy removes the operator for defined tasks. Because USDA’s most recent published figures (ERS, 2023) measure auto-steer adoption (70% large farms, 52% midsize) rather than full autonomy specifically, there is no verified national percentage for autonomous-only equipment in the sources available here. A farm evaluating this trend should treat auto-steer adoption as the leading indicator — full autonomy adoption tends to follow guidance-system adoption within the same large-farm segment first.
- Self-driving tractors extending working hours without proportionally extending labor hours
- Robotic pickers aimed at specialty crops where seasonal labor gaps are most acute
- Automated sprayers and scouting drones reducing pass counts on large acreage
Labor cost and availability are the two forces pushing this trend regardless of the exact adoption percentage — that reasoning holds independent of any single year’s labor statistics, which is why it belongs in a durable trends article rather than a number that will look dated in twelve months. These systems integrate with fleet coordination tools such as Farmonaut’s Fleet Management product, which tracks equipment utilization and routing across multiple fields or properties.
What the data supports and doesn’t: it’s accurate to say autonomy adoption builds on an auto-steer base already present on a majority of large farms (70%, ERS 2023) and just over half of midsize farms (52%). It would not be accurate to state a specific “% of US farms use autonomous tractors” figure, because that number isn’t in the USDA releases checked for this article — if a reader needs that figure for a business case, the correct next step is to check ERS’s ARMS technology reports directly for any newer module that isolates full autonomy from guided-steering adoption.
4. Regenerative and Sustainable Practices
The measurable edge of the sustainability conversation in American agriculture today is certified organic production, and it’s smaller than most trend pieces imply: 3.6 million acres across 17,445 certified organic operations nationwide, per USDA NASS’s Census-linked organic production data from 2021. Set against 2026’s combined 95.3 million corn acres, 85.4 million soybean acres, and 42.7 million wheat acres, organic acreage is under 2% of just those three conventional crops’ planted area. That’s not a criticism of the regenerative-agriculture movement — it’s a scale check that anyone budgeting a transition to certified organic, or evaluating a supplier’s sustainability claims, should have in hand.
Practices grouped under “regenerative agriculture” — no-till and reduced tillage, cover cropping, integrated livestock, carbon monitoring — don’t require organic certification and are adopted at higher rates than the organic-acreage figure suggests, but this brief does not carry a sourced USDA percentage for no-till or cover-crop adoption specifically. The method to get that figure: USDA’s Conservation Effects Assessment Project (CEAP) and the Census of Agriculture’s tillage-practice tables are the two places that data is tracked; check NASS’s Census of Agriculture release for the most recent tillage-practice breakout before citing a specific percentage.
- No-till and reduced tillage to preserve soil structure and water retention
- Cover cropping between cash-crop seasons to reduce erosion and feed soil microbes
- Integrated livestock and rotational grazing to diversify farm income and soil inputs
- Carbon credit and carbon footprint programs that monetize verified practice changes
Satellite-based monitoring and blockchain traceability platforms — the kind Farmonaut provides — matter here because carbon and sustainability claims increasingly need third-party verification to be marketable, not just practiced. That’s a documentation problem as much as a farming-practice one, and it’s where remote imagery does something a soil sample alone can’t: create a dated, field-level record over multiple seasons.

5. Smart Irrigation and Water Management
Water management is one of the two trends in this article (alongside digital marketplaces) where the research brief compiled for this review did not turn up a sourced USDA adoption figure specific to smart irrigation, IoT soil-moisture sensors, or variable-rate drip systems. Rather than fill that gap with an estimate, here is the direct path to the real number: USDA NASS runs an Irrigation and Water Management Survey following each Census of Agriculture, and that survey is the authoritative source for irrigation-technology adoption by state and by system type (drip, pivot, flood). A reader in a drought-exposed region — the Plains, the Midwest during dry years, or California’s irrigated valleys — should pull that survey directly rather than rely on a percentage repeated from a secondary source.
What is verifiable and durable regardless of any single year’s adoption percentage: satellite-based soil-moisture monitoring and IoT field sensors are the two technology categories driving this trend, and the economic logic is straightforward — water costs and regulatory exposure both rise with scarcity, so metering water use precisely pays back faster in drought-exposed regions than in consistently well-watered ones. That reasoning holds whether the current adoption rate is 20% or 60%, which is exactly the kind of spine that keeps this section useful after the underlying numbers change.
- IoT sensors and satellite-based moisture monitoring feeding precision irrigation controls
- Cloud-based alerts for predicted drought stress or excess soil moisture
- Variable-rate drip irrigation matching delivery to real-time plant water needs
Farmonaut’s satellite tools generate automated alerts for water stress or runoff risk at the field level, and for operations managing irrigation across multiple properties, that data integrates with the Agro Admin App for centralized scheduling and compliance tracking.

Real-time soil-moisture maps are accessible via web and mobile access without requiring a farm to install its own sensor network first — useful for a midsize operation testing whether the investment case for permanent IoT infrastructure holds before committing capital.
6. Digital Marketplaces and Traceability
Direct-to-consumer sales, blockchain traceability, and farm-to-table platforms are reshaping how a portion of US production reaches buyers, but — like irrigation adoption — this article’s research brief does not carry a sourced USDA percentage for the share of farms selling through digital or direct channels. USDA’s Agricultural Marketing Service (AMS) tracks local and regional food market data, including direct sales figures from the Census of Agriculture’s direct-to-consumer and local food tables; that is the correct source to check for a current percentage rather than a repeated industry estimate.
- Web and mobile platforms enabling direct sales to local consumers or specialty buyers
- Blockchain traceability verifying origin and practice claims from field to point of sale
- Carbon-footprint and environmental-impact reporting tools adding documented value to a sale
- Identity-marketed crops — heritage, organic, regenerative — sold on provenance rather than commodity price alone
The durable point here, independent of any specific adoption percentage: traceability and direct sales both function as documentation businesses as much as farming ones. A buyer paying a premium for a verified-origin or verified-practice claim needs that claim backed by a dated, field-level record — which is the same data infrastructure discussed under regenerative practices above, reused for a market-access purpose instead of a compliance one.
7. Labor, Workforce, and Rural Connectivity
Labor availability and cost are the forces referenced throughout Sections 1, 3, and 5 above as the underlying driver for auto-steer, autonomy, and irrigation-automation adoption — but this article’s research brief does not carry sourced current figures for farm labor headcount, wage rates, or rural broadband coverage. Two sources carry that data reliably going forward: USDA NASS’s Farm Labor report (issued twice yearly, covering wage rates and worker counts by region) and the Bureau of Labor Statistics’ Quarterly Census of Employment and Wages for agricultural-sector employment trends. Rural broadband coverage, which gates whether a farm can actually use cloud-based precision-ag or IoT tools at all, is tracked by the FCC’s National Broadband Map.
- Automation reducing per-acre labor need without eliminating it entirely — the same auto-steer and autonomy categories covered above
- Rural broadband expansion as a prerequisite for cloud-based tools, not an optional add-on
- Workforce training in equipment automation, data systems, and drone maintenance as a distinct skill category from traditional field labor
Farmonaut’s tools are built to run on standard mobile and web access rather than requiring dedicated on-farm broadband infrastructure, which matters directly for the connectivity gap named above — a farm in a low-connectivity area can still pull satellite-derived field data through a standard mobile connection rather than needing a fixed high-bandwidth line.

For a reader tracking “changes in agriculture” in the labor category specifically: the method is to compare NASS Farm Labor releases year over year rather than trust a single cited figure, since wage rates and worker counts move with both the general labor market and crop-specific seasonal demand.
Tool: Precision-Ag ROI Estimator for Your Acreage
Use your own acreage and per-acre input cost to see what a precision-ag input-waste reduction is worth on your farm, rather than relying on a national average that may not match your operation’s size bracket.
Estimated annual input savings from adding auto-steer guidance:
Assumptions: this estimates input-cost savings only, from reduced overlap and skip when adding GPS auto-steer guidance to existing equipment. It excludes yield gains, equipment financing cost, and labor-time savings. The 52%/70% adoption figures are USDA ERS’s 2023 midsize/large-scale farm rates and are shown for context, not as your farm’s guaranteed outcome — your actual overlap waste depends on field shape, existing equipment, and operator experience.
Satellite Insights for American Farming: The Farmonaut Factor
Across every trend above, the recurring constraint is the same: the data that makes precision agriculture, AI advisory, sustainability documentation, and traceability claims possible has to come from somewhere, and building it on-farm (sensor networks, drone fleets, in-house analytics) is a capital commitment most midsize operations can't justify alone. We at Farmonaut built our platform around closing that specific gap — satellite and AI-derived field data delivered through standard web, mobile, and API access, without requiring on-farm hardware as a prerequisite.



Farmonaut's core value propositions for American farmers:
- Satellite crop monitoring: multispectral, field-level data without on-farm hardware investment
- Flexible API access (developer docs) for integration with existing farm management systems
- AI-powered advisory (Jeevn AI): field-specific recommendations and risk alerts
- Traceability: blockchain-based origin and practice verification (product traceability)
- Environmental impact tracking: carbon footprint documentation (carbon footprinting) supporting regenerative-practice claims
- Fleet and resource management: equipment utilization and routing (fleet management)
- Financing and insurance verification: satellite field data for lenders and insurers (crop loan and insurance)
FAQs on Changes in Agriculture and Ag Trends
-
What is the future of farming in America likely to look like?
Based on current adoption patterns, the near-term future is continued closing of the gap between large-scale and midsize farm technology adoption — auto-steer alone runs 18 percentage points higher on large farms (70%) than midsize farms (52%) as of USDA ERS's 2023 data. The trajectory is toward midsize farms catching up rather than a new technology displacing the current toolset.
-
What does farming in America look like today, in numbers?
Corn, soybeans, and wheat together account for 223.4 million planted acres in 2026 (95.3M corn, 85.4M soybean, 42.7M wheat, USDA NASS), while certified organic production covers 3.6 million acres across 17,445 operations as of the 2021 Census-linked survey. Precision-ag hardware — GPS auto-steer and yield monitors — is used on a majority of large farms and just over half of midsize farms.
-
What are the biggest ag trends right now?
The trend with the strongest published data behind it is precision-agriculture hardware adoption (auto-steer, yield monitors, soil mapping), tracked by USDA ERS. Trends like AI analytics, smart irrigation, digital marketplaces, and rural connectivity are real and active but lack a single standalone USDA adoption percentage in current public data — track them through ERS's ARMS reports, NASS's Irrigation Survey, USDA AMS local food data, and NASS Farm Labor reports respectively.
-
Is agriculture in the United States shifting toward organic production?
Not at scale yet by acreage: 3.6 million certified organic acres is under 2% of the combined 2026 corn, soybean, and wheat acreage alone. Organic remains a distinct, smaller production category rather than a majority direction for US row-crop agriculture.
-
How does precision agriculture address current farming challenges?
Precision agriculture enables targeted application of water, fertilizer, and pesticides based on field-zone data, which cuts input waste from over-application. USDA ERS's 2023 figures show this technology already reaches most large farms (70% auto-steer) and just over half of midsize farms (52%), so the open question for most operations is expansion within an existing adoption curve, not a leap into unproven territory.
-
Does "animal for farming" fit into these trends?
Livestock integration appears in this article specifically as one regenerative-agriculture practice — rotational grazing and integrated livestock systems that diversify soil inputs and farm income (see Section 4). Broader livestock-specific technology and economics are outside the scope of the USDA row-crop and precision-ag data cited here.
-
How does farming in Latin America compare on these trends?
This article is sourced entirely from USDA data covering US agriculture and does not carry verified Latin American adoption figures. A reader researching farming trends in Latin America should consult the FAO or World Bank agricultural data for that region rather than extrapolate from the US figures above, since farm-size distribution, mechanization rates, and crop mix differ substantially.
-
How can farmers get started with satellite monitoring?
Mobile, web, and API-based tools such as Farmonaut provide field-level NDVI, water-stress, and crop-health data without requiring an on-farm sensor network first — useful for testing the case before a larger technology investment.
The Future of Farming in America: What to Watch
The future of American agriculture is not a single forecast — it's a set of adoption curves that can be tracked with public data every season. The clearest one to watch: whether the 18-point gap between large-scale (70%) and midsize (52%) auto-steer adoption narrows in the next USDA ERS ARMS release, which would signal precision agriculture moving from a large-farm advantage to a sector-wide baseline. The acreage side is equally trackable — USDA NASS reissues planted-acreage figures every March and June, so the 95.3 million corn / 85.4 million soybean / 42.7 million wheat acreage for 2026 is a snapshot, not a fixed fact, and should be checked against the NASS Newsroom each season.
For the trends without a current USDA percentage in this review — AI analytics, smart irrigation adoption, digital marketplace penetration, and rural labor and connectivity — the durable takeaway isn't a number, it's the method: ERS's ARMS technology modules, NASS's Irrigation and Water Management Survey, USDA AMS local food data, and NASS Farm Labor reports are the specific sources that will carry those figures whenever they're published, and checking them directly beats repeating an unsourced industry estimate.
Whether you manage a family farm, a large operation, or work in agricultural policy, the practical next step is the same: match your technology investment decisions to your farm's actual size bracket and adoption context, using verified USDA data rather than an industry-wide average that may not describe your operation.




Farmonaut Subscriptions & Resources
We at Farmonaut offer subscriptions for individual farmers, agribusinesses, and government agencies, providing satellite, AI, and blockchain-based tools for the trends covered above.
Explore more at:
• Farmonaut Web & Mobile App
• API for Integrations (Developer Docs)
• Carbon Footprinting Solutions
• Product Traceability (Blockchain)
• Satellite Verification for Crop Loans/Insurance
• Fleet/Resource Management
• Large-scale Farm Management
Match your next technology investment to your farm's actual size bracket and adoption data — start with Farmonaut.

 KJBN Labs
 SFX
 BACF Africa
 Doodlakine
 Exurbia Geospatial
 FieldZero
 Indico Company
 Kubota
 FFBS
 Jontra
 Tucor

