

Rural finance · FY2026 program guide
USDA Rural Development Programs: Loans, Grants, Limits
USDA Rural Development finances rural housing, community buildings, utilities, business and energy through more than 40 programs (CRS, 2026). Here are the loan fees, grant shares and limits for fiscal year 2026 (October 2025 to September 2026), and what has changed. No fiscal year 2027 fee notice had been published as of 26 October 2026.
Key takeaways
- Rural Development has more than 40 programs run by three agencies; farm ownership and operating loans come from the separate Farm Service Agency (CRS, July 2026).
- Fiscal year 2026 (Oct 2025-Sep 2026) guarantee fees range from 1.0% to 3.0%, with annual fees up to 0.55% (USDA OneRD notice); no FY2027 notice was found as of 26 October 2026.
- Community Facilities grants are capped at 75%, 55%, 35% or 15% of eligible cost, depending on town size and income, plus a 60% tier only for towns hit by a major disaster (7 CFR 3570.63).
- The guaranteed home loan income limit is the greater of three measures, not a flat 115% of area median income (7 CFR 3555.10); USDA published new 2026 limits on 13 July 2026.
- REAP grants are being rebuilt: the old funding notice was rescinded on 15 April 2026 and a new rule needs projects built before applying.
In this article
- What USDA Rural Development does
- Loans, guarantees and grants: how they differ
- Housing: Section 502 and 504 loans
- Community facilities: grants and loans for local buildings
- Business and energy programs for farms
- FSA farm loans: the other USDA lender
- How the money is split in fiscal year
- Where the farm bill stands
- How to apply: five steps
- Maps and records for rural projects
- FAQ
USDA Rural Development is the part of the US Department of Agriculture that lends, guarantees loans and gives grants for rural housing, community buildings, water systems, businesses and energy. The Congressional Research Service counts more than 40 programs in this mission area (CRS, July 2026), run by three agencies: the Rural Housing Service, Rural Business-Cooperative Service and Rural Utilities Service. This guide sorts the main loan and grant programs, shows the fee and grant-share rules in force for fiscal year 2026, and flags what has changed or ended.
It is written for farmers, ranchers and rural business owners. Rules and funds change often, so check each point with your USDA Rural Development state office before you apply. This page is general information, not legal or financial advice.
What USDA Rural Development does
Rural Development (RD) is not one loan. It is a group of programs, and each has its own applicant, purpose and rules. They fall into four groups.
- Housing (Rural Housing Service): home loans, loan guarantees, and repair loans and grants for rural homeowners.
- Community facilities (Rural Housing Service): fire stations, clinics, schools and other public buildings.
- Business and energy (Rural Business-Cooperative Service): guaranteed business loans, energy projects and producer grants.
- Utilities (Rural Utilities Service): water, waste water, electric and broadband.
One common mix-up: farm ownership and operating loans come from the Farm Service Agency (FSA), a different USDA agency, not from Rural Development. The CRS lists only the three agencies above as RD agencies. FSA is covered in its own section below.
Congress sets the money for each program in annual appropriations. Each program has its own funding line, so there is no one answer to which area gets priority. The chart in the funding section below shows how uneven the amounts are for a few programs in fiscal year 2026.
▶ How farm technology affects rural towns: money, jobs and internet. · 3:50
Loans, guarantees and grants: how they differ
A direct loan comes from USDA itself. A guaranteed loan comes from a bank or other approved lender, and USDA promises to repay part of it if the borrower defaults. A grant does not have to be repaid, but it usually covers only part of a project.
For guaranteed loans, the lender pays USDA a guarantee fee and an annual fee. USDA sets them each fiscal year. The table shows the fiscal year 2026 fee notice (October 2025 to September 2026), the latest we found on 26 October 2026. Fiscal year 2027 began on 1 October 2026 and a newer notice may change these rates, so confirm them with your lender or state office (USDA OneRD notice, Federal Register, March 2026).
| Guaranteed loan type | Guarantee fee | Annual fee | Guarantee share |
|---|---|---|---|
| Business and Industry, under $5M | 3.0% | 0.55% | 85% |
| Business and Industry, $5M-$25M | 3.0% | 0.55% | 80% |
| Community Facilities | 1.25% | 0.50% | 80% |
| REAP energy loans | 1.0% | 0.25% | 80% |
| Water and Waste Disposal | 1.0% | None | 90% |
The notice also lists a reduced-fee Business and Industry class and a higher guarantee for remote Alaska projects. The agency says it will publish a new notice if fees change. The rules let lenders pass some of these costs to the borrower, so ask yours how they appear in your loan.
Chart
Guarantee fee and annual fee by loan type
Percent, fiscal year 2026 rates effective 1 October 2025
Housing: Section 502 and 504 loans
Housing is the best-known part of Rural Development. Our separate page on USDA rural development home loans and loan rates goes deeper. Here are the rules that matter for a farm family.
Guaranteed home loans
The guaranteed program is for moderate-income households. The rule defines “moderate income” as the greater of three measures: 115 percent of the US median family income, the average of the statewide and state non-metro median family income, or 115/80ths of the area low-income limit for the county (7 CFR 3555.10). So the limit is not a flat “115% of area median income”. It varies by county and household size. USDA published new 2026 limits on 13 July 2026 and updated its eligibility tools (USDA Rural Development bulletin, 16 July 2026).
The loan may not exceed the lesser of the appraised value plus the up-front guarantee fee, or the purchase price plus eligible costs (and a new home that cannot meet the inspection and warranty rules is limited to 90 percent), so the rule itself does not require a down payment (7 CFR 3555.103). The regulation caps the up-front fee at 3.5 percent and the annual fee at 0.5 percent (7 CFR 3555.107). As reported by lenders, loans obligated on or after 1 October 2025 carry a 1 percent up-front fee and a 0.35 percent annual fee (Pennymac, 16 September 2025). That is a lender notice, not the USDA text, so confirm the current figures with your lender.
Funding can run short. The rule lets USDA limit guaranteed loans to first-time buyers and veterans when funds fall short. The same lender notice said commitment authority was temporarily unavailable from 1 October 2025, so lenders issued conditional commitments. A USDA Rural Development bulletin of 6 October 2026 says fiscal year 2027 funding for this program has been made available (USDA bulletin, 6 October 2026).
Direct loans and repair help
Direct Section 502 loans are for low and very low-income households. The lender-side test is a repayment ratio: housing costs up to 33 percent of repayment income and total debt up to 41 percent, with room for compensating factors (7 CFR 3550.53).
Section 504 helps owners fix their homes. Applicants must own and live in the home and have income at or below the very low-income limit. Grants go only to applicants aged 62 or older (7 CFR 3550.103). Grants pay to remove health and safety hazards or to make a home usable for people with disabilities. Loans can cover general repairs. Neither can pay for a new dwelling.
What “rural” means
The housing law defines a rural area by population. It covers places of up to 2,500 people, places of up to 10,000 that are rural in character, and some places up to 20,000 outside metro areas with a serious lack of mortgage credit. Some areas that were classed as rural before 1 October 1990 and lost that status through later census data keep it until the 2030 census data, if they have up to 35,000 people, are rural in character and have a serious lack of mortgage credit (42 U.S.C. 1490). Check an address on USDA’s eligibility map before you rely on it.
Community facilities: grants and loans for local buildings
The Community Facilities program serves public bodies and nonprofits, not individual farmers. Farmers meet it as taxpayers and users: the new fire hall or clinic. Grants are on a sliding scale. A smaller, lower-income community can get a larger share of the project paid by grant (7 CFR 3570.63).
This chart shows the grant-share caps in the regulation. Grants may not pay more than 75 percent of the cost to develop a facility.
Chart
Maximum grant share of project cost
Percent of eligible cost, by size of the community served
Business and energy programs for farms
Two RD programs often come up for farm businesses: the Business and Industry guaranteed loan and the Rural Energy for America Program (REAP). The first backs bank loans to rural businesses and uses the fees in the table above.
REAP has changed
Older guides describe REAP as a steady source of solar and efficiency grants. That is no longer the case.
- On 15 April 2026 USDA rescinded the REAP funding notice for fiscal years 2025 to 2027. Applicants without a fully executed agreement must apply again under the new rule (Federal Register, 15 April 2026).
- A final rule with comment period, issued in the Federal Register on 1 October 2026 with a 30-day comment period, turns REAP into a post-completion model. Projects must be built and running before the application, and applicants send 12 months of actual energy data (USDA final rule, October 2026). The rule also proposes one national scoring process in place of state competitions, and makes multi-location projects ineligible.
If you planned a solar array or grain-dryer upgrade, read the rule text and talk to your state office before you spend money.
▶ Ten small agriculture business ideas for people without a farm, with start-up scale in mind. · 6:03
FSA farm loans: the other USDA lender
The Farm Service Agency lends for land, equipment and operating costs. These loan limits were shown on FSA’s pages when we checked them on 26 October 2026.
- Direct farm ownership loans: up to $600,000; guaranteed ownership loans: up to $2,558,000 (FSA farm ownership loans).
- Operating microloans: up to $50,000 per loan (FSA operating microloan).
- The Down Payment Program asks 5 percent down from beginning farmers and ranchers and finances up to 45 percent of the price.
Congress is also working on higher FSA limits. Both farm bill proposals would raise maximum loan amounts (CRS, July 2026).
How the money is split in fiscal year
Appropriations for individual programs vary a lot. The chart picks six lines from the CRS rural development primer. It is a sample and not the total for Rural Development, which also runs large housing and utility loan programs funded in other ways.
Chart
Fiscal year 2026 appropriations, selected RD programs
US$ million; six lines from the CRS primer, not total Rural Development funding; the relending bar is a loan subsidy that supports $9M of loans
Where the farm bill stands
Many rural development programs are written into the farm bill. The 2018 farm bill was last extended through fiscal year 2026 (Public Law 119-37). CRS notes that authorizations for many RD programs were set to expire on 30 September 2026, and trade press reports in early October 2026 that no further extension was passed, so check which authorizations still apply. The House passed the Farm, Food, and National Security Act of 2026 (H.R. 7567) on 30 April 2026 by 224 to 200, and a Senate committee reported S. 5526 (CRS, updated 22 October 2026). The CRS describes both only as proposals. They would extend most RD programs through fiscal year 2031, create a Rural Development Innovation Center, and widen loan refinancing for rural health care facilities.
Until a new law passes, treat any rule in a news story as unfinished. Look for the date and the Federal Register number.
How to apply: five steps
- Pick the program that fits. Housing, a community building, a business loan and a farm purchase each go to a different door.
- Check the place. Use USDA’s address checks for housing and community programs.
- Check the income test. Use the current limits for your county and household size.
- Talk to a lender or your state office. Guaranteed loans start with an approved lender. For direct programs, start with your RD state office.
- Keep records. Land maps, receipts and energy bills support most applications.
Use the calculator to test your income against a limit and to see what the guarantee fees add.
Try the numbers for your own farm below.
Calculator
How close is my income to the limit, and what do the fees add?
Enter your own household income, your county limit and the loan details.
- Income as share of limit: 98.3 %
- Loan amount before fees: $250,000
- Up-front fee: $2,500
- Annual fee, first year: $875
- Annual fee per month, first year: $73
Example values only, not a forecast or a quote. Look up your county limit on USDA’s income eligibility tool; the 120,000 shown is a made-up round number. The fee rates (1.00% up-front, 0.35% annual) are the figures in a lender notice for loans obligated from 1 October 2025 (fiscal year 2026); fiscal year 2027 rates may differ, so confirm them with your lender. The annual fee is shown on the starting loan amount, so the real figure falls as the balance falls. Fees may be paid by the lender or passed to you.
Maps and records for rural projects
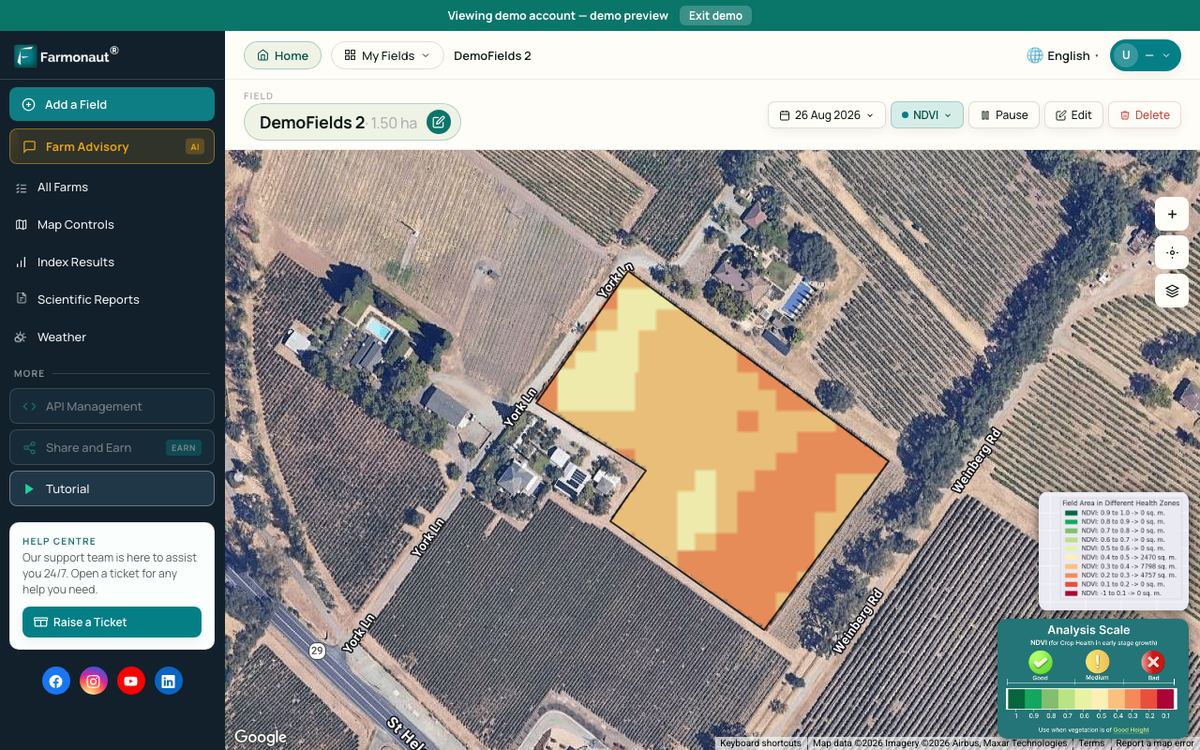
Some lenders and programs ask for maps and field records. Farmonaut Satellite + AI Farm Monitoring System gives farm owners vegetation maps of their own fields over a season. These show plant cover, not whether you qualify for a program, and they replace none of the USDA paperwork.
▶ How satellite NDVI maps show crop stress across a large farm. · 4:09
FAQ
What is USDA Rural Development?
It is the USDA mission area that finances rural housing, community facilities, utilities, business and energy projects. CRS counts more than 40 programs, run through three agencies (CRS, July 2026).
Do USDA Rural Development programs prioritize housing, business or infrastructure?
No single priority is set. Congress funds each program by appropriation, and amounts differ a lot, as the chart of fiscal year 2026 lines shows. Within a program, USDA applies its own scoring and, in some cases, priorities written into law.
How do communities apply for USDA Rural Development funding?
Start by contacting your RD state office, which the RD website lists by state. Guaranteed loans are made by approved lenders, so you may begin with a bank or other lender.
How do Rural Development grants differ from loans?
Loans are repaid with interest. Grants are not, but they cover only a share. Community Facilities grants are capped at 15 to 75 percent of eligible costs depending on town size and income (there is also a 60 percent tier for certain disaster-hit towns). Section 504 home repair grants go only to owners aged 62 or older.
Is rural housing funding mostly grants or loans?
Section 502 help is loans, either direct or guaranteed. Section 504 offers both repair loans and repair grants, and the grant is limited to applicants aged 62 or older (7 CFR 3550.103).
Who runs these programs at state and local level?
Each state has an RD state office. The fee notice for fiscal year 2026 tells readers to contact their RD State Office about how it is put into practice.
Check the program notice, your lender and local rules. Fees, limits and funding change by fiscal year.
Related pages on our site: crop loans and insurance, farm carbon footprint tracking, product traceability, farm fleet management, weather data for farms, satellite data API.
Farmonaut crop monitoring
See your own fields from space
Draw your fields once and Farmonaut shows satellite vegetation maps for them through the season, on web, Android or iOS.
Keep reading
Sources
- USDA Rural Development, OneRD Annual Notice of Guarantee Fee Rates, FY2026 (Federal Register, March 2026): public-inspection.federalregister.gov
- USDA RBCS, Notice of Rescission of Funding Opportunity for REAP (Federal Register, 15 April 2026): govinfo.gov
- USDA RBCS, REAP final rule with comment period, RIN 0570-AB13 (Federal Register, October 2026): public-inspection.federalregister.gov
- CRS, Farm Bill Primer: Rural Development Title, IF13249 (updated 22 October 2026): everycrsreport.com
- CRS, The 2026 Farm Bill: Comparison of the House and Senate Bills with Current Law, R48918 (July 2026): everycrsreport.com
- 7 CFR 3555.10, Definitions (Guaranteed Rural Housing Program): law.cornell.edu
- 7 CFR 3555.103, Maximum loan amount: law.cornell.edu
- 7 CFR 3555.107, Application for and issuance of the loan guarantee: law.cornell.edu
- 7 CFR 3550.53, Repayment ability (direct single family housing): law.cornell.edu
- 7 CFR 3550.103, Eligibility requirements (Section 504): law.cornell.edu
- 7 CFR 3570.63, Community Facilities grant limitations: law.cornell.edu
- 42 U.S.C. 1490, Rural and rural area defined: law.cornell.edu
- USDA Rural Development, SFH Guaranteed Loan Program Updated Income Limits for 2026 (bulletin, 16 July 2026): content.govdelivery.com
- Pennymac, Funding for USDA Rural Housing 2026 Fiscal Year (lender announcement, 16 September 2025): corr.pennymac.com
- USDA Farm Service Agency, Farm Ownership Loans: fsa.usda.gov
- USDA Farm Service Agency, Operating Microloan: fsa.usda.gov
- 7 CFR 3550.10, Definitions (direct single family housing): law.cornell.edu
- USDA Rural Development, Single Family Housing Guaranteed Loan Program bulletin (6 October 2026): content.govdelivery.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Raintree Computing
 Agricultural Credit Policy Council
 BayWa
 MCSOD
 Marei Nursery
 eKGIS
 Mostas Tech
 Native Seeds
 Andex
 FCF India
 Unifrutti Gulf
 Deluxe Conseil
 TVS Electronics
 WICO
 Chimera Innovation
 SkyHarvest

 Licence holder · Niger · Gold
 Licence holder · Nigeria · Gold + lithium










