

Agricultural Technology Companies: US Market & Revenue Guide
Reviewed September 2026 against USDA Economic Research Service, IMARC Group, and PS Market Research data.
Try it: Enter values above to calculate. →
The US agricultural equipment market was valued at $39.4 billion in 2024, according to PS Market Research, while the narrower US agricultural robots market reached $3.43 billion in 2025 per IMARC Group — two very different numbers because they measure different things: one is hardware sales across all farm machinery, the other is autonomous and robotic systems specifically. Layer in USDA’s own adoption survey, which found only 27% of US farms and ranches used any precision agriculture practice as of 2023, and you get the real picture: this is a market with billions in vendor revenue chasing a customer base that is still, by USDA’s own count, a minority adopter.
This page breaks down what “agricultural technology company” actually means as a revenue category, which USDA and market-research numbers are load-bearing versus marketing filler, and how to evaluate a company or a robot vendor against real US data rather than a press release. Every figure below carries its source and its date, plus a note on how to pull a fresher number when one becomes available.
USDA Adoption Data: Who’s Actually Using Precision Agriculture
Before comparing vendors, it helps to know how many US farms are actually buying what these companies sell. USDA’s National Agricultural Statistics Service found that 27% of US farms and ranches reported using precision agriculture practices in 2023 — that’s the headline adoption number, and it covers the full range of farm sizes, from small operations to large commercial farms.
The number that matters more for revenue forecasting is the large-farm breakdown. Among large-scale US crop-producing farms — the segment that buys the most expensive equipment — USDA found 70% used GPS guidance autosteering systems and 68% used yield monitors and soil maps, both as of the 2023 survey year. That gap between the 27% all-farm figure and the 68–70% large-farm figures tells you where agtech revenue actually concentrates: a small number of large operations account for most precision-ag spending, while the long tail of smaller farms has not adopted at anywhere near the same rate.
These figures come from the USDA Economic Research Service Chart of Note on precision agriculture adoption. USDA NASS runs its full Census of Agriculture every five years — the last full cycle was 2022, published in 2024, with the next scheduled for 2027 — but interim survey updates on specific technology adoption appear between census years. To check whether newer adoption figures have been published, search the USDA NASS QuickStats database for “precision agriculture” as a survey variable.
Agricultural Technology Companies: Market Sizing Breakdown
“Agricultural technology company” gets applied to businesses selling wildly different things, which is why market-size estimates for the sector vary by billions of dollars depending on what’s included. Three US-specific figures worth keeping separate:
- $39.4 billion — the total US agricultural equipment market in 2024, per PS Market Research. This covers physical machinery: tractors, harvesters, planters, and attachments, whether or not they carry smart features. It is the broadest of the three numbers because it includes plenty of equipment with no digital component at all.
- $25 billion — the US AgTech market in 2024, according to Mobility Foresights market research. This is the closer proxy for “agricultural technology companies” as a distinct category: software, data platforms, sensors, and digital services layered onto or alongside farm operations, rather than the machinery itself.
- $3.43 billion — the US agricultural robots market in 2025, per IMARC Group. This is the narrowest slice: autonomous and semi-autonomous machines specifically, a subset of both the equipment market and the AgTech market above.
There is no single USDA source that breaks the agtech category down further into software-versus-hardware-versus-services revenue splits — market research firms define these categories inconsistently with each other, which is exactly why the three numbers above don’t nest cleanly. If you need a sector-specific revenue split for investment or competitive analysis, you’ll need to go to individual company 10-K filings and add up segment revenue by hand, since no aggregator currently standardizes this across the industry.
Agricultural Robot Companies and the $3.43 Billion Market
Anyone searching for agricultural robot companies is usually trying to gauge whether the category is real money or still mostly demo units. The data says real money, growing fast from a small base: the US agricultural robots market was $3.43 billion in 2025, and Markets and Markets projects a 27.3% compound annual growth rate for the US agricultural robot market from 2025 to 2030. At that growth rate, a market this size roughly doubles every 2.8 years if the trajectory holds — though five-year CAGR projections are directional, not a guarantee, and should be checked against updated reports as they’re released.
In practice, “agricultural robot company” spans several distinct product categories: autonomous tractors and guidance retrofits, robotic weeders and sprayers, automated harvesters for specialty crops, and robotic milking or livestock-handling systems. USDA’s adoption data above only tracks GPS autosteering and yield monitoring at the national survey level — it does not break out adoption rates for drones, robotic weeders, or other specific hardware categories, so there is no USDA figure to cite for “percentage of US farms using robotic weeders” or similar. Vendor-reported unit sales or the market-research firms named above are currently the only sources for that level of granularity.
AI-driven robotics deployed on Washington state farms illustrate the labor-shortage driver behind this growth: robotics adoption concentrates where seasonal labor is hardest to secure, which is consistent with the equipment-market data showing large-scale operations as the primary buyers.
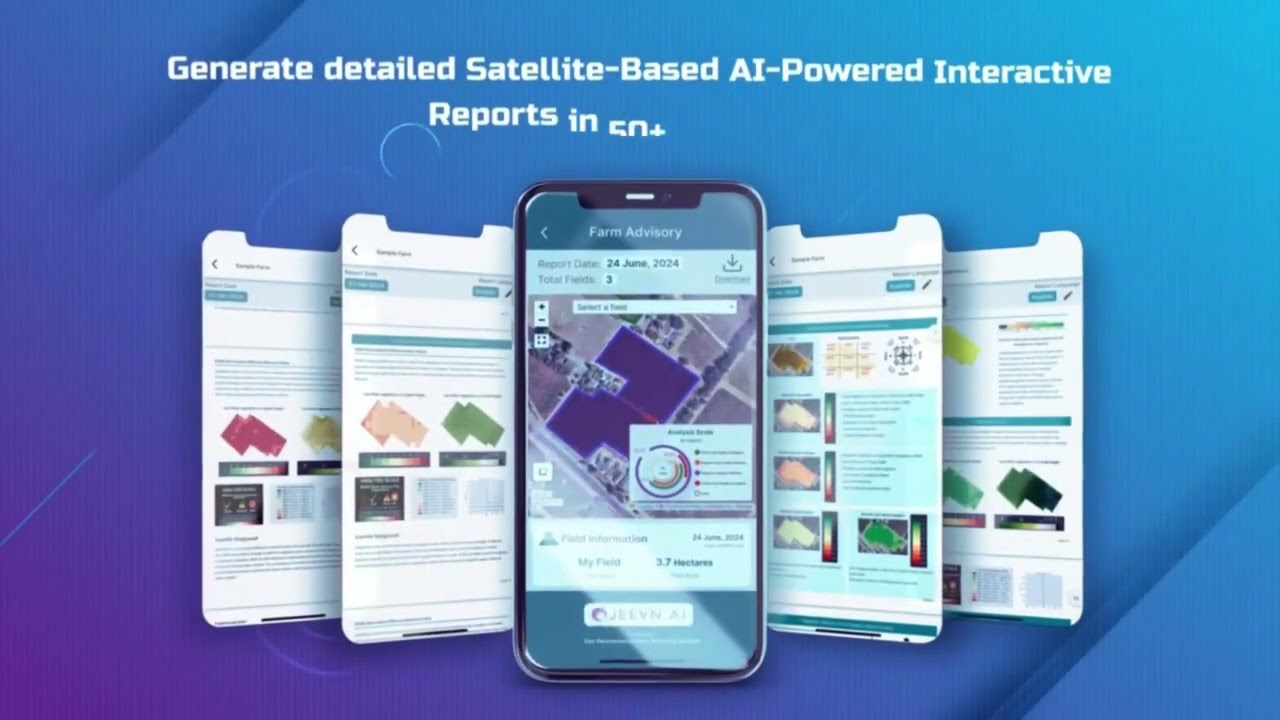
Explore how Farmonaut’s large-scale farm management app leverages satellite and AI-powered analytics to help agribusinesses and growers optimize operations without requiring a robotics capital outlay.

Agricultural Marketing Companies: Where They Fit
“Agricultural marketing companies” is a distinct search from “agricultural technology companies,” and worth separating clearly: the term covers two different kinds of businesses. The first is grain and commodity marketing firms — brokers and advisory services that help producers time sales, hedge price risk, and move crops to buyers. The second, increasingly overlapping category, is digital marketing and go-to-market firms that specialize in the agriculture sector, helping input suppliers, equipment makers, and agtech companies themselves reach farm-operator customers.
Neither category has a USDA-published revenue figure the way farm-level technology adoption does, because agricultural marketing services aren’t captured in NASS’s Census of Agriculture the way on-farm practices are. If you’re evaluating an agricultural marketing company, the closest checkable proxies are its client roster relative to known equipment and biotech vendors listed in the comparison table below, since those buyers’ revenue figures are at least partially public through SEC filings for the publicly traded names.
Where agtech and agricultural marketing genuinely intersect is digital supply-chain and traceability tooling — platforms that double as both an operational tool and a marketing/provenance claim a brand can make to buyers. Farmonaut’s blockchain-based product traceability platform is an example of that overlap: it’s built as farm-to-buyer tracking infrastructure, but the transparency data it generates is also what a brand uses in its own marketing to retailers and consumers.
How to Rank “Best” Agricultural Technology Companies
There is no single authoritative “best agricultural technology companies” list, and any ranking that claims to be definitive is making an editorial choice about weighting, not reporting a fact. What you can do instead is rank companies against a small number of checkable criteria and see where each one actually stands:
- Revenue scale — pull segment revenue from public 10-K or annual report filings where available; private companies (most robotics startups, many biotech firms) require funding-round disclosures as a proxy.
- US market share within its category — compare against the category totals above ($39.4B equipment, $25B AgTech, $3.43B robots) rather than the market as a whole, since a company dominant in robotics is working with a market 11x smaller than the equipment category.
- Growth trajectory — the 27.3% CAGR figure from Markets and Markets for agricultural robots (2025–2030) is a useful sector-wide benchmark; a company growing slower than its category average is losing relative share even if its absolute revenue is rising.
- Adoption evidence — does the company’s customer base align with USDA’s finding that large-scale farms drive 68–70% adoption of precision tools, or is it targeting the underserved 73% of farms not yet using any precision agriculture practice?
A useful list for cross-referencing named biotech and seed-technology players against current industry coverage is Farmonaut’s roundup of agtech, biotech, seed, and wind technology companies, which tracks company names and focus areas as the sector evolves.

Company Comparison: Revenue, Segment, and Focus
The table below separates companies by the market segment they primarily compete in, so a robotics-focused reader isn’t comparing a company against biotech peers three times its category size. Revenue figures for private and non-disclosing companies are marked accordingly rather than estimated — check each company’s most recent SEC filing or investor relations page for current figures, since these change annually.
| Company | Primary Segment | Revenue Disclosure | US Market Relevance |
|---|---|---|---|
| Deere & Company | Precision equipment, autonomy | Public (10-K) — check latest annual report | Autosteer/GPS systems overlap directly with USDA’s 70% large-farm adoption figure |
| AGCO Corporation | Farm equipment, connected machinery | Public (10-K) — check latest annual report | Competes in the $39.4B US equipment category |
| Trimble Agriculture | Guidance, farm management software | Reported within Trimble Inc. 10-K segment data | GPS guidance systems directly measured by USDA adoption survey |
| CNH Industrial (Raven) | Automation, telematics | Public (10-K) — check latest annual report | Autonomous sprayer systems within the robotics growth segment |
| Corteva Agriscience | Seed genetics, gene editing | Public (10-K) — check latest annual report | Biotech segment, separate from equipment/robotics markets above |
| BASF Agricultural Solutions | Crop protection, biotechnology | Reported within BASF SE segment data | Biopesticide and microbial inoculant R&D |
| Pivot Bio | Biofertilizers, microbial nitrogen | Private — funding-round disclosure only | US-focused nitrogen-fixing microbe technology |
| Farmonaut | Satellite monitoring, AI analytics | Private — subscription-based model | Serves the adoption gap below the 27% all-farm precision-ag figure via low-cost satellite access |
Revenue figures change with each fiscal year filing. For publicly traded companies, check the most recent 10-K or investor relations page directly rather than relying on any secondary aggregation, including this table.
Precision Ag ROI Calculator
Use USDA’s adoption benchmarks alongside your own farm’s numbers to estimate where GPS guidance or yield-monitoring investment would land relative to the 68–70% large-farm adoption rate USDA reports.
Enter values above to calculate.
Assumes a one-time system cost and a flat per-acre annual saving; excludes financing costs, maintenance, subscription fees, and yield-side revenue gains. USDA adoption figures are national averages for 2023 and are shown for context, not as a prediction of your specific outcome.
Largest US Agriculture Companies by Revenue
“Largest agriculture companies by revenue” and “largest agriculture companies in the US by revenue” are broader questions than agtech specifically — they pull in commodity traders, food processors, and input manufacturers whose primary business isn’t technology at all. The research base for this article is focused on agtech, precision-ag adoption, and robotics rather than whole-of-sector revenue rankings, so rather than list a set of company revenue figures we can’t verify against the brief here, the reliable method is this: cross-reference the USDA Economic Research Service’s farm sector income data with SEC EDGAR filings for the publicly traded names (Deere, AGCO, Corteva, and others named in the table above all file 10-Ks with segment-level revenue breakdowns), since aggregated third-party “largest companies” lists frequently mix fiscal years and include private-company estimates that can’t be independently checked.
Within the agtech-specific companies this article does cover, market position relative to the $39.4 billion equipment market, the $25 billion AgTech market, or the $3.43 billion robotics market (all figures above) is the more defensible comparison than an unranked “largest overall” claim.

Enhance supply chain authenticity with Farmonaut’s blockchain-based product traceability platform, and reduce operational costs with fleet management for agricultural logistics.
Where Farmonaut Fits: Satellite Data as Infrastructure
Given USDA’s finding that only 27% of US farms use any precision agriculture practice, the addressable gap isn’t more equipment for the 70%-adoption large-farm segment — it’s affordable access for the roughly three-quarters of farms not yet using these tools. Satellite-based platforms compete on that basis: no field hardware to install, calibrate, or maintain, versus the equipment purchases reflected in the $39.4 billion US equipment market figure above.
- Satellite-based monitoring — remote crop, soil, and vegetation tracking without on-farm sensor hardware.
- AI-driven advisory (Jeevn AI) — weather forecasts and input recommendations generated from the same satellite feed.
- Blockchain traceability — supply-chain verification via Farmonaut’s traceability platform.
- Carbon footprint tracking — via Farmonaut Carbon Footprinting tools, supporting ESG reporting requirements.
- Fleet and resource management — through fleet management for agricultural logistics.
Our subscription-based model offers flexible packages for individual farmers, businesses, and governments.
Developers can integrate with our API or access detailed API Developer Docs for custom agriculture, mining, or infrastructure solutions.

Our modular solutions also cover satellite-based crop loan and insurance verification, streamlining farm financing, and crop plantation and forest advisory for environmental stewardship.
Discover our advanced farm management platform for comprehensive agricultural monitoring, or trial our satellite and AI insights for your operations today.

Frequently Asked Questions
What percentage of US farms use precision agriculture technology?
27% of US farms and ranches reported using precision agriculture practices as of the 2023 USDA National Agricultural Statistics Service survey. Among large-scale crop-producing farms specifically, adoption is much higher: 70% use GPS guidance autosteering and 68% use yield monitors and soil maps. Check USDA ERS’s Chart of Note for updates as newer survey data is published.
How big is the US agricultural technology market?
Estimates depend on scope: the US AgTech market was valued at $25 billion in 2024 per Mobility Foresights market research, the broader US agricultural equipment market was $39.4 billion in 2024 per PS Market Research, and the narrower agricultural robots market was $3.43 billion in 2025 per IMARC Group. These are not additive — they overlap and measure different slices of the sector.
What is the growth rate for agricultural robot companies?
Markets and Markets projects a 27.3% compound annual growth rate for the US agricultural robot market from 2025 to 2030. Confirm this against their published report directly, since CAGR projections are periodically revised as new market data comes in.
How do I find the current largest agricultural technology companies by revenue?
There is no single authoritative ranking. Cross-reference SEC EDGAR 10-K filings for publicly traded companies (Deere, AGCO, Corteva, CNH Industrial, and others) against the category-specific market sizes above to see relative position within equipment, biotech, or robotics segments specifically, rather than relying on a single “largest companies” list that may mix fiscal years or include unverified private-company estimates.
Are agricultural marketing companies the same as agricultural technology companies?
No. Agricultural marketing companies are commodity brokers, sales advisory firms, or ag-sector digital marketing agencies — a service category. Agricultural technology companies build the equipment, software, or biotech products themselves. The two overlap mainly in supply-chain traceability tools, where the same data serves both operational and marketing/provenance purposes.
How does Farmonaut fit into the agricultural technology sector?
Farmonaut provides satellite-based crop monitoring, AI advisory, blockchain traceability, and carbon-footprint tracking on a subscription model, targeting the gap below USDA’s 27% all-farm precision-ag adoption rate by removing the on-farm hardware costs that drive the $39.4 billion equipment market figure.
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Nivia
 Doodlakine
 Exurbia Geospatial
 FieldZero
 Indico Company
 Kubota
 FFBS
 Jontra
 Kalustyan
 Tucor
 Geno
 Hayleys Agriculture
 Linx Agritech
 Adinet

