

Reviewed September 2026 against USDA Economic Research Service, USDA NASS Census of Agriculture, and IMARC Group’s US precision farming market analysis.
Try it: Run your own numbers →
IoT farming means sensors, satellite feeds, and connected field hardware replacing guesswork with per-acre data — and in the United States it is already mainstream at scale, not a pilot-stage novelty. USDA’s Economic Research Service found 27% of US farms used at least one precision agriculture practice in 2023, and among large-scale row-crop operations that figure rises to 68% for yield or soil mapping specifically. The open question for most operators isn’t whether to adopt it, but which sensors pay back fastest, which farm-management platform coordinates the data, and how the resulting savings stack up against the subscription and hardware cost.
Table of Contents
- What IoT Farming Actually Means
- US Adoption Data: Who’s Using It and at What Scale
- Sensor Types and What Each One Replaces
- Yield Gains and Resource Savings, by the Numbers
- Calculator: Estimate Your IoT Payback Period
- Coordinating the Data: CRM and Farm-Management Platforms
- Choosing Between Farming Brands and Platforms
- Sector Use Cases: Row Crops, Orchards, and Reclamation Land
- A Durable Checklist for Evaluating Any IoT Farming Setup
- How Farmonaut Fits This Stack
- Frequently Asked Questions
- Conclusion
- Try it: Run your own numbers
What IoT Farming Actually Means
IoT farming is the use of networked, low-power field sensors and satellite-derived indices to give every part of a field, orchard, or reclamation plot its own status update, instead of managing the whole property as one unit. A soil moisture probe reports one zone’s water content; a canopy reflectance sensor flags stress in another; a satellite pass adds a vegetation index across the entire property at once. The distinguishing trait isn’t the hardware, it’s the resolution: decisions get made at the scale of a management zone or individual tree, not a whole 466-acre farm — which happens to be the average US farm size reported in USDA NASS’s 2022 Census of Agriculture, published in 2024.

Farmonaut Web System Tutorial: Monitor Crops via Satellite & AI
US Adoption Data: Who’s Using It and at What Scale
The clearest published figures on IoT and precision agriculture adoption in the US come from two USDA sources, and they tell a story of sharp divergence by farm size. USDA’s Economic Research Service reported that 27% of US farms overall used at least one precision agriculture practice in 2023 — but that average conceals a large gap: 68% of large-scale row-crop farms had adopted yield maps or soil maps, against just 13% of small-scale farms. USDA NASS separately counted 1.88 million total US farms in its 2022 Census of Agriculture (published 2024), with an average farm size of 466 acres.
On the commercial software side, IMARC Group’s analysis of the US precision farming software market found 81% of farms over 5,000 acres had adopted at least one AgTech solution as of 2025, and that 72% of US agriculture software deployments were cloud-based rather than on-premises by the same year. The market-value side is sizable too: Market.us sized the US IoT-in-precision-agriculture market at $2.36 billion for 2024.
The gap between 68% and 13% is the single most useful number in this data set for anyone budgeting an IoT rollout: it says the return on sensor investment scales with acreage, and a 40-acre operation should expect a different payback profile than a 4,000-acre one. USDA’s Census of Agriculture runs on a five-year cycle, with the next full survey due in 2029; in the interim, USDA’s Agricultural Resource Management Survey (ARMS) publishes updated adoption figures annually and is the right place to check for a more current number than the one above.
Sensor Types and What Each One Replaces
Four sensor categories account for most deployed IoT farming hardware in the US, each replacing a specific manual practice or fixed schedule:
- Soil moisture and temperature sensors — replace calendar-based or visual-cue irrigation scheduling with threshold-triggered watering per zone.
- Canopy reflectance sensors — replace routine crop scouting with continuous stress detection, often ahead of visible symptoms.
- Environmental sensors (weather stations, humidity/wind probes) — replace regional weather-service forecasts with on-site microclimate readings specific to a field’s terrain.
- Salinity and pH sensors — used mainly in land restoration and reclamation contexts, replacing lab-only soil testing with continuous in-field readings.
No published USDA or NASS figure breaks down adoption by these specific sensor types or by crop and region — the Census of Agriculture and ARMS both report precision-practice adoption in aggregate categories like “yield maps” or “soil maps” rather than by sensor hardware class. An operator wanting sensor-type-specific adoption data for their own state or crop should check their state’s land-grant extension service, which typically runs its own regional AgTech adoption surveys with finer breakdowns than the federal data.
How AI Drones Are Saving Farms & Millions in 2025 🌾 | Game-Changing AgriTech You Must See!
Yield Gains and Resource Savings, by the Numbers
Agricultural technology market reports covering the 2024–2025 period put IoT and precision agriculture’s yield effect at 20% for wheat and 15% for maize — figures drawn from aggregated grower and market data rather than a single controlled trial, so treat them as directional ranges rather than a guarantee for any specific field. These gains come from a mix of sources: fewer missed irrigation windows, earlier pest and disease detection, and nutrient application matched to what a zone actually needs instead of a blanket per-acre rate.
On the software-spend side, the US agriculture CRM and farm-management software market was valued at $3.2 billion in 2025, according to Growth Market Reports — the layer that turns raw sensor and satellite feeds into an actual task list for field crews. That figure conflates several categories: standalone farm-management software, input-supplier CRM tools, and cooperative-facing CRM systems are all counted together, so there’s no clean published breakout of adoption for farmer-facing CRM alone.
None of the sources in this brief give a per-acre dollar figure for net economic value of IoT adoption specific to farm size — that number would need to be built from a grower’s own input-cost and yield records, comparing a season before and after adoption. The calculator below does that arithmetic for a single farm’s own numbers rather than relying on an industry-wide average that may not fit a given acreage or crop mix.
Calculator: Estimate Your IoT Payback Period
Enter your acreage, current per-acre input cost, and expected yield lift to see the payback period for an IoT sensor and platform subscription.
Run your own numbers
Assumptions: yield-lift percentages are the wheat and maize ranges reported in agricultural technology market analyses for 2024–2025, applied uniformly across your acreage — actual results vary by crop, soil, and season. The calculator excludes financing costs, labor changes, and multi-year subscription discounts, and does not account for years with weather losses that no sensor network prevents.
Coordinating the Data: CRM and Farm-Management Platforms
Sensor and satellite data only becomes useful once it reaches a system that turns readings into tasks — irrigate this zone, scout that block, log this application for a compliance file. That coordination layer is where a farm-management or agriculture CRM platform sits, and it's also where the query "HubSpot for agritechs" points: agritech companies increasingly run their customer, dealer, and field-data operations on general-purpose CRM platforms like HubSpot, configured for agricultural workflows, rather than a bespoke system built from scratch.
- ✔ Task orchestration: assign and track field jobs — irrigation, fertilization, harvest — triggered by sensor alerts or satellite-derived index changes.
- 📊 Data-driven advisory: push zone-specific recommendations to field teams based on current sensor readings plus historical patterns for that plot.
- ⚠ Traceability and reporting: log the full chain from input purchase to field application to harvest, needed for crop insurance claims and buyer audits.
This is also where blockchain-based product traceability earns its keep — a CRM or task-dispatch layer captures what was applied and when, but traceability tooling is what makes that record verifiable to a buyer, certifier, or insurer months later.
JEEVN AI: Smart Farming with Satellite & AI Insights
Choosing Between Farming Brands and Platforms
Anyone comparing farming brands for an IoT rollout is really comparing three separate purchase decisions bundled into one: the sensor hardware manufacturer, the data platform that ingests readings, and the advisory or task layer built on top. Treating all three as one brand choice is a common cause of buyer's remorse, because a hardware brand's proprietary app rarely doubles as a capable CRM or compliance-reporting tool. Evaluate each layer against its own criteria — sensor accuracy and durability for hardware, API openness and uptime for the platform, and advisory relevance for the top layer — rather than picking a single vendor and hoping all three functions are equally strong.
72% of US agriculture software deployments run cloud-based rather than on-premises as of 2025, per IMARC Group — a relevant data point when comparing platforms, since a cloud-native brand is generally easier to integrate with satellite feeds and third-party sensors than a legacy on-premises system built before cloud APIs were standard.
Sector Use Cases: Row Crops, Orchards, and Reclamation Land
Row Crops and Orchards
- Row crops: soil moisture and nutrient sensors drive variable-rate irrigation and fertilization decisions at the zone level, matching the yield-lift ranges cited above for wheat and maize.
- Orchards: canopy reflectance sensors and per-tree monitoring catch water and nutrient stress before visible symptoms appear, particularly valuable given the higher per-unit value of tree crops.

California Wine 2025 🍇 Sustainable Viticulture, Organic & Biodynamic, Precision AgTech
Land Reclamation and Restoration
Salinity, pH, and drainage sensors serve a different purpose on mining reclamation and ecological restoration sites: guiding revegetation and erosion-control schedules rather than optimizing a cash crop. Environmental impact and carbon footprint tracking tools apply directly here, giving site managers a continuous record for regulatory reporting rather than a single annual survey.

Regenerative Agriculture 2025 🌱 Carbon Farming, Soil Health & Climate-Smart Solutions | Farmonaut
A Durable Checklist for Evaluating Any IoT Farming Setup
Adoption figures and yield ranges will be revised as new surveys publish, but the criteria for evaluating a specific IoT setup don't expire. Use this checklist regardless of what year you're reading this:
- Data export: Can raw sensor readings leave the vendor's app via API or CSV, or are they trapped in a single dashboard?
- Farm-size fit: Does the sensor density and pricing model match your acreage? A setup priced for a 5,000-acre operation rarely scales down economically to 100 acres, and USDA's 68%-vs-13% adoption gap by farm size reflects exactly this mismatch.
- Sensor-to-platform latency: How long between a sensor reading and an actionable alert reaching a field team — minutes, hours, or a daily batch?
- Compliance trail: Does the platform log applications and readings in a format an insurer, certifier, or buyer can audit without manual reconstruction?
- Renewal cost trajectory: Is the annual subscription flat, or does it scale with acreage, sensor count, or data volume in ways that change the payback math above?
- Source verification: For any adoption or market-size figure a vendor cites, check whether it traces to a named source (USDA, a named market research firm) with a stated year, or is presented without attribution.

2025 Veg Equipment Boom 🌱 Smart Farming, AI Telematics & $2.3B Market Powered by Farmonaut
How Farmonaut Fits This Stack
Farmonaut provides the satellite-derived and IoT-complementary layer of this stack — crop health, soil, and vegetation index monitoring without requiring a farm to install its own sensor network first. It runs across web, Android, and iOS, with an API for developers who want to feed satellite and weather data directly into an existing farm-management or CRM platform.
- Real-time satellite monitoring of crop, vegetation, and soil health, usable alongside or instead of ground sensors.
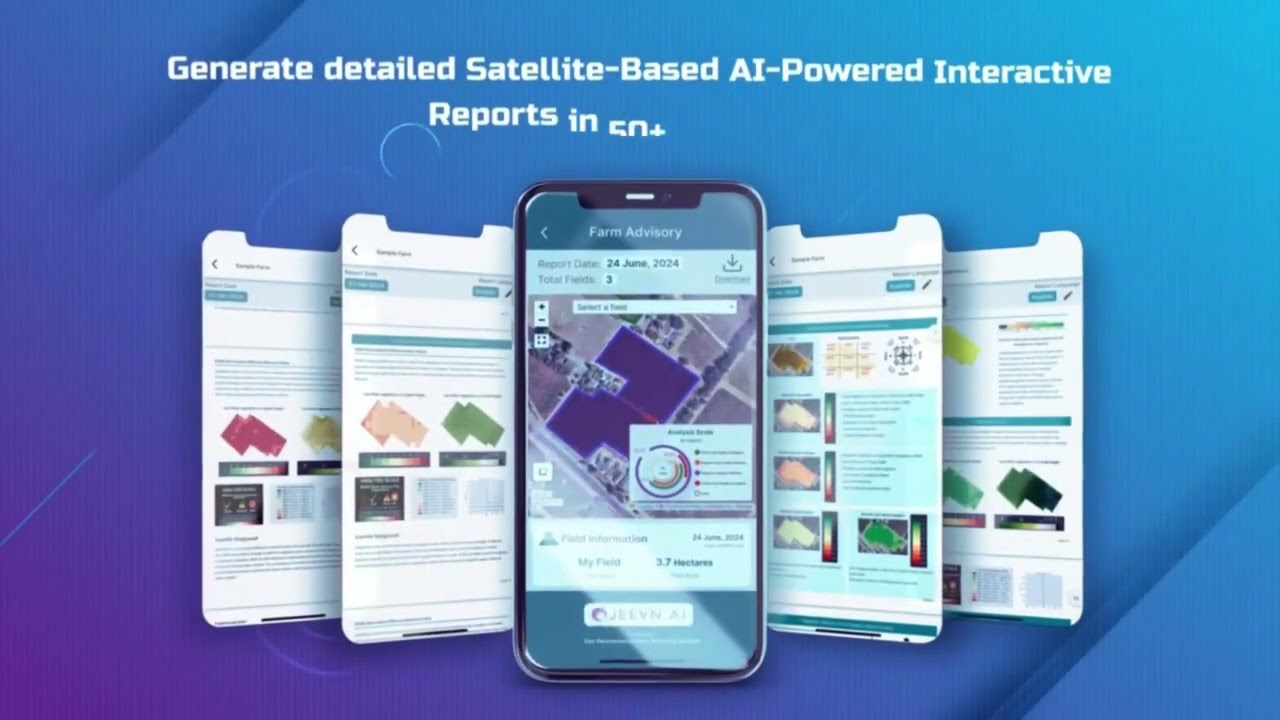
- Jeevn AI Advisory combines satellite, historical, and live data into in-season recommendations for irrigation, fertilization, and pest response timing.
- Fleet and resource management tools for coordinating machinery, transport, and field crews.
- Carbon and environmental footprint tracking for compliance and sustainability reporting.
- Large-scale farm management tools for multi-site oversight from a single dashboard.



Developers can access the Farmonaut API and developer documentation to bring satellite and weather analytics directly into an existing IoT farming or CRM workflow, rather than building a parallel system.

Farmonaut – Revolutionizing Farming with Satellite-Based Crop Health Monitoring
Smart Farming Future : Precision Tech & AI: Boosting Harvests, Enhancing Sustainability
Frequently Asked Questions
What percentage of US farms actually use IoT or precision agriculture?
27% of US farms used at least one precision agriculture practice in 2023, per USDA's Economic Research Service — but adoption splits sharply by size: 68% of large-scale row-crop farms used yield or soil maps, against 13% of small-scale farms. Check USDA's Agricultural Resource Management Survey (ARMS) for a more current annual figure; the next full Census of Agriculture is due in 2029.
How much can IoT farming actually increase yield?
Agricultural technology market reports for 2024–2025 cite a 20% yield increase for wheat and 15% for maize from IoT and precision agriculture adoption. These are market-report ranges, not guaranteed outcomes for any single field — actual results depend on baseline management quality, soil type, and season.
What does "HubSpot for agritechs" mean in practice?
It refers to agritech companies running customer relationship management, field-task dispatch, and compliance reporting on general-purpose CRM platforms like HubSpot, rather than building bespoke software. The US agriculture CRM software market was valued at $3.2 billion in 2025.
Is there a single best IoT farming brand?
No published data ranks farming brands as a single category — hardware, data platform, and advisory layers should be evaluated separately, since a strong sensor manufacturer is not necessarily a strong CRM or compliance-reporting provider.
How do I get started with Farmonaut for IoT and satellite-based farming?
Visit the Farmonaut app for onboarding, or the developer documentation to integrate the API into an existing workflow.



Conclusion
IoT farming in the US is no longer an emerging trend to watch — it's a documented, size-stratified reality: 27% overall adoption, 68% among large row-crop operations, 81% of farms over 5,000 acres running at least one AgTech solution as of 2025. The gap that matters isn't between adopters and non-adopters in the abstract, it's between the 68% and the 13% — a farm-size divide that any operator can locate themselves in before deciding what to spend.
The figures here will move: USDA's ARMS survey updates precision-ag adoption annually, market-sizing firms revise their US IoT and CRM figures on their own release schedules, and the next full Census of Agriculture lands in 2029. What won't move is the checklist above — data export, farm-size fit, alert latency, compliance trail, and renewal-cost trajectory stay the right questions to ask of any sensor network, platform, or brand, regardless of which year's numbers you're checking them against.

 Godrej Agrovet
 Hayleys Agriculture
 Linx Agritech
 Adinet
 Save Your Soils
 GalaxEye Space
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 DnCubed
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroRisk
 Oath Inc
 Esri North East Africa
 MDCV UK
 Etech Consulting Madagascar
 Vestlandsforsking
 WB Dev
 Sama Premium
 Tres Valles
 Blickwinkel
 Agricultural Credit Policy Council
 eKGIS
 Mostas Tech
 Andex
 Deluxe Conseil
 WICO
 Chimera Innovation
 SkyHarvest
 Teledarbas
 Exurbia Geospatial
 FieldZero

