

Reviewed September 2026 against USDA NASS Land Values and Cash Rents data and the NCREIF Farmland Index.
Try it: Enter your numbers above to see results. →
US farm real estate averaged $4,350 per acre in 2025, with cropland at $5,830/acre and pastureland at $1,920/acre, per USDA’s National Agricultural Statistics Service. Farmland has returned an average 9.84% annually from income and appreciation combined since 1992, according to the NCREIF Farmland Index — a track record that is exactly why “portfolio diversification with farmland” is one of the most searched allocation questions among US investors right now.
This article answers it directly: what farmland actually returns, what it costs to buy in, how those returns behave alongside stocks and bonds, and where agricultural real estate fits — or does not fit — inside a broader agricultural portfolio that also includes crops, livestock, and technology. It closes with a calculator that runs your own numbers.
Table of Contents
- Farmland Value & Return Data: What the Numbers Actually Show
- Diversification: The Core Principle Behind Farmland’s Appeal
- Where Farmland Fits in a Portfolio — and Where It Doesn’t
- Climate, Risk Management & Building Resilience
- Economic & Environmental Sustainability
- Investment & Market Access Routes
- Comparative Table: Diversified Agricultural Assets
- Satellite Technology for Agricultural Portfolio Management
- Building an Agricultural Portfolio: A Step-by-Step Method
- Farmland Allocation Calculator
- FAQs
- Conclusion: A Durable Way to Check This Yourself
- Try it: Enter your numbers above to see results.
Farmland Value & Return Data: What the Numbers Actually Show
Start with the figures a search for “portfolio diversification with farmland” is actually trying to find. USDA NASS’s 2025 Land Values and Cash Rents report put the average US farm real estate value (land plus buildings) at $4,350/acre, up 4.3% from 2024’s $4,170/acre. Cropland specifically averaged $5,830/acre in 2025 versus $5,570/acre in 2024, and pastureland averaged $1,920/acre in 2025 versus $1,830/acre in 2024. Cropland cash rent — what a landowner collects annually from a tenant farmer without operating the land — averaged $161/acre in 2025. Since 2020, US cropland values are up 37%, a run documented in NASS’s 2024 summary report.
On the return side, the NCREIF Farmland Index — the benchmark institutional investors and farmland funds use — shows an average annual total return (income plus land appreciation) of 9.84% from 1992 through 2025. That average masks real swings: the index posted a -1.03% total return in 2024, its first negative year in over a decade, driven by falling row-crop commodity prices even as land values held up. That is the honest picture: a long-run average north of 9%, with a downside year on record, not a number that only goes up.
Farm income context matters for reading these land values. USDA’s Economic Research Service tracks US net farm income (inflation-adjusted): $193.1 billion in 2022, falling to $150.3 billion in 2023, and forecast at $140.7 billion for 2024. Land values kept climbing through that same income decline — a sign that farmland pricing is driven as much by long-term appreciation and scarcity as by current-year farm profitability. Anyone underwriting a farmland purchase or fund allocation should separate those two drivers rather than assume rising rents justify rising prices one-for-one.
None of these figures are static. NASS republishes Land Values and Cash Rents each August; the 2026 edition is expected around the same time, via NASS’s Reports & Publications section under Agricultural Prices at USDA NASS. ERS updates its net farm income forecast quarterly at its Charts of Note data product page. NCREIF’s Farmland Index reports calendar-year returns in Q1 of the following year. Whatever you read here, check the current release before acting on it.
Diversification: The Core Principle Behind Farmland’s Appeal
Farmland earns a place in a diversified portfolio for a specific reason: its return stream does not move in lockstep with equities or bonds. That is qualitatively well established — NCREIF and farmland investment platforms describe farmland’s correlation to the S&P 500 and to Treasury bonds as low — but a precise, current correlation coefficient against those specific indices is not published in the sources behind this article. If you need an exact number for a portfolio model, pull the NCREIF Farmland Index total-return series and your benchmark’s total-return series from the same date range and compute the correlation directly; NCREIF’s own site (ncreif.org) is the place to source the raw index data.
At the farm level, diversification means something more concrete: not relying on one crop, one buyer, or one weather pattern. A grower can spread risk across:
- ✔ Crop mix — staple grains alongside higher-value horticultural crops, so a bad wheat year doesn’t sink the whole operation.
- 🌾 Livestock integration — cattle, poultry, or aquaculture as a separate income stream with a different risk profile than row crops.
- 📈 Land type — cropland, pastureland, and timber or agroforestry acreage, each with distinct value drivers per the NASS data above.
- 🛡️ Financial instruments — crop insurance and satellite-verified loan underwriting to smooth a bad season.
- 🌱 Technology — sensors, drones, and monitoring platforms that cut input waste regardless of which crop is planted.
Land value appreciation and farm operating income are two different return sources. USDA NASS tracks the first (cropland up 37% since 2020); USDA ERS tracks the second (net farm income down from $193.1B in 2022 to a $140.7B 2024 forecast). A portfolio built only on rising land prices ignores that operating income has been falling.
This variety reduces exposure to any single point of failure. If drought cuts maize yields, better performance from drought-tolerant crops, livestock, or land-lease income can offset it. The blockchain-based traceability layer adds a market dimension to this: buyers increasingly pay a premium for verified origin and supply-chain integrity, which is itself a diversification of revenue away from commodity pricing alone.
Where Farmland Fits in a Portfolio — and Where It Doesn’t
“Agricultural portfolio” searches span two different audiences: farm operators diversifying what they grow, and outside investors diversifying what they own. Farmland real estate specifically speaks to the second group. Three honest facts investors should know going in:
- Entry cost is real. At $5,830/acre for average US cropland in 2025, a 100-acre parcel runs roughly $583,000 before financing, closing costs, or equipment. This is not a low-minimum asset class for direct ownership.
- Direct ownership is illiquid. Unlike a stock or bond, a farm parcel cannot be sold in a day. Farmland REITs (publicly traded companies that own leased farmland) offer daily liquidity instead, but a numeric comparison of their returns against direct farmland ownership is not available from the USDA or NCREIF sources behind this article — that comparison would need to come from each REIT’s own SEC filings and total-return history.
- Returns are lumpy, not smooth. The 9.84% long-run NCREIF average sits alongside a -1.03% year in 2024. Treat the average as a multi-decade figure, not a promise for any single year.
For farm operators — as opposed to outside investors — the relevant question is less “should I own land as an asset class” and more “how do I structure what I already farm.” That’s where crop mix, livestock, and technology investment (covered next) do the diversification work, and where tools like large-scale farm management platforms earn their keep by giving a multi-parcel operation one place to track performance across crops and land types.
Climate, Risk Management & Building Resilience
Farmland values and farm income both sit exposed to weather, and the ERS net farm income slide from $193.1 billion in 2022 to a forecast $140.7 billion in 2024 reflects commodity price and cost pressure that climate volatility compounds. A diversified operation manages this through:
- Drought-tolerant crop and livestock breed selection, matched to regional conditions.
- Water management and soil conservation systems integrated across the land base.
- Crop insurance backed by satellite-based monitoring for early risk detection (satellite-verified crop insurance and loan support).
- Precision input application via sensors, drones, and AI-driven advisories to cut waste and protect margins in a low-income year.

Why This Matters for the Land-Value Side Too
Land value and farm profitability can diverge, as the 2022–2024 ERS data shows, but they cannot diverge indefinitely — sustained income pressure eventually shows up in cash rents and, over a longer horizon, in land prices. Satellite monitoring and analytics (see carbon footprinting tools) give both operators and investors an earlier read on which parcels are under stress before it shows up in a NASS report a year later.
Treating the 9.84% long-run NCREIF average as an annual guarantee. The index recorded -1.03% in 2024 — plan cash flow around a range, not a point estimate, and check the current-year NCREIF release before committing capital (see the update path in the section above).
Economic & Environmental Sustainability in Agricultural Portfolios
A durable agricultural portfolio balances economic return with environmental stewardship, because the two increasingly fund each other:
- 🌲 Biodiversity and habitat quality improve when crop, livestock, and tree systems are combined rather than run as monocultures.
- ♻️ Lower chemical input costs come from mixed systems that naturally suppress pest and disease pressure.
- 🟠 Nutrient recycling through livestock and crop-residue integration cuts waste and emissions.
- 🪴 Soil health regeneration from rotational and cover-cropping practices protects the long-term productivity that underlies land value itself.
- 💰 Additional revenue from timber, specialty crops, and sustainability-linked premiums.

Carbon footprinting and tracking tools support access to premium supply chains that pay for verified sustainable practice — a revenue line that doesn’t show up in the USDA land-value or income series above but increasingly factors into what a well-managed parcel can command in lease or sale.
Investment & Market Access Routes
Investors and operators looking to build exposure to agricultural real estate and production have several access routes, each with a different capital requirement and liquidity profile:
- ⚡ Direct land ownership — full control and full illiquidity, at the per-acre prices detailed above ($5,830/acre average US cropland, 2025).
- 💸 Leasing land to a tenant operator — the $161/acre 2025 average cropland cash rent is the return without the operating risk, though it forgoes upside from land appreciation captured by an owner-operator.
- 🔍 Farmland investment funds and REITs — lower minimums and daily or periodic liquidity, at the cost of fees and a return stream that will not exactly track direct ownership (comparative performance data was not available in USDA or NCREIF sources for this article; check individual fund prospectuses and REIT filings directly).
- 🚜 Operating diversification — for existing farm operators, adding crop types, livestock, or agritech rather than new acreage.

Operations managing multiple parcels or lease arrangements lean on fleet and resource management tools to keep logistics, input delivery, and crop tracking coordinated across a diversified land base.
American Farm Bureau’s market commentary on farmland values (see American Farm Bureau) tracks regional variation in these trends and is a useful complement to the national NASS averages cited throughout this article.
Comparative Table: Diversified Agricultural Assets
| Asset / Land Type | 2025 US Value or Return | Liquidity | Primary Risk | Portfolio Role |
|---|---|---|---|---|
| US Cropland (avg.) | $5,830/acre (NASS) | Low | Commodity price, input cost | Core real asset |
| US Pastureland (avg.) | $1,920/acre (NASS) | Low | Livestock market, drought | Lower-cost entry |
| Cropland Cash Rent | $161/acre/year (NASS) | Low (multi-year lease) | Rent renegotiation risk | Passive income stream |
| NCREIF Farmland Index | 9.84% avg. annual total return, 1992–2025 | Low (direct); higher via funds | Single-year downside (-1.03% in 2024) | Long-horizon diversifier |
| US Net Farm Income | $140.7B forecast, 2024 (ERS) | N/A (operating metric) | Falling since 2022 peak | Operating profitability signal |
| Farmland REITs / Funds | Not published in USDA/NCREIF sources | High (public REITs) | Market pricing, management fees | Liquid proxy exposure |
| Agritech / Monitoring Tools | Cost-saving, not a market-priced asset | N/A | Adoption, integration cost | Efficiency layer across all of the above |
Satellite Technology for Agricultural Portfolio Management
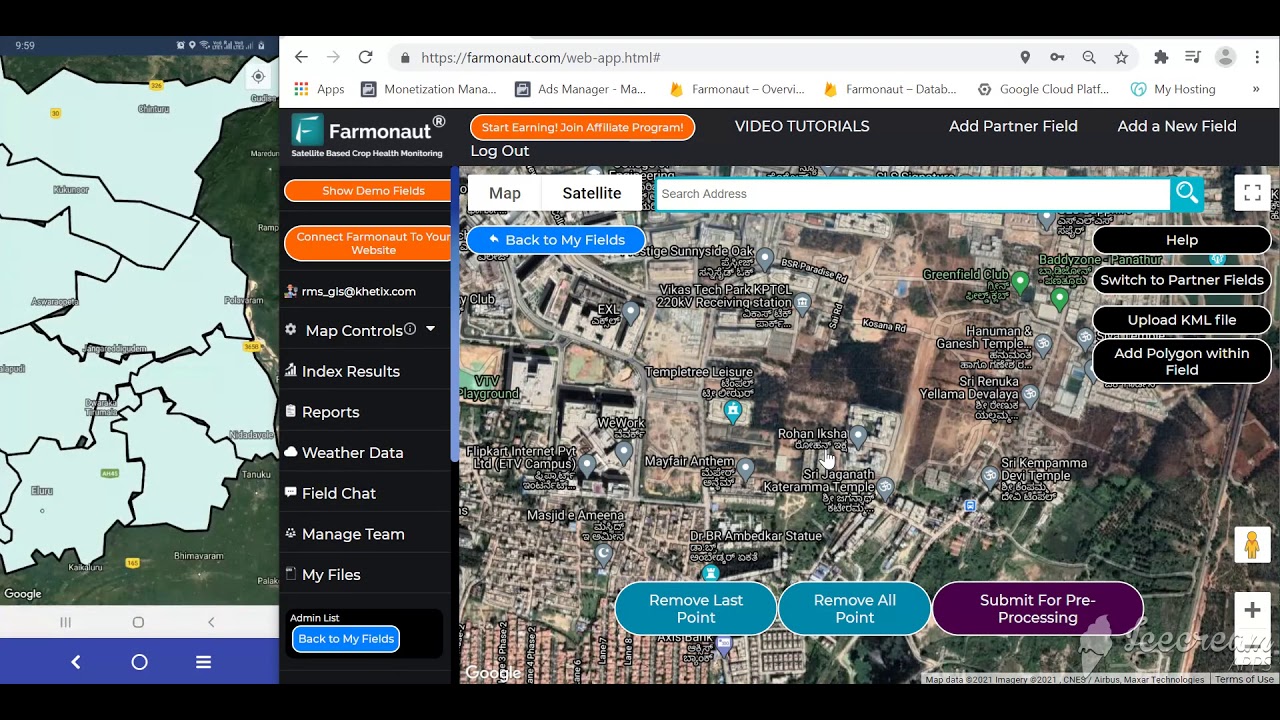
Whichever side of this you’re on — landowner, tenant operator, or fund investor — the same underlying data helps: verified crop condition, water use, and yield trend across every parcel in a portfolio. Farmonaut’s tools address that layer directly:
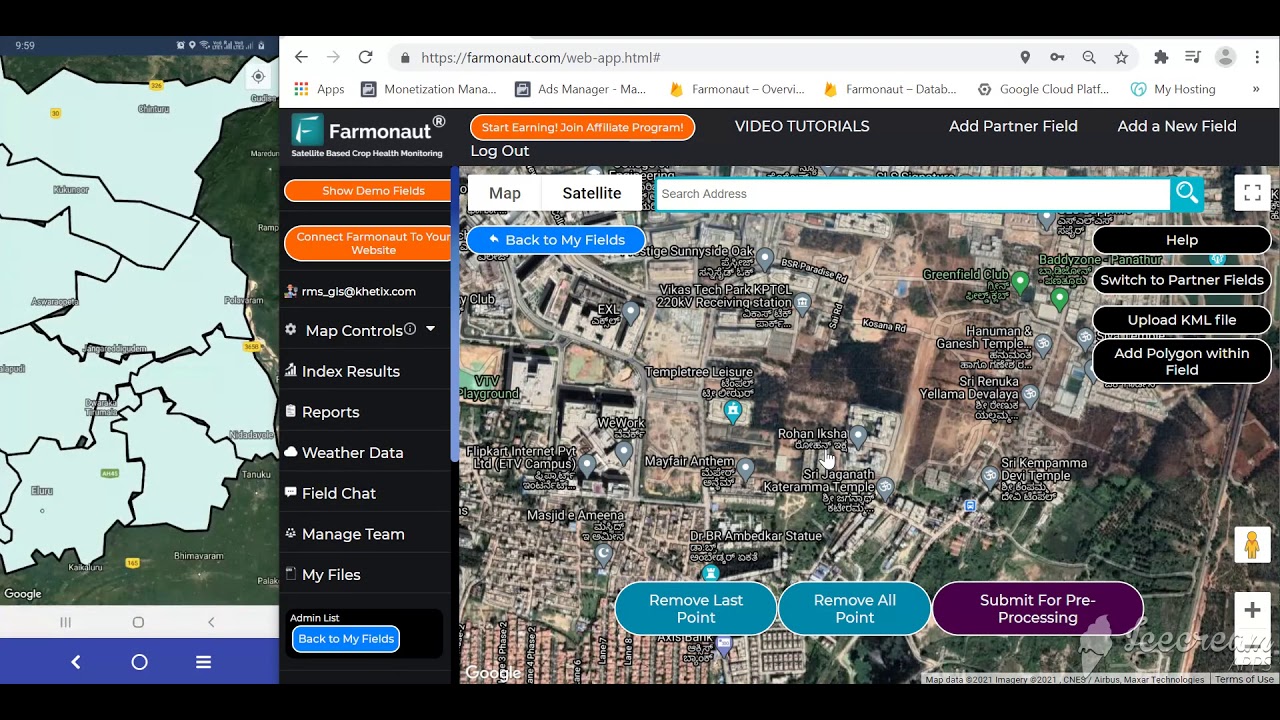
- 🔭 Real-time satellite monitoring for crop vitality (NDVI), soil health, and vegetation trends across diversified land holdings.
- 🧠 AI-based advisory (Jeevn AI), delivering location-specific guidance on yield and input management.
- 🛡️ Blockchain-powered traceability for supply-chain integrity and market trust.
- 🚚 Fleet and resource management for operational efficiency across multiple parcels.
- 🌱 Environmental impact monitoring, including carbon and emissions tracking for compliance and premium-market access.
Explore Farmonaut’s tools directly:
- 🌍 Carbon Footprinting for emissions monitoring and compliance.
- 🔗 Blockchain Traceability for verified agricultural supply chains.
- 📊 Fleet Monitoring for optimized logistics across a multi-parcel portfolio.
- 🌲 Crop Plantation & Forest Advisory for climate-smart decision support.
- 🛰️ Developer API Access and API Docs for integrating satellite intelligence into existing farm management systems.




Building an Agricultural Portfolio: A Step-by-Step Method
This method holds regardless of what next year’s NASS or NCREIF numbers say — rerun it against the current release each year:
- Pull the current-year figures first. Get the latest NASS Land Values and Cash Rents report and the latest NCREIF Farmland Index return before making any allocation decision — the numbers in this article will be a year or more old by the time you read it.
- Separate land value from operating income. Check both the per-acre value trend and the ERS net farm income trend for your target region; they can diverge, as 2022–2024 shows.
- Decide your access route. Direct ownership, a lease, or a fund/REIT — each trades control for liquidity differently (see the Investment & Market Access Routes section above).
- Size the position against illiquidity. Direct farmland cannot be sold quickly; size any allocation so a bad year doesn’t force a fire sale.
- Diversify what’s grown, not just where it’s owned. Add at least one high-value horticultural crop, one climate-resilient grain, and consider livestock or agroforestry to reduce single-crop exposure.
- Layer in satellite monitoring and AI advisory (like Jeevn AI) to catch yield and soil stress early, across every parcel.
- Verify with insurance and traceability. Use satellite-based verification for loans or insurance, and blockchain traceability for premium and export markets.
- Rebalance every season, tracking performance via a farm management app rather than waiting for the next annual report.
Digitize multi-parcel operations with Farmonaut’s management suite for tracking, analysis, and scalable operation from phone or browser.
Farmland Allocation Calculator
Enter your budget and target mix to see indicative acreage, annual lease income, and a NCREIF-based return range for a farmland allocation, using the 2025 USDA NASS and NCREIF figures cited above as defaults you can override.
Enter your numbers above to see results.
Assumptions: uses 2025 USDA NASS per-acre values and NCREIF Farmland Index return figures as defaults, all editable. Excludes financing costs, property taxes, closing costs, management fees, and any appreciation beyond the entered return rate. Cash rent and returns are not guaranteed and vary by region and year — replace the defaults with current-year figures from NASS and NCREIF before relying on this for a real decision.
FAQs
- What does portfolio diversification with farmland actually mean?
- It means holding farmland — directly, through a lease arrangement, or via a fund — alongside other asset classes because its return pattern, driven by land appreciation and lease income rather than corporate earnings, does not move identically to stocks and bonds. US cropland averaged $5,830/acre in 2025 (USDA NASS) and the NCREIF Farmland Index averaged 9.84% annual total return from 1992–2025.
- Is portfolio diversification with agricultural real estate the same thing as farmland investing?
- Largely yes — “agricultural real estate” refers to the land and buildings (the $4,350/acre US average in 2025 per NASS), while “farmland investing” typically describes the act of acquiring exposure to that real estate, directly or through a fund. Whether this fits your portfolio depends on your liquidity needs: direct ownership is illiquid, so weigh it against your investment horizon before allocating.
- What returns has farmland actually delivered?
- The NCREIF Farmland Index averaged 9.84% annually from 1992 through 2025, combining land appreciation and lease/operating income. That average includes a -1.03% total return in 2024 — the first negative year on record in over a decade — so treat 9.84% as a long-run figure, not an annual guarantee.
- How much does it cost to build an agricultural portfolio that includes land?
- At the 2025 US average of $5,830/acre for cropland, a 100-acre position costs roughly $583,000 before financing and closing costs; pastureland at $1,920/acre is a lower-cost entry point. Cropland cash rent averaged $161/acre in 2025 for those leasing rather than buying.
- Why is US net farm income falling while land values keep rising?
- USDA ERS recorded inflation-adjusted net farm income of $193.1 billion in 2022, falling to $150.3 billion in 2023 and a forecast $140.7 billion in 2024, while NASS cropland values rose over the same period. Land pricing reflects long-term scarcity and appreciation expectations more than a single year’s farm profitability — the two series should be checked separately, not assumed to move together.
- How can satellite and AI technology improve returns on an agricultural portfolio?
- Real-time monitoring of crop health, soil condition, and water use lets farmers and landowners catch yield-limiting stress early and apply inputs more precisely, protecting margins in years when commodity prices or weather are working against them.
- How often should an agricultural portfolio be reviewed?
- Every season for crop and operational decisions; annually for land-value and return benchmarking, since USDA NASS and NCREIF both publish on an annual cycle (NASS each August, NCREIF in Q1 for the prior calendar year).


Conclusion: A Durable Way to Check This Yourself
The figures in this article — $5,830/acre cropland, $1,920/acre pastureland, 9.84% long-run farmland returns, a -1.03% 2024 downturn, and net farm income falling from $193.1 billion to a $140.7 billion forecast — are all a snapshot from USDA NASS, USDA ERS, and NCREIF as of the reports cited above. They will be superseded. What doesn’t expire is the method: pull the current NASS Land Values and Cash Rents report each August, check ERS’s quarterly net farm income forecast, and get the latest NCREIF Farmland Index annual return before sizing any position. Compare land-value trend against operating-income trend for your target region, decide your access route based on how much illiquidity you can tolerate, and diversify the underlying farm operation — crop mix, livestock, technology — regardless of whether you ever hold land directly.
Whether you’re an operator diversifying what you grow or an investor weighing farmland as a real-asset allocation, that combination of updated data and a repeatable checklist is what makes an agricultural portfolio resilient — not a fixed set of numbers that ages the moment they’re published.

 BayWa
 Azure Clouds
 MCSOD
 Marei Nursery
 eKGIS
 Mostas Tech
 Native Seeds
 Andex
 FCF India
 Unifrutti Gulf
 Deluxe Conseil
 TVS Electronics
 WICO
 Chimera Innovation
 SkyHarvest

