

Cattle Management Software: Market Size & Buyer’s Guide
Reviewed August 2026 against USDA Economic Research Service, Eurostat, and Mordor Intelligence data.
Try it: Mixed-Operation Software Fit Calculator →
The global farm management software market was worth $2.91 billion in 2025 and is tracked toward $3.25 billion in 2026 by Mordor Intelligence; the cattle-specific slice of that market is smaller but compounding faster, at $1.93 billion in 2025 heading toward $3.09 billion by 2030. Europe holds a documented 26.1% of 2025 global revenue, China’s own software spend is still a small fraction of its farmland, and the UK’s evidence-retention rules are now pushing digital record-keeping whether farms want it or not. Below, each of those figures is broken out by region and by use case — cattle herds, mixed crop-livestock operations, and row crops — with a calculator at the end so you can check where your own operation sits against USDA’s actual adoption data.
Farm Management Software Market Size, by Research Firm and by Region
Ask five market-research firms how big the “farm management software market” is and you will get five different numbers, because each defines the category’s edges differently — some count only crop/field software, others fold in livestock, fleet, and data-analytics tools. Rather than pick one and hide the disagreement, here is the actual spread, so you can judge which scope matches what you are buying:
| Research Firm | Base Year Value | Forecast Year Value | CAGR |
|---|---|---|---|
| Mordor Intelligence | $2.91B (2025) | $5.64B (2031) | 11.66% |
| Fortune Business Insights | $3.20B (2025) | $13.48B (2034) | 17.40% |
| IMARC Group | $3.4B (2025) | $7.2B (2034) | 8.60% |
| MarketsandMarkets | $3.4B (2024) | $5.8B (2029) | 11.0% |
| Market Growth Reports | $1.58B (2026) | $4.18B (2035) | 11.4% |
| Research Corridor | $3.0B (2023, source’s own approximate figure) | Not separately published | Not separately published |
The narrowest estimate (Market Growth Reports, scoped mainly to cloud- and web-based platforms) puts the 2026 figure at $1.58 billion; the widest (Fortune Business Insights, which folds in a broader definition of farm software) puts 2025 at $3.20 billion and projects $13.48 billion by 2034 on a 17.40% CAGR. If a vendor or press release quotes you a market-size number, ask which of these scopes it matches — “farm management software” without a stated boundary is not a comparable figure.
By region, Fortune Business Insights put North America at $1.04 billion of 2025 revenue (32.4% of the global total), Europe at $0.84 billion (26.1%), and Asia-Pacific at $0.67 billion (20.9%) — leaving roughly 20.6% split across South America, the Middle East, and Africa. marketgrowthreports.com‘s separate data-analytics-focused report puts North America closer to 45% and Europe at 28%, and cites over 700,000 farms worldwide already applying farm software to map soil variability and monitor inputs, with Asia-Pacific accounting for 20% of global installations — broadly consistent with Fortune Business Insights on Asia-Pacific’s share even though the North America and Europe splits differ by scope.

Cattle Management Software: What It Does and What the Market Is Worth
What Is Cattle Management Software?
Cattle management software tracks the things a herd manager has to know without walking every pasture every day: individual animal IDs, breeding and calving dates, weight gain, feed rations, vaccination and treatment records, and movement between paddocks or feedlots. Mordor Intelligence’s cattle-specific market report segments the category by sector (dairy versus meat/beef), by software type (on-premise versus cloud-based), and by end user (farm owners, dairy managers, and others) — which is a useful checklist when you are comparing products, since “cattle management software” can mean anything from a herd spreadsheet replacement to a full health-monitoring platform with ear-tag sensors.
Cattle Management Software Market Size
Mordor Intelligence sizes the global cattle management software market at $1.74 billion in 2024, rising to $1.93 billion in 2025 and a projected $3.09 billion by 2030 — a 9.81% CAGR, faster than the broader farm management category on the same firm’s numbers (11.66% CAGR, but on a base roughly 50% larger). North America is the largest regional market for cattle software; Asia-Pacific is the fastest-growing.
On the ground, the clearest US data point on cattle-adjacent technology adoption comes from dairy, not beef: the USDA Economic Research Service found that robotic milking systems produced 6% of US milk in 2021, up from 4% in 2016, and that adoption was highest — 13% — among midsized dairies running 150–499 head. Smaller operations under roughly 50 cows tend to rely on family labor that makes a robotic system’s cost hard to justify, while the largest operations already run low per-cow labor costs and see less incentive to retool. That U-shaped pattern (adoption peaking in the middle, not at the top) is the opposite of what most software marketing assumes, and it is worth checking the current ERS chart before assuming “bigger farm equals more software.”
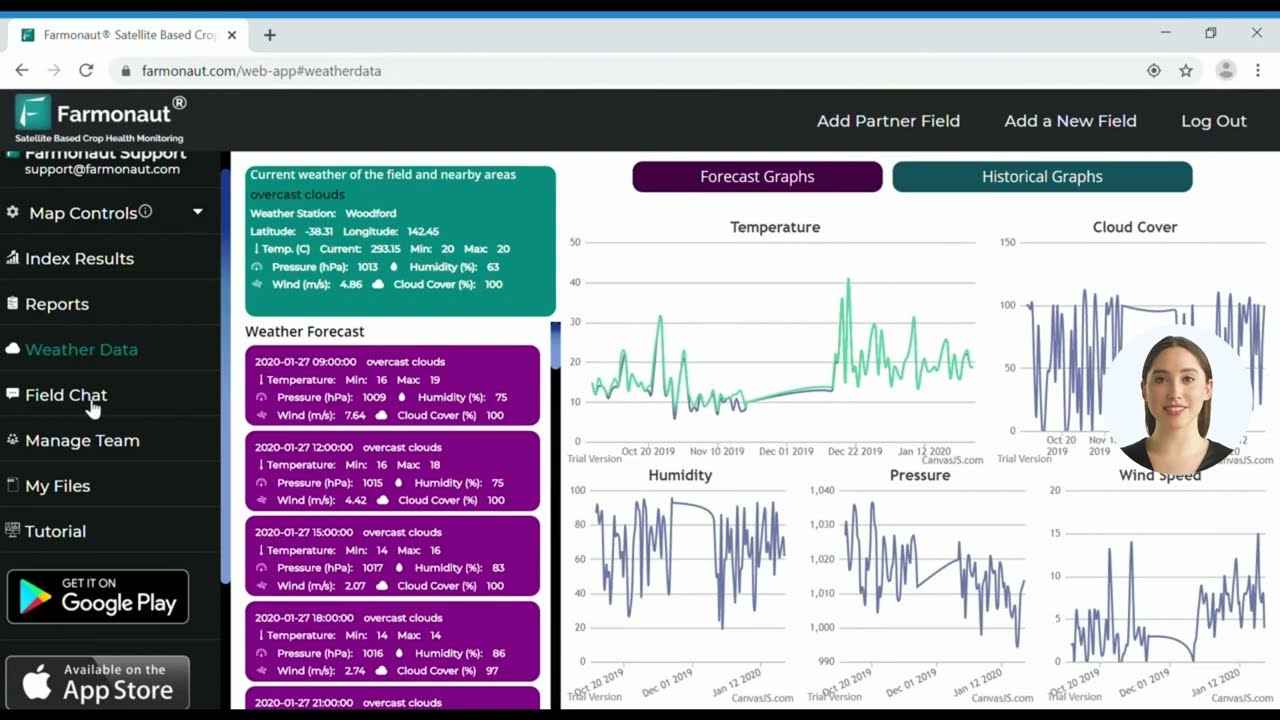
For logistics around the herd itself — feed delivery, waste hauling, and animal transport — Farmonaut’s fleet and resource management tools track vehicle use and routing without requiring a separate dedicated livestock-logistics platform.
Why Adoption Is Accelerating: Cloud, AI, and Government Rules
Three forces show up in every report on this market, and each has a specific, sourced number behind it rather than a vague trend line:
- Cloud deployment now dominates new installs. marketgrowthreports.com puts cloud-based platforms at 65% of 2024 deployments against 35% for local or web-based systems, and precision farming as the largest single application at over 45% of total software usage. Cloud’s advantage is scale and remote access — one login covering every field or paddock — not just cost; on-premise systems persist mainly where gminsights.com-tracked connectivity gaps or legacy hardware make cloud impractical.
- AI and IoT are the technology layer, not the product. marketsandmarkets.com sizes the AI/IoT-enabled slice of the market at $3.4 billion in 2024 growing to $5.8 billion by 2029 (11.0% CAGR), driven by predictive analytics for disease and weather risk plus blockchain-based traceability — the same functions Farmonaut delivers through satellite imagery and its API developer docs rather than on-ground sensor networks.
- Government programs are a genuine tailwind, not marketing filler. imarcgroup.com credits subsidies, grants, and tax incentives in Europe and North America specifically for accelerating adoption — and the UK section below shows exactly how a compliance deadline turns into a software purchase.
On the crop side, US Department of Agriculture survey data confirms the same technology gap by farm size that shows up in dairy. Using four rounds of the Agricultural Resource Management Survey, USDA ERS found auto-steer guidance adoption among the largest farms reached 73% for corn (2016 survey), 82% for winter wheat (2017), 68% for soybeans (2018), and 67% for cotton (2019) — against just 10%, 7%, 11%, and 50% respectively among the smallest farms in each crop’s survey year. Cotton is the outlier because even small cotton operations tend to run at a scale where guidance systems pay for themselves faster.



Europe Farm Management Software Market
Two numbers frame Europe’s market: Fortune Business Insights values it at $0.84 billion in 2025 (26.1% of global revenue), while marketgrowthreports.com‘s broader data-analytics scope puts Europe closer to 28% — the two are consistent with each other within normal scope variation. Underneath that headline, Eurostat’s 2023 farm structure survey shows adoption is still uneven across the bloc: 43% of EU farms reported having internet access, but only 11% had deployed a Farm Management Information System — with France alone reaching 60% adoption, far ahead of the EU average. Precision farming methods (automated spraying, GPS-guided input application) reached 18% of EU farms, covering 44% of total EU agricultural land, with Luxembourg, Finland, and Estonia above 75% adoption while Cyprus, Greece, and Romania sat between 1% and 15%. Autonomous machinery remained rare at 7% of farms.
That France/EU-average gap is the useful takeaway: European adoption is not one market moving together, it is a handful of leaders pulling the bloc’s average up while most member states lag. Two structural drivers explain why the leaders keep investing — Common Agricultural Policy compliance reporting and Green Deal sustainability targets both require documentation that a spreadsheet handles poorly. Farmonaut’s carbon footprinting platform tracks and reports emissions data in the format those compliance schemes increasingly expect.
China Farm Management Software Market
China’s farm management software figures vary more by report scope than almost any other country in this piece. Fortune Business Insights projects China’s national market at $0.22 billion for 2026, inside an Asia-Pacific total of $0.67 billion (20.9% of global revenue) for 2025. marketgrowthreports.com‘s data-analytics-scoped report instead frames Asia-Pacific as 20% of global installations and cites China as one of the region’s largest contributors to overall active-user counts, without publishing a standalone dollar figure for China. The two are not contradictory — one measures software revenue, the other measures installed base — but neither should be quoted as “the” China market size without naming which measure it is.
What is consistent across reports: Asia-Pacific is the fastest-growing region in the global market on Mordor Intelligence’s figures (11.4% CAGR through 2031, ahead of every other region), and China’s mechanized farm base is large enough that even a small percentage-point increase in software penetration represents a meaningful absolute number of new users. If you need a current China-specific dollar figure for planning, pull the latest Fortune Business Insights or Mordor Intelligence regional breakdown directly rather than relying on a percentage share applied to an outdated global total.
UK Farm Management Software Market
Fortune Business Insights projects the UK’s national farm management software market at $0.27 billion for 2026 — the largest single national market inside Europe on that firm’s figures, ahead of Germany’s projected $0.23 billion. The reason UK adoption keeps climbing has less to do with software marketing than with paperwork: under the Sustainable Farming Incentive 2026 (SFI26) scheme rules published on GOV.UK, participants must keep evidence — field-operation logs, invoices, and action-specific documentation — for at least seven years from an agreement’s end or termination date, and the Rural Payments Agency can request that evidence during compliance checks at any point in that window. The scheme rules explicitly allow remote monitoring, including satellite imagery, as part of a “combination of approaches” to verification.
Seven years of retrievable, dated, geo-tagged records is a hard thing to guarantee from paper notebooks and is exactly what cloud farm management software is built to do by default. That is the durable driver behind the UK number: it does not depend on this specific scheme surviving unchanged — whatever the next iteration of environmental land management funding requires, digital record-keeping will keep being the practical way to meet it. Check the current SFI26 scheme rules on GOV.UK for the specific evidence requirements attached to whichever actions you have selected, since those are set per action rather than scheme-wide.
Mixed Farm Management Software: What to Look For
Mixed farming combines crop production and livestock raising on the same operation — a wheat-and-cattle farm, or a vegetable grower running a small beef herd on rotational pasture. The software problem this creates is not that the technology doesn’t exist; it’s that most farm management platforms are built around one module or the other, forcing mixed operations to run two logins, two data formats, and two support contracts to cover one farm.
When you are evaluating “mixed farm management software” specifically, the checklist is narrower than a general farm-software comparison:
- One login covering both field and herd data — not two products bridged by a spreadsheet export.
- Shared compliance and traceability reporting — a single audit trail that covers crop inputs and animal movements together, which matters directly for UK SFI26-style evidence retention and EU CAP reporting.
- Independent update cadence per module — crop data changes with the growing season, herd data changes daily; a platform that forces both onto the same refresh cycle wastes effort.
- No hardware lock-in on either side — satellite-based crop monitoring avoids per-field sensor costs, and herd tracking should not require replacing every ear tag to switch providers.
Farmonaut’s product traceability solutions record each stage of the agricultural process across crop and livestock outputs alike, which is the “shared compliance” piece above in practice rather than in theory.
Mixed-Operation Software Fit Calculator
Assumes one software module per operation type (cropland, herd, and combined compliance reporting when both are present) and applies the USDA and Eurostat adoption bands cited in this article. It does not price any specific software product or estimate labor savings.
Farmonaut’s Platform for Cattle and Mixed Operations
Farmonaut runs the field side of a mixed or cattle operation on satellite imagery rather than on-ground sensors, which is what makes it usable on pasture and rangeland where wiring up IoT sensors is impractical:
- Satellite crop and pasture monitoring: Multispectral imagery delivers vegetation-health (NDVI) and soil-condition data for the cropland half of a mixed operation without in-field hardware, complementing GPS-guided tractor workflows already in use on the equipment side.
- Fleet and resource management: The fleet management tools mentioned above cover feed delivery and animal transport logistics alongside crop-input hauling.
- Traceability: Product traceability records apply across both crop and livestock outputs for one audit trail.
- Financing verification: Crop loan and insurance verification uses satellite-confirmed field data to support financing applications, which matters as much to a mixed operation’s crop side as to a pure row-crop farm.
- Large-scale and government use: The agro admin app scales from a single mixed farm to cooperative or government-level oversight of many operations at once.
- API access: Developers can pull the same satellite and weather data directly via sat.farmonaut.com/api, documented at the API developer docs.
Challenges and What Comes Next
The gaps in this market are the same ones the Eurostat and USDA numbers above already show: connectivity (43% EU internet access still means 57% without it), farm-size disparity in adoption (7–13% among the smallest US operations versus 67–82% among the largest for auto-steer alone), and regulatory divergence between the UK’s SFI26 evidence rules, the EU’s CAP and Green Deal reporting, and whatever US state or federal programs apply to a given operation. None of these are software problems Farmonaut or any vendor can solve unilaterally — they are adoption-curve realities to plan around.
researchcorridor.com expects continued integration of IoT, AI, and machine learning to keep narrowing those gaps by making software cheaper to run per farm, and Farmonaut’s own approach to that trend is documented at high-tech agriculture equipment — the throughline being that satellite-first platforms lower the entry cost that has kept smallholders and midsized operations below the adoption curve every survey in this article measured.
Frequently Asked Questions
- What is the cattle management software market size?
- Mordor Intelligence values it at $1.74 billion in 2024, $1.93 billion in 2025, and projects $3.09 billion by 2030 — a 9.81% CAGR. That is faster growth than the broader farm management software category, though from a smaller base.
- What is cattle management software, specifically?
- Software for tracking individual animal IDs, breeding and calving records, weight and feed data, health and vaccination history, and herd movement. It is segmented by dairy versus meat sector, and by on-premise versus cloud deployment.
- How big is the farm management software market in Europe, China, and the UK?
- Fortune Business Insights puts Europe at $0.84 billion (2025, 26.1% global share), with the UK projected at $0.27 billion and Germany at $0.23 billion for 2026. China is projected at $0.22 billion for 2026 within a $0.67 billion Asia-Pacific total (20.9% share). Country-level figures shift by report scope, so check the source’s definition before comparing across firms.
- What counts as “mixed farm management software”?
- Software that handles crop/field data and livestock/herd data in one platform with shared compliance reporting, rather than two separate products for a farm that runs both crops and cattle. See the checklist above and the calculator for a rough fit assessment of your own operation.
- Do I need on-farm IoT sensors to use satellite-based farm management software?
- No. Farmonaut’s platform runs on multispectral satellite imagery rather than ground sensors, so pasture and rangeland can be monitored without wiring hardware into fields; IoT integrations remain optional add-ons rather than a requirement.
- Can farm management software help with loans, insurance, or carbon compliance?
- Yes. Farmonaut’s crop loan and insurance verification and carbon footprinting tools use satellite-confirmed field data to support financing and emissions-reporting requirements, including the kind of multi-year evidence retention now required under schemes like the UK’s SFI26.
Farmonaut Subscriptions
Subscription plans scale by hectarage, data-refresh needs, and feature set — from crop monitoring alone up through fleet management and yield certification for a full mixed or cattle operation.
Ready to see satellite-based digital farm management running on your own fields or pasture?
Further reading:
Conclusion
Every number in this article carries its own expiration date. Mordor Intelligence, Fortune Business Insights, IMARC, MarketsandMarkets, Market Growth Reports, and Research Corridor will all refresh their farm and cattle management software figures on their own schedules — check the linked report pages directly for whatever is current when you read this rather than trusting a screenshot of today’s numbers. USDA ERS and Eurostat publish on regular survey cycles too, so the adoption percentages above are a snapshot from named survey years, not a permanent ranking.
What does not expire is the method: separate revenue-scope claims from installed-base claims, check whether a “farm management software” figure includes livestock and cattle software or excludes it, and use the region- and herd-size-specific adoption data — not a single global average — to judge whether your own operation is ahead of or behind the curve. The calculator above applies that same method to your own cropland and herd numbers.
Ready to see where satellite monitoring fits into your operation? Get Started Now.

 Global Launch Base
 Elders
 Agritein
 Delicio
 WB Dev
 Sama Premium
 Prochecker
 Tres Valles
 LACOS Geoinformation
 Magrifly
 LatConnect 60
 WebsEdge
 Blickwinkel
 Agricultural Credit Policy Council
 Marei Nursery
 eKGIS
 Mostas Tech
 Andex
 FCF India

