

Mining investment · Evaluation guide
Mining Analysis: 7 Steps to Evaluate a Mine or Stock
Seven checks decide whether a mine or mining share holds up: resource quality, study stage, unit cost, price sensitivity, title, closure and valuation. Each is shown here with real filings.
Key takeaways
- Study accuracy differs widely: about ±50% for an initial assessment, ±25% for pre-feasibility and ±15% for feasibility (SEC S-K 1300).
- Four large gold producers reported 2025 AISC from $1,339 to $1,637 per ounce, though on differing bases (company reports).
- Agnico Eagle’s 2025 AISC differed by $56 per ounce between by-product and co-product accounting (2025 annual report).
- DeLamar’s after-tax NPV falls from $773.7M to $178.3M when gold goes from $3,000 to $2,250 and silver from $35 to $20 (2025 study).
- Satellite screening gives exploration targets ahead of any resource estimate; drilling and assays are still needed.
In this article
- Mine analysis or stock analysis: what changes
- Step 1: Check the deposit and its resource category
- Step 2: Test the study stage and its cost accuracy
- Step 3: Work out the margin per ounce or pound
- Step 4: Stress-test net present value against the metal price
- Mine economics calculator
- Step 5: Check title, jurisdiction and permits
- Step 6: Price closure, tailings and water
- Step 7: Value the company and its funding needs
- Red flags that end an analysis early
- Where satellite data fits in the process
- Frequently asked questions
Mining analysis is the process of testing whether a mineral deposit can make money after every cost and risk is counted, and whether the price of the asset or share already reflects that. Seven checks do most of the work: resource quality, study stage, cost per unit, price sensitivity, title and permits, closure liabilities, and valuation against funding needs.
The same seven steps work for a mine analysis of one property and for a listed company, because a mining share is mostly a claim on the cash its deposits may produce. This guide uses real filings as worked examples, including one published feasibility study and the reported costs of four large gold producers. It is written for investors, licence owners and the consultants who advise them.
Mine analysis or stock analysis: what changes
The geology and the engineering stay the same. What changes is the question you ask at the end. A buyer of a property asks what the ground is worth to them. A shareholder asks what the whole company is worth, after debt, overheads and future share sales.
Infographic
The evaluation in order
- 1DepositCategory, grade and cut-off.
- 2StudyStage, date and accuracy.
- 3MarginPrice minus full unit cost.
- 4SensitivityNPV at lower prices.
- 5Title and closureRights, permits and liabilities.
- 6ValueMarket value, NAV and funding.
| Question | Evaluating a mine or licence | Evaluating a mining stock |
|---|---|---|
| Main evidence | Drill data, assays, title papers, site visit | Technical reports, annual filings, cost reconciliations |
| Key cost figure | Your own capital and operating estimate | Reported all-in sustaining cost per ounce or pound |
| Key value figure | Net present value of the project | Market value compared with net asset value |
| Biggest hidden risk | Defective title, closure liabilities | Share dilution, a study built on old prices |
| Who signs the numbers | Your qualified consultant | The company’s named qualified person |
If you are comparing specialist firms rather than single assets, our guide to mining investment companies covers that side.
Step 1: Check the deposit and its resource category
Start with what is actually in the ground, and how sure anyone is about it. Grade is the amount of metal per tonne of rock, often in grams per tonne (g/t). Tonnage multiplied by grade gives contained metal, but contained metal is not recoverable metal and it is not profit. The type of ore deposit also matters, because it shapes the mining method and the recovery you can expect.
The confidence category tells you how far to trust the tonnage. The SEC mining disclosure rules (S-K 1300) use these levels:
- Inferred resource: based on limited evidence. The rule says uncertainty is too high to apply the economic factors in a way that is useful for judging viability.
- Indicated resource: adequate evidence and sampling, enough to support mine planning.
- Measured resource: conclusive evidence and sampling, enough for detailed mine planning.
- Probable reserve: the economically mineable part of an indicated (and in some cases measured) resource.
- Proven reserve: the economically mineable part of a measured resource.
Canadian-listed issuers report under National Instrument 43-101, the Canadian disclosure standard for mineral projects, which has its own technical report form. When you compare companies, confirm which code each one uses.
What to do: add up the share of ounces or tonnes in each category. A company whose headline number is mostly inferred is at a very different stage from one with proven and probable reserves, even if the totals match. Then look for the cut-off grade, the lowest grade counted as ore, and the metal price used to set it.
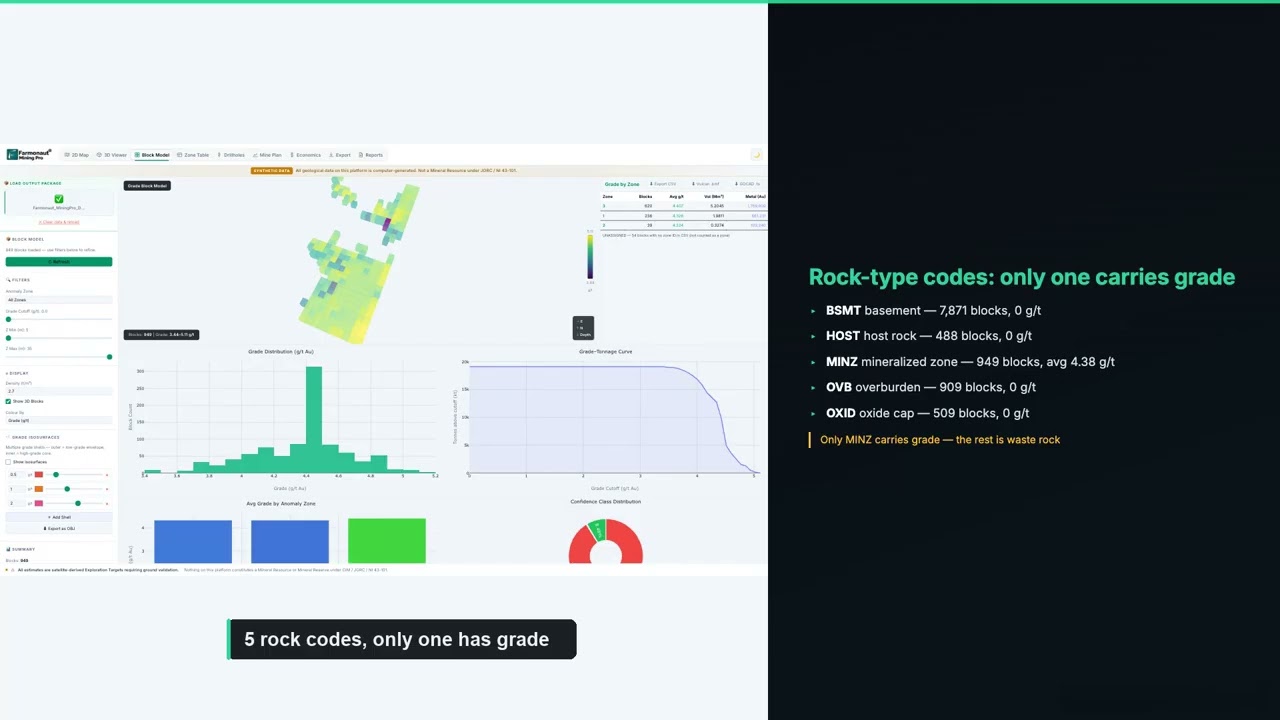
▶ The block model behind a mine plan, in plain English (17:46) · 17:46
Step 2: Test the study stage and its cost accuracy
A number means little until you know which study produced it. S-K 1300 sets out three levels and the cost accuracy each should reach.
| Study level | Capital and operating cost accuracy | Contingency allowed | What it can support |
|---|---|---|---|
| Initial assessment | About ±50%, if costs are included | Up to 25% | Disclosure of resources and early economic potential |
| Pre-feasibility study | About ±25% | Up to 15% | Evidence that extraction is economically viable |
| Feasibility study | About ±15% | Up to 10% | An investment decision or project financing |
Source: the summary table in the same SEC rule. An initial assessment may include inferred material in its cash flow only with warnings: it must say the work is preliminary, disclose the inferred share of the resources used, and show the results without inferred material as well. Find that percentage. It is one of the fastest checks in this whole process.
Also check the date. A study built on an old metal price and old labour and fuel costs can be wrong in both directions. Read the price deck (the prices the study assumes) before reading its results.
Step 3: Work out the margin per ounce or pound
Operational evaluation comes down to one figure: the margin between the selling price and the full cost of keeping production going. For gold, the common measure is all-in sustaining cost (AISC). The World Gold Council guidance on AISC asks companies to reconcile the figure to their financial statements. Barrick’s explanation shows what it contains: cash costs plus sustaining capital, sustaining leases, general and administrative costs, minesite exploration and reclamation accretion. It leaves out tax, interest, dividends and depreciation.
Chart
Average gold price used for US statistics
US$ per troy ounce, annual; 2025 is an estimate
Chart
Reported all-in sustaining cost, four large gold producers
US$ per ounce, full year 2025; bases as stated by each company
AISC is not a standard accounting measure, and the basis changes the answer. Agnico Eagle reported 2025 AISC of $1,339 per ounce on a by-product basis and $1,395 on a co-product basis, a $56 gap for the same ounces. By-product accounting subtracts the value of other metals from gold’s costs. Agnico Eagle’s co-product figure simply does not deduct them. Newmont’s co-product method instead shares costs across the metals by relative sales value.
Costs also move with the price. Barrick said its 2025 AISC of $1,637 ran slightly above guidance partly because higher gold prices raised royalties, and it guided to $1,760 to $1,950 for 2026 on a $4,500 gold price assumption. Kinross reported $1,539 per ounce on a by-product basis for 2025, against $1,365 for 2024. A royalty is a payment to a third party, often a net smelter return (NSR) royalty, a percentage of metal revenue after smelting and transport charges. Our guide to buying mining royalties covers them from the holder’s side.
For scale, the USGS Mineral Commodity Summaries 2026 puts the average gold price at about $3,300 per ounce for 2025 (estimate), and Kitco reported spot gold above $4,100 on 5 November 2026. Compare today’s margin with a margin at the lower price too, since a price you cannot rely on is a poor base for a decision. Our overview of mining profitability compares margins and AISC by metal.
Step 4: Stress-test net present value against the metal price
Net present value (NPV) is all the project’s future cash flows, discounted to today, minus what it costs to build. Internal rate of return (IRR) is the discount rate at which NPV reaches zero. Payback is how long the cash takes to repay the build. The headline NPV is a single scenario, so go straight to the sensitivity table.
Chart
DeLamar after-tax NPV at different gold prices
US$ million at a 5% discount rate; silver moves with gold in each case
The DeLamar feasibility study in Idaho, prepared for Integra Resources, is a useful public example. At $3,000 gold and $35 silver it reports an after-tax NPV at a 5% discount rate of $773.7 million, an IRR of 46% and a 1.8-year payback. It plans about 106,000 gold-equivalent ounces a year over a 10-year operating life, plus five years of residual leaching, at a co-product mine-site AISC of $1,480 per gold-equivalent ounce, with $389.1 million of preproduction capital.
Now move the price. At $2,250 gold and $20 silver, NPV falls to $178.3 million, IRR to 16% and payback stretches to 4.5 years. So a 25% fall in the gold price, paired with a 43% fall in silver in that table, removes 77% of the value. The study’s authors state that the economics are more sensitive to metal prices than to capital or operating costs.
What to do: find the price at which NPV is still acceptable to you, and compare it with spot and with a long-run average. Then check how the same report treats a rise in capital and operating costs. If a report gives no sensitivity table, build your own, or ask why it is missing.
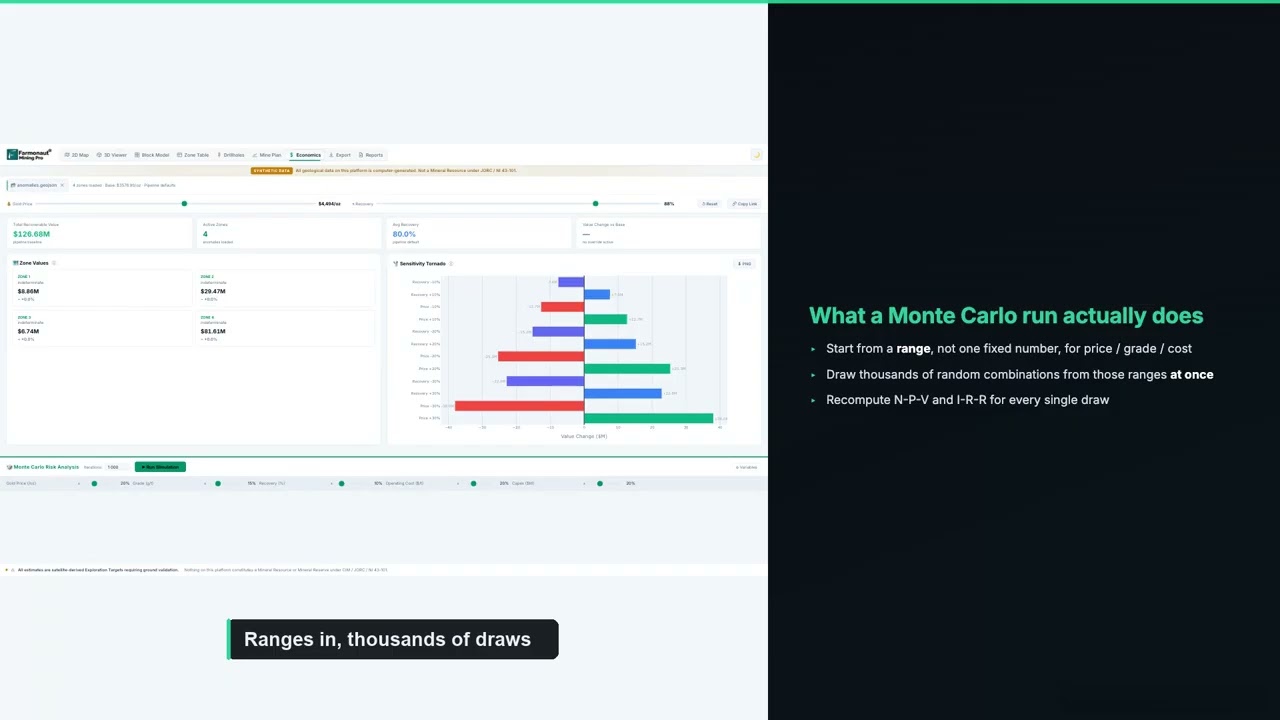
▶ What P10, P50 and P90 mean in mine economics (14:59) · 14:59
Mine economics calculator
Use this for a first pass on any gold project or company with one main asset. It deliberately ignores discounting and financing, so treat the results as a screen before a proper model, not as a valuation.
Calculator
Does the project clear its build cost, and what does the market pay?
Enter your own project or company figures in US$.
- Margin per ounce, US$: $1,500
- After-tax cash per year, US$: $112,500,000
- Simple payback, years: 3.6
- Asking price as multiple of net cash: 0.41
Example values only, not a benchmark or forecast. Prices are inputs: example, use today’s price. Undiscounted, and tax is a simple share of margin, with no debt or closure timing.
Step 5: Check title, jurisdiction and permits
A good deposit on weak title has little value to you. Confirm that the licence or claim is in good standing, who holds it, what royalties and back-in rights sit on it, and when it expires. Do that against the official cadastre or register, not a seller’s summary. In a share purchase, read the property section of the technical report and the notes on royalties in the annual filing.
Jurisdiction also affects timing and cost. The Fraser Institute’s annual survey of mining companies is one widely quoted measure of how they see each region. The Nevada Division of Minerals reports that the state ranked 1st in that survey for 2025 and 2nd for 2024. A ranking is an opinion poll of executives, so use it to frame questions, then read the actual permit list.
Land access can undo good geology. Existing towns, protected areas, water rights and surface owners can all block part of a deposit, however good the grade. S-K 1300 expects permitting work to grow at each study stage, from a list of required permits and agencies in an initial assessment to finalized analysis and completed baseline studies at feasibility level. Ask which permits are in hand, which are applied for and which have not been started.
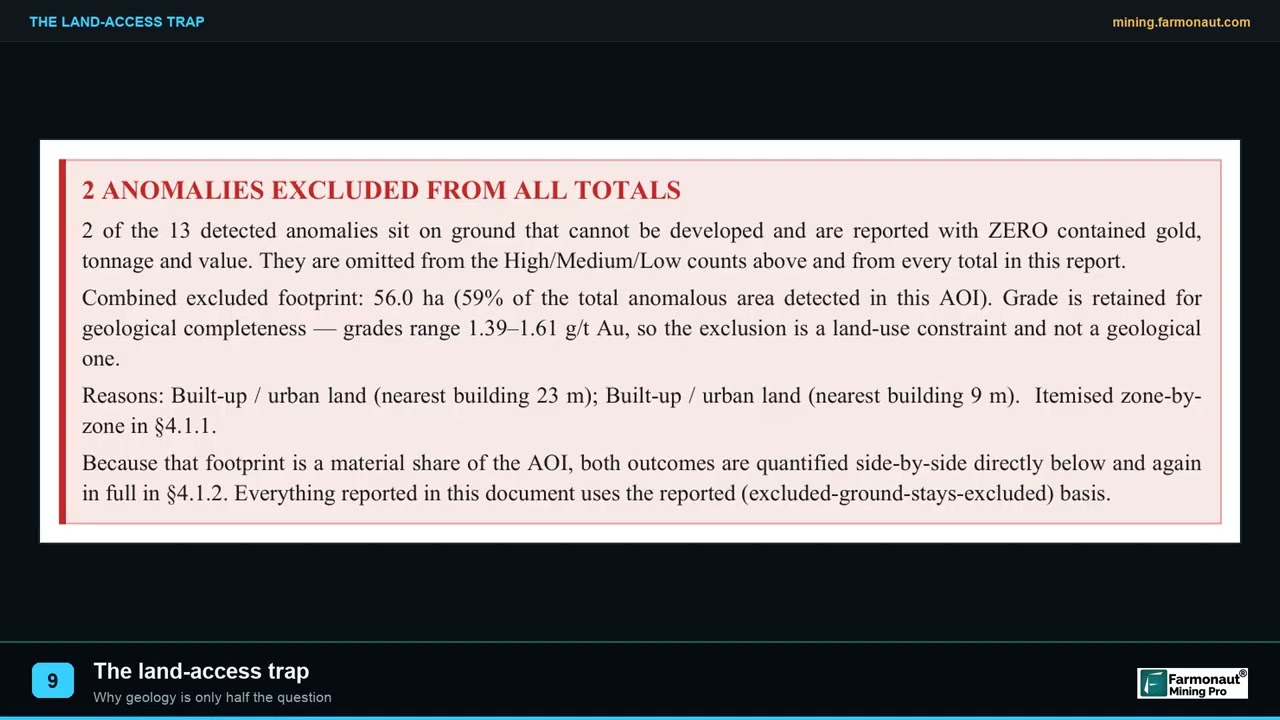
▶ How land access can block good ground (2:05) · 2:05
Step 6: Price closure, tailings and water
Closure is a real cash cost and belongs in the model. The DeLamar study carries $53.5 million of reclamation costs within sustaining capital and shows site reclamation of $65.5 million in its capital table. It also lists existing reclamation bonds with Idaho agencies, which shows how a legacy site’s obligations travel with the property. If you are buying an old mine, you may inherit such liabilities, so have a lawyer confirm what passes to you.
Tailings are the waste left after processing, usually stored behind a dam. The Global Industry Standard on Tailings Management sets 15 principles and 77 auditable requirements for operators. For a listed company, check whether it reports conformance and what its largest facilities look like. For a private site, ask for the design, the responsible engineer and the latest inspection report.
Water is the third item. Check the source, the permit, the discharge route and any treatment that continues after mining ends. Treatment that runs for decades can outlast the revenue that pays for it.
Step 7: Value the company and its funding needs
For a stock, the last step is comparing market value with the assets. Net asset value (NAV) adds up the NPV of each project, plus cash, minus debt and other liabilities. Price-to-NAV divides market value by that figure. A ratio above 1 means the market pays more than the modelled value. A ratio below 1 can mean a discount, or it can mean the market doubts the model. Always build NAV at one stated metal price and one stated discount rate, or two companies will not be comparable.
Then look at how the next stage gets paid for:
- Producers: compare cash flow after capital spending, debt and project capital with the AISC trend. AISC excludes project capital, so a low AISC does not mean a company has no large bills ahead.
- Developers: compare the build cost with cash on hand and market value. A build far larger than the market value usually means new shares, debt, a stream or a partner.
- Explorers: compare cash with yearly spending to see how many months are left. Expect further share sales, and count the shares, options and warrants on a fully diluted basis.
- Royalty companies: they carry little direct operating cost, but their value rests on the assets and operators they hold interests in. Review those in turn.
To see how the large producers compare, use our list of the top gold mining companies. Keep the figures on the same basis and for the same period. This page gives facts and methods only and does not recommend any company or share.
Red flags that end an analysis early
- A contained-metal value in the headline, with no recovery, cost or category attached.
- Economics that lean on inferred material without stating the share.
- A claimed comparison to a famous mine nearby. A neighbour’s result is not evidence for your ground.
- No named qualified person, or a technical report you cannot find on SEDAR+ or EDGAR.
- AISC with no reconciliation to the financial statements.
- A sensitivity table that only shows prices above the base case.
- A seller who refuses a site visit, independent assays or access to the title register.
Where satellite data fits in the process
Satellite imagery is most useful early, before money goes into drilling or a purchase: to screen ground for surface alteration, see land access and existing disturbance, and rank targets. It produces exploration targets, which sit ahead of any resource estimate and do not replace drilling, assays or a qualified person’s report.
Farmonaut’s satellite-based mineral detection works from a boundary file and returns a report in 5 to 20 business days. To discuss a specific licence, use the mining query form or contact the team.
Frequently asked questions
What is mining analysis?
It is the evaluation of a mineral project or mining company across geology, engineering, costs, price risk, legal title, closure and valuation. The aim is a decision: buy, drill further, renegotiate or walk away.
How do analysts evaluate mining stocks?
They usually review reserves and resources, reported unit costs such as AISC, project NPV at stated prices, jurisdiction, debt and funding needs, then compare market value with net asset value. Comparisons only hold when the bases match.
What is the difference between mine analysis and mining stock analysis?
Mine analysis judges one property. Stock analysis adds corporate items such as overheads, debt, cash, other assets and future share issues.
What is a good AISC for a gold mine?
No fixed number is good. What counts is the margin against the gold price you are willing to assume. Among the four large producers in this guide, using their 2025 reports, AISC ran from $1,339 (Agnico Eagle, by-product) to $1,637 (Barrick).
What is the difference between a resource and a reserve?
A resource is material with reasonable prospects of economic extraction. A reserve is the part of a measured or indicated resource shown to be economically mineable after applying mining, processing, legal and other factors in a pre-feasibility or feasibility study.
How accurate is a feasibility study?
Under S-K 1300, cost estimates should reach about ±15%, against about ±25% for a pre-feasibility study and about ±50% for an initial assessment. Actual results can still differ from any of these.
What does price-to-NAV mean for a mining company?
It is market value divided by net asset value. It depends heavily on the metal price and discount rate used, so a ratio is only meaningful with both stated.
What discount rate is used in mine NPV?
It varies by metal, company and risk. The DeLamar gold-silver study reports its NPV at 5%. Run your own model at higher rates for earlier-stage or higher-risk projects.
Which metal price should a mine evaluation use?
Use a stated long-run assumption, then test it against spot and against lower cases. The closer your base case sits to a recent high, the more weight the low cases deserve.
Can a mine be evaluated without drilling?
A first screen can, using public records, geological maps and satellite imagery. A resource estimate or a valuation of tonnage and grade cannot. Those need drilling and assays.
This page is for information only. It is not investment or legal advice. Confirm title and permit rules with the regulator.
Farmonaut mining
Screen a project area from space
Evaluating a company or project? Satellite exploration can screen its ground before you commit to further due diligence.

Mining Pro sample view, synthetic data
Keep reading
Sources
- SEC, Regulation S-K subpart 1300, mining disclosure (eCFR): ecfr.gov
- Ontario Securities Commission, NI 43-101 instruments: osc.ca
- World Gold Council, all-in sustaining costs guidance: gold.org
- USGS, Mineral Commodity Summaries 2026: Gold: pubs.usgs.gov
- Kitco, gold market report, 5 November 2026: kitco.com
- Integra Resources, DeLamar feasibility study (2025): minedocs.com
- Agnico Eagle, 2025 annual report: s205.q4cdn.com
- Barrick, full year and Q4 2025 results: finviz.com
- Kinross, Q4 and full year 2025 results: finviz.com
- Newmont, 2025 Form 10-K: s24.q4cdn.com
- Nevada Division of Minerals, State of Nevada Mining, SME (May 2026): minerals.nv.gov
- ICMM, Global Industry Standard on Tailings Management: icmm.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Klusetic Mining Investments
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited











