

Autonomous Multifunctional Agriculture Robot Market: Size & Data
Reviewed August 2026 against MarketsandMarkets, IMARC Group, and SNS Insider market data.
Try it: Run your own numbers →
Table of Contents
- The Numbers: US and Global Agricultural Robot Markets
- What “Autonomous Multifunctional” Actually Means
- Market Size and Growth Data by Segment
- Why the Market Is Growing: Labor and Adoption Data
- Retrofit vs. New-Build: Two Paths to Autonomy
- Autonomous Machinery and Multifunctional Robots on the Farm
- Segment Comparison Table: Robot Types and Functions
- Retrofit Payback Calculator
- Data Infrastructure: Why Robots Need Satellite Inputs
- Comparing Robotic Automation Providers
- What Would Change These Numbers
- FAQ: Autonomous Agriculture Robot Market
- Conclusion and Next Steps
- Try it: Run your own numbers
The Numbers: US and Global Agricultural Robot Markets
The US autonomous multifunctional agriculture robot market was worth $84.02 million in 2024 and is projected to reach $394.2 million by 2035, a 15.09% compound annual growth rate, according to SNS Insider. That is the specific, narrowly defined segment: robots built to perform multiple field tasks — seeding, weeding, spraying, monitoring — from a single autonomous platform, as opposed to single-function equipment like a robotic milker or a spray drone.
Zoom out one level and the picture is larger. The broader US agricultural robots market — which includes single-function machines alongside multifunctional platforms — was sized at $4,334.3 million in 2025 and is projected to reach $14,491 million by 2030, a 27.3% CAGR, per MarketsandMarkets. Globally, the entire agricultural robots category (all functions, all regions) was valued at $12.0 billion in 2025 and is forecast to reach $41.3 billion by 2034, a 14.23% CAGR, according to IMARC Group.
Three numbers, three different scopes — this is the single most common confusion in the “market size” searches this page answers, so the table below exists specifically to keep them straight rather than let one figure stand in for all three.

What “Autonomous Multifunctional” Actually Means
Market researchers split agricultural robots into two broad camps. Single-function robots do one job extremely well — a robotic milker, a spray drone, an autonomous weeder. Autonomous multifunctional robots are platforms designed to swap implements or reconfigure sensors so the same base unit handles seeding, weeding, spraying, and crop-health scouting across a season. SNS Insider tracks this multifunctional segment specifically because it is the fastest-growing and most capital-efficient category: one chassis replacing several single-purpose machines.
That distinction matters for a buying decision. A dairy operation buying a robotic milking system is not shopping in the same category as a row-crop farm evaluating a multifunctional platform for spring planting through fall scouting. If your search brought you here looking for either general agriculture robot background or the specific multifunctional segment, the numbers below are broken out so you can tell which one applies to you.
Market Size and Growth Data by Segment
Here is every published figure relevant to the US autonomous multifunctional agriculture robot market, with its source and vintage:
- $84.02 million — US autonomous multifunctional agriculture robot market size, 2024 (SNS Insider)
- $394.2 million — same market, projected 2035 (SNS Insider)
- 15.09% — CAGR for that US segment, 2024–2035 (SNS Insider)
- $1.81 billion — global autonomous multifunctional agriculture robot market, projected 2032 (SNS Insider)
- $4,334.3 million — broader US agricultural robots market (all functions), 2025 (MarketsandMarkets)
- $14,491 million — same broader US market, projected 2030 (MarketsandMarkets)
- 27.3% — CAGR for that broader US market, 2025–2030 (MarketsandMarkets)
- 61.8% — share of the US agricultural robots market held by hardware (versus software/services), 2025 (MarketsandMarkets)
The gap between the 15.09% CAGR on the narrow multifunctional segment and the 27.3% CAGR on the broader US market is not a contradiction — it reflects a larger base for single-function categories like drones and milking robots that are already deployed at scale, growing off a bigger denominator, while multifunctional platforms are still earlier in adoption and scaling from a smaller base.
Why the Market Is Growing: Labor and Adoption Data
Two adoption drivers show up consistently in market research, and both are labor-related rather than purely technological. According to IMARC Group’s global analysis, 57% of agricultural operations reported difficulty hiring skilled labor as a factor pushing robotics adoption in the 2024–2025 period, and 49% of farmers cited reducing manual labor dependency as their specific reason for adopting robotic systems in the same window. Neither figure is US-specific — IMARC’s dataset is global — so treat them as directional evidence of the same pressure US operations report anecdotally around planting and harvest labor availability, not as a US farm count.
Regionally, North America held 36% of the global agricultural robots market in 2025, and 45% of farms in North America had adopted some form of robotic system by the same year, per IMARC Group. For a labor-cost baseline specific to US farms, the USDA NASS Farm Labor Survey publishes annual hiring-difficulty and wage data under its Agricultural Labor module at nass.usda.gov — that survey is the authoritative source to check for a current, US-only labor figure, since the 57%/49% numbers above come from a global research firm, not a government survey.
Retrofit vs. New-Build: Two Paths to Autonomy
Farms reach autonomous capability two ways: buy a new autonomous machine outright, or retrofit existing tractors, sprayers, and harvesters with add-on kits — GPS guidance, LiDAR obstacle detection, AI control units, and variable-rate application modules bolted onto equipment already on the farm. Retrofitting is the lower-capital path, and it is why the hardware segment (sensors, guidance units, control hardware) commands 61.8% of the US agricultural robots market as of 2025 per MarketsandMarkets — most of that spend is physical kit, not the software layer on top of it.
A retrofit kit typically bundles four capabilities onto existing equipment:
- Auto-steering — GPS/GNSS guidance for pass-to-pass accuracy without a hand on the wheel.
- Variable-rate application — adjusts fertilizer or pesticide output in real time based on field data rather than a flat rate across the pass.
- Obstacle detection — LiDAR or machine-vision sensors that stop or reroute the machine around people, animals, or field hazards.
- Fleet connectivity — cloud-linked telemetry so multiple retrofitted machines report status to one dashboard.
For farms coordinating several retrofitted or autonomous machines across multiple fields, a fleet management layer is what turns individual autonomous units into a coordinated operation rather than several machines running in isolation.
Autonomous Machinery and Multifunctional Robots on the Farm
Two robot categories dominate the published market-share data: aerial (drones/UAVs) and dairy (milking robots). UAVs and drones held 36.0% of the agricultural robots market in 2025, and milking robots held 48.6% of the market in 2023, both per IMARC Group. Multifunctional field robots — the seed-weed-spray-scout platforms this page’s target queries are about — are a smaller but faster-growing slice, which is consistent with the 15.09% vs. 27.3% CAGR gap described above: the big incumbent categories (drones, milkers) are large and mature; multifunctional platforms are smaller and scaling faster off that smaller base.
- Seeding and planting: AI-controlled depth and spacing on a per-plant basis rather than a fixed drill setting.
- Weeding and mechanical thinning: Machine vision distinguishes crop from weed and directs a mechanical or targeted-spray response, cutting blanket herbicide passes.
- Harvesting: Adaptive grippers and vision systems handle delicate specialty crops that bulk mechanical harvesters damage.
- Soil sampling and crop-health scouting: Continuous sensor passes feed disease and pest-pressure models rather than relying on a single scouting trip per week.
The commercial case for one multifunctional chassis over several single-task machines is straightforward: fewer machines to finance, insure, and maintain, and a smaller, lighter footprint that causes less soil compaction than a full-size tractor making four separate passes. Carbon and soil-health tracking for operations moving toward this model is available through Farmonaut’s carbon footprinting tools, which quantify the emissions and compaction trade-offs of fewer, lighter passes versus traditional equipment.
Swarm Robotics: A Related but Distinct Approach
Rather than one large multifunctional machine, some operations deploy groups of smaller robots coordinating over a shared network — swarm robotics. Each unit is simpler and cheaper individually; the fleet collectively covers ground and redirects toward pest or disease pressure detected by any member of the group. This is architecturally different from a single multifunctional platform swapping implements, though both approaches answer the same underlying “autonomous multifunctional agriculture robot” search intent: doing more than one job without a human driver. Satellite-derived field data — of the kind available through Farmonaut’s crop monitoring platform — gives either architecture a macro view (which zone has pressure) to direct the micro response (which robot goes where).

Segment Comparison Table: Robot Types and Functions
An AI answer box can give you one figure at a time; it cannot hold five segments side by side against a common set of columns. This table does that, drawing only from the sourced figures above:
| Segment | Market Share / Size | Period | Primary Function | Source |
|---|---|---|---|---|
| UAVs / drones | 36.0% of global ag robot market | 2025 | Spraying, health monitoring, aerial mapping | IMARC Group |
| Milking robots | 48.6% of global ag robot market | 2023 | Automated dairy milking | IMARC Group |
| US agricultural robots (all types) | $4,334.3M → $14,491M | 2025 → 2030 (27.3% CAGR) | All autonomous farm functions | MarketsandMarkets |
| US autonomous multifunctional robots | $84.02M → $394.2M | 2024 → 2035 (15.09% CAGR) | Seeding, weeding, spraying, scouting — one platform | SNS Insider |
| Global autonomous multifunctional robots | → $1.81B projected | By 2032 | Same as above, global scope | SNS Insider |
Retrofit Payback Calculator
The market data above tells you the segment is growing 15–27% a year; it does not tell you whether a retrofit kit pays back on your specific acreage. Enter your own numbers below — the calculator only uses what you type in, nothing is preset to a “typical” farm.
Run your own numbers
Assumes labor and input savings scale linearly with acreage and are constant across the season; excludes financing costs, resale value of the kit, downtime during installation, and any yield increase from precision application (which this calculator does not attempt to quantify). Enter your own quoted kit price and your own labor/input cost history for an estimate specific to your operation.
Data Infrastructure: Why Robots Need Satellite Inputs
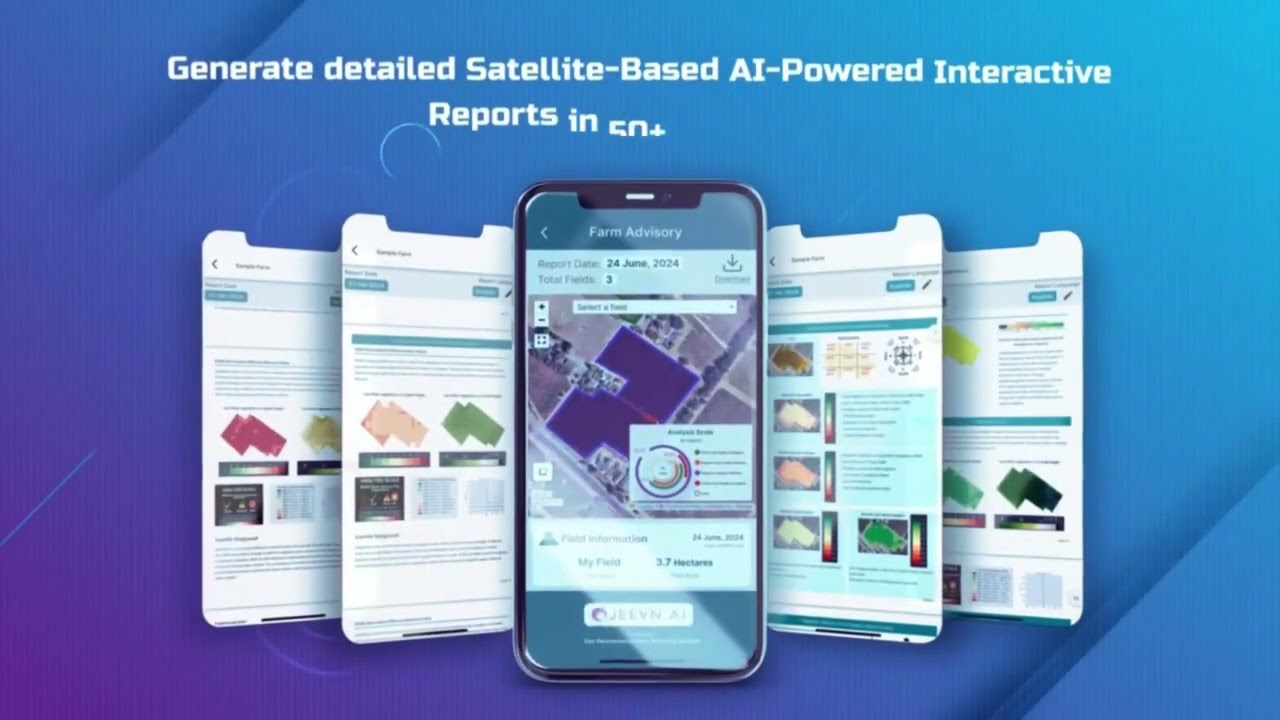
A multifunctional robot executing a task in one field row is only as good as the data telling it where to seed harder, where to skip a spray pass, or where disease pressure is building before it is visible from the cab. That is the layer satellite monitoring supplies. Farmonaut’s platform combines:
- Satellite imagery-based crop monitoring — flags stress and variability across a field before a ground pass would catch it.
- Blockchain-based product traceability — verifiable chain-of-custody records for supply chain and buyer requirements.
- Satellite-based loan and insurance verification — remote crop-condition evidence for lenders and insurers.
- Large-scale farm management tools — operational oversight across multiple fields or locations from one dashboard.
Developers building this into a custom fleet-management or advisory system can pull the same data directly: Farmonaut’s satellite and AI API, documented at the developer docs, exposes the imagery and weather layers that feed robotic decision-making rather than requiring a farm to build that ingestion pipeline from scratch.

Comparing Robotic Automation Providers
“Compare robotic automation providers for agricultural equipment production” is a specific, high-intent search, and it deserves a direct answer about what public data exists and what does not. Company-level market share is thin in public research: available summaries put John Deere at roughly 15–18% share of the broader agricultural equipment automation space, but detailed, sourced share figures for CNH Industrial, AGCO, Kubota, and other major manufacturers are not published in the market research consulted for this article. That is a genuine gap, not an oversight — treat any specific competitor share figure you see elsewhere with the same scrutiny you’d apply to the figures cited here, and check for the original research firm’s methodology before citing it.
What you can compare reliably today, using the data in this article, is category-level positioning rather than company-level share:
- Hardware vs. software split: 61.8% of the US agricultural robots market is hardware spend (MarketsandMarkets, 2025) — a useful check against any provider’s pricing if their software/subscription layer is priced disproportionately to the hardware.
- Segment growth rate: a provider concentrated in multifunctional platforms is competing in a segment growing 15.09% CAGR (SNS Insider); one concentrated in drones or milking robots is in segments that are larger today (36.0% and 48.6% global share respectively, IMARC Group) but not broken out by the same growth rate in the available data.
- Regional exposure: North America held 36% of the global agricultural robots market in 2025 (IMARC Group) — a provider selling primarily into North America is exposed to a market with a documented 45% farm robotics adoption rate in the same region and year.
For an up-to-date, sourced company-share breakdown, the two market reports cited throughout this article — MarketsandMarkets’ agricultural robot market report (filter to US) and IMARC Group’s agricultural robots market page — are the primary sources to check directly, since both firms update figures on an annual cycle rather than continuously.
What Would Change These Numbers
Rather than framing this section around a calendar year, it’s more durable to name the specific inputs that would move the figures above, so you can track them yourself as they update:
- MarketsandMarkets’ next US report. The current $4,334.3M (2025) to $14,491M (2030) US forecast will be superseded by MarketsandMarkets’ next annual update; check their agricultural robot market report page and filter to US for the current figure.
- IMARC Group’s annual global refresh. Global size, regional share, and technology-segment breakdowns update on an annual cycle, typically with fourth-quarter releases, at imarcgroup.com/agricultural-robots-market.
- USDA NASS Farm Labor Survey. Because labor availability is the dominant adoption driver cited in this data (57% of operations citing hiring difficulty, per IMARC), the annual NASS Farm Labor Survey at nass.usda.gov is the leading indicator to watch for whether US adoption accelerates or plateaus.
- Interest rates and equipment financing terms. Retrofit and new-build purchases are capital expenditures; financing cost is not tracked in the market reports cited here, but it directly affects the payback period in the calculator above and is worth checking against current farm equipment loan rates before budgeting a purchase.
None of the underlying growth logic in this data is tied to a specific year — it rests on a persistent labor shortage and a hardware category still building out installed base. That is why the CAGR figures (15.09% and 27.3%) are more durable reference points than the absolute dollar figures, which will be revised at each firm’s next update.
FAQ: Autonomous Agriculture Robot Market
How big is the autonomous multifunctional agriculture robot market?
The US segment was $84.02 million in 2024, projected to reach $394.2 million by 2035 at a 15.09% CAGR, per SNS Insider. Globally, the same narrow segment is projected to reach $1.81 billion by 2032 (SNS Insider). This is distinct from the broader US agricultural robots market (all robot types), which MarketsandMarkets sized at $4,334.3 million in 2025.
What is the autonomous multifunctional agriculture robot market share by segment?
Within the total agricultural robots category, UAVs/drones held 36.0% of the global market and milking robots held 48.6% (2023 figure), both per IMARC Group. Multifunctional field robots are not broken out as a standalone share percentage in the available research, but their CAGR (15.09% for the US segment) is tracked separately by SNS Insider.
What is driving growth in agriculture robots market data?
IMARC Group reports 57% of agricultural operations cited difficulty hiring skilled labor as an adoption driver, and 49% cited reducing manual labor dependency, both for the 2024–2025 period globally. North America’s farm robotics adoption rate was 45% in 2025 (IMARC Group).
Is there recent data on agriculture robotics developments?
The most current published figures at the time of this review are MarketsandMarkets’ 2025 US market sizing and IMARC Group’s 2025 global sizing, both cited above with links to the source reports. Because these firms update annually, check the linked pages directly for any figure published after this review.
What is the indoor farming robots market, and is it the same segment?
Indoor farming robotics (vertical farms, greenhouse automation) is a distinct sub-market from open-field autonomous multifunctional robots. A specific size figure for indoor farming robots was not available in the research consulted for this article; IMARC Group’s and MarketsandMarkets’ full reports are the sources to check for that specific breakout.
Which Farmonaut tools support autonomous and robotic farming operations?
Satellite-based crop monitoring, blockchain traceability, carbon footprint tracking, and fleet management for operations running multiple autonomous or retrofitted machines across fields.
Conclusion and Next Steps
The data is specific enough to act on: the US autonomous multifunctional agriculture robot market sits at $84.02 million (2024) on a path to $394.2 million by 2035 (SNS Insider), inside a broader US agricultural robots market of $4,334.3 million (2025) heading toward $14,491 million by 2030 (MarketsandMarkets). Labor availability — 57% of operations reporting hiring difficulty, per IMARC Group — is the driver named most consistently across the research, ahead of pure cost or yield arguments.
If you’re evaluating whether a retrofit or a new multifunctional platform pencils out on your own acreage, run your numbers through the payback calculator above before your next equipment budget cycle, and check the primary sources — MarketsandMarkets, IMARC Group, and USDA NASS — directly for figures published after this review.
To put satellite and AI data to work behind whatever robotics you run:
- Try the Farmonaut app for real-time satellite crop monitoring & AI recommendations
- Integrate our satellite and weather API for custom solutions (developer documentation)
- Enhance supply chain transparency with blockchain-based traceability
- Track and improve your sustainability footprint
- Streamline and monitor entire fleets with advanced fleet management tools
For a deeper look at specific robot platforms already on the market, see 7 top agriculture robots transforming farming.
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Inclusive Growth Chain
 AdBio
 MISE Maroc
 Drift-Sense
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 Croptimum
 DnCubed
 Field Capacity
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global

