

Farm finance · US crop insurance guide
Agriculture Insurance: Types, Costs and Subsidy Rates
The Federal Crop Insurance Program covered about 89% of the acres of eight major US field crops in 2024, and the government paid $10.4 billion of premiums (USDA ERS). This guide compares the main policy types, shows the subsidy rates in force since July 2025 and estimates your own cost per acre.
Key takeaways
- In 2024 federal crop insurance covered about 89% of acres of eight major field crops, 543 million insured acres and more than $192 billion of liability (USDA ERS).
- Since July 2025 the subsidy on basic and optional units is 3 to 5 points higher: 60% at 75% coverage and 41% at 85% (RMA MGR-25-006).
- Drought and heat caused 41% of indemnities since 2000, and excess moisture 27% (USDA ERS).
- Revenue Protection is the main individual plan; area plans such as SCO and ECO now get an 80% subsidy (American Farm Bureau).
- Canada’s AgriInsurance is cost-shared and run by each province (Agriculture and Agri-Food Canada).
In this article
- What agriculture insurance covers
- Main types of agriculture insurance in the US
- What causes most crop insurance claims
- Premium subsidies and the changes
- How much agriculture insurance costs a farmer
- How to choose a coverage level
- Agriculture insurance in Canada, the UK and Australia
- Technology changing farm insurance
- Limits and common problems
- FAQ
Agriculture insurance pays a farmer when weather, disease or a price drop cuts the value of a crop or herd below a guaranteed level. In the US it is mostly the Federal Crop Insurance Program: in 2024 it covered about 89% of the acres of eight major field crops, and the government paid $10.4 billion of farmers’ premiums, according to the USDA Economic Research Service (ERS) crop insurance overview. Since July 2025 the federal share of most premiums is 3 to 5 points higher than before.
This guide explains the main types of farm and agriculture insurance, what each one costs a farmer after the subsidy, and how to pick a coverage level. It includes the current subsidy table, charts of what causes most claims, and a calculator that estimates your own share of the premium per acre. It also covers Canada’s AgriInsurance and the new technology insurers use to check losses.
Not financial advice. Rules, prices and subsidy rates change each year and differ by crop, county and province. Check your own policy and talk to a licensed crop insurance agent, your provincial agency or a farm financial adviser before you buy.
What agriculture insurance covers
Farm insurance comes in two broad groups. Property and liability cover (barns, machinery, vehicles, injury to visitors) is bought from private insurers like any business policy. Crop and livestock insurance covers the farm’s output. In the US this second group is run as a public-private partnership: private companies sell and service the policies, and the Federal Crop Insurance Corporation sets the rules, subsidizes premiums and shares losses.
The USDA Risk Management Agency (RMA) says federal policies protect against drought, excess moisture, freeze, hail, wind, disease and price falls. For crop year 2024 it offered cover for more than 120 commodities, which the ERS says is most of the value of US crop production.
The program is large. Insured acres rose from 206 million in 2000 to 543 million in 2024, and total liability passed $192 billion in 2024 (ERS). Much of the recent rise in acres came from pasture, rangeland and forage cover, which made up 56% of insured acres in 2024 but only 4% of liability.
Who pays for it
Farmers pay part of the premium. The government pays the rest as a subsidy, plus the companies’ costs of selling and adjusting policies. Since 1997 the program’s loss ratio has averaged 0.85, meaning claims paid have been about 85% of total premiums (ERS). A loss ratio under 1.0 across the whole pool does not mean a single farm will get back less than it pays: farms with frequent losses can collect more than they pay for years in a row.
Chart
Acres insured under the Federal Crop Insurance Program
Million acres, selected crop years
Main types of agriculture insurance in the US
The ERS groups federal products into individual policies, which pay on your own farm’s loss, and area or index policies, which pay on a county yield, rainfall or other index. Individual policies split again into yield and revenue protection. The table below lists the products a row-crop, livestock or specialty farm will most often see.
| Product | What triggers a payment | Best for |
|---|---|---|
| Revenue Protection | Your yield times harvest or projected price falls below your guarantee | Corn, soybean, wheat and cotton farms that sell on the futures market |
| Yield Protection | Your yield falls below your coverage level of your production history | Farms that only want to cover lost bushels |
| CAT coverage | Yield below 50%, paid at 55% of price | Low-cost minimum cover; the farmer pays a $655 admin fee per crop per county, not a premium |
| SCO and ECO | County yield or revenue falls below a trigger | Topping up an individual policy toward 86% to 95% |
| Whole-Farm (WFRP) | Whole-farm revenue falls below the guarantee | Diverse, specialty, organic or direct-market farms |
| PRF | Rainfall index in your grid falls below normal | Ranchers with pasture, rangeland or hay |
| LRP and LGM | Livestock price or margin falls below a chosen level | Cattle, hog, lamb and dairy producers |
Individual yield and revenue plans
Revenue Protection is the plan most US grain farmers choose. The ERS notes that individual revenue policies have made up most insured liability for the last decade. Your guarantee is your actual production history (APH) yield times your coverage level times the higher of the projected or harvest price. If your bushels times the harvest price fall below that, the policy pays the gap.
Yield Protection uses the projected price only. It costs less but does not pay when prices fall while yields hold.
Area and index plans
Area and index plans pay on a county or grid result, not your own field. They are cheaper to run because no one has to inspect your crop. The risk is “basis risk”: your field can fail while the county does fine, and you get nothing. Area and index plans held 24% of total liability in 2024 and overtook individual yield plans in 2021 (ERS).
The Supplemental Coverage Option (SCO) and Enhanced Coverage Option (ECO) sit on top of an individual policy and cover part of the deductible. Under the July 2025 law, ARC enrollees can now buy SCO too, SCO coverage can now reach 90% from 2027 (ECO already goes to 95%), and the subsidy for these area plans rose from 65% to 80%, according to the American Farm Bureau summary of the One Big Beautiful Bill Act.
Whole-farm and livestock plans
Whole-Farm Revenue Protection covers all commodities on the farm under one policy. RMA says it is sold in all counties and fits farms with up to $17 million in insured revenue, including specialty, organic and direct-market farms. A smaller Micro Farm version exists for very small operations.
For ranchers, Pasture, Rangeland and Forage (PRF) pays when rainfall in a grid area falls below its long-term index. Livestock Risk Protection (LRP) and Livestock Gross Margin (LGM) protect against falling prices or margins rather than lost animals. The IRS treats LRP and LGM payouts as crop insurance for tax purposes.
What causes most crop insurance claims
Weather drives most losses. The ERS reports that drought and heat were the leading cause of claims in 14 of the 25 years since 2000 and made up 41% of all indemnities over that time. Excess moisture made up another 27%.
Chart
Share of federal crop insurance indemnities by cause
Percent of total indemnity payments, 2000 to 2024
Annual indemnities rose by an average of 17% a year after 2000, partly because more acres and higher crop values are insured. A bad year can still be very bad: claims swing with drought, floods and prices.
Knowing your own main risk helps you choose. A farm on light soil in a dry area may want high coverage and revenue cover. A farm in a wet river bottom may care more about prevented planting rules.
Premium subsidies and the changes
The government pays a share of each premium, and that share falls as you buy higher coverage. It is also higher for enterprise units, which combine all your fields of one crop in a county into one unit. Since policies with a sales closing date on or after 1 July 2025, RMA’s Manager’s Bulletin MGR-25-006 sets these rates for policies under the Common Crop Insurance Policy:
| Coverage level | Basic or optional unit | Enterprise unit |
|---|---|---|
| 50% | 67% | 80% |
| 55% | 69% | 80% |
| 60% | 69% | 80% |
| 65% | 64% | 80% |
| 70% | 64% | 80% |
| 75% | 60% | 80% |
| 80% | 51% | 71% |
| 85% | 41% | 56% |
Before the law, basic and optional units got 64% at 65% coverage, 59% at 70%, 55% at 75%, 48% at 80% and 38% at 85%, as listed in a farmdoc daily article from November 2023. An NDSU Agricultural Risk Policy Center analysis calls this the first change to these rates since 2000 and puts the extra premium support at more than $1 billion a year nationwide.
Help for beginning farmers
The same law widened the definition of a beginning farmer or rancher from five to 10 years of experience. It also adds extra subsidy on top of the usual 10-point beginning-farmer boost: 15 points in the first two years, 13 in year three, 11 in year four and 10 from year five to year 10 (American Farm Bureau). The Farm Bureau says the law also directs a new pilot product for contract poultry growers.
Some later farm bill drafts may change these rules again. The Congressional Research Service comparison of the House and Senate farm bills tracks proposals still under debate. Check the current rules with your agent before each sales closing date.
Chart
Federal share of the premium by coverage level
Basic and optional units, percent of premium paid by the government, policies with sales closing on or after 1 July 2025
How much agriculture insurance costs a farmer
There is no single price. Your premium depends on your crop, county, APH yield, the projected price, the plan, the unit type and the coverage level. RMA publishes the actuarial rates, and agents run quotes with them. Two rules of thumb hold everywhere:
- Higher coverage costs more per acre, and your subsidy share also falls, so the last 5 points of coverage are the most expensive.
- Enterprise units cost less than basic or optional units at the same coverage level, but losses on one field can be offset by good yields on another.
The calculator below shows how the subsidy changes your out-of-pocket cost. It needs a total premium rate, which you can get from your agent’s quote or from RMA’s cost estimator. The defaults are example values only, not a quote.
Try the numbers for your own farm below.
How to choose a coverage level
Use these steps before the sales closing date for your crop, which for spring crops in much of the Corn Belt is mid-March.
- Know your break-even. Add your cost per acre (seed, fertilizer, rent, machinery, interest). University budgets such as the farmdoc Illinois crop budgets for 2027 give a starting point.
- Check your lender. Many operating loans need a minimum coverage level. Satellite-backed field records can help when you apply for crop loans and insurance.
- Compare 70%, 75%, 80% and 85% quotes. Look at the guarantee per acre and the cost of each extra 5 points.
- Pick a unit structure. Enterprise units cost less; optional units pay field by field.
- Decide on add-ons. SCO or ECO can cover part of the deductible at a high subsidy, but they pay on county results.
- Keep records. Planting dates, yields and photos speed up claims. Report damage to your agent within 72 hours of discovery and confirm it in writing within 15 days.
Agriculture insurance in Canada, the UK and Australia
Canada runs AgriInsurance as a cost-shared program with the federal and provincial governments. Agriculture and Agri-Food Canada says each province designs and delivers its own plans for production losses and quality loss from natural hazards. Plans cover field crops such as wheat, corn, oats and barley and horticultural crops such as strawberries and carrots. Some provinces also cover bee losses and maple syrup.
The UK and Australia have no national subsidized crop insurance scheme like the US or Canada. Farmers there buy cover privately: hail and fire cover for standing crops is common, and some insurers sell weather-index or multi-peril products. Prices and terms vary by insurer, so compare several quotes and read the exclusions carefully.
Technology changing farm insurance
Insurers and agtech companies now use satellites, weather data and AI to price risk and check claims. Five changes stand out:
- Satellite crop maps. Sentinel-2 and Landsat show crop vigor every few days, so damage can be mapped across a whole county after a storm.
- Index products. PRF uses gridded rainfall data, so no one needs to visit the pasture.
- Digital claims. Photos, GPS field boundaries and yield monitor files can be sent straight to the adjuster.
- Weather and soil models. Crop models help insurers rate new areas and crops.
- Data APIs. Insurers plug satellite and weather data into their own systems through tools such as the satellite and weather API.
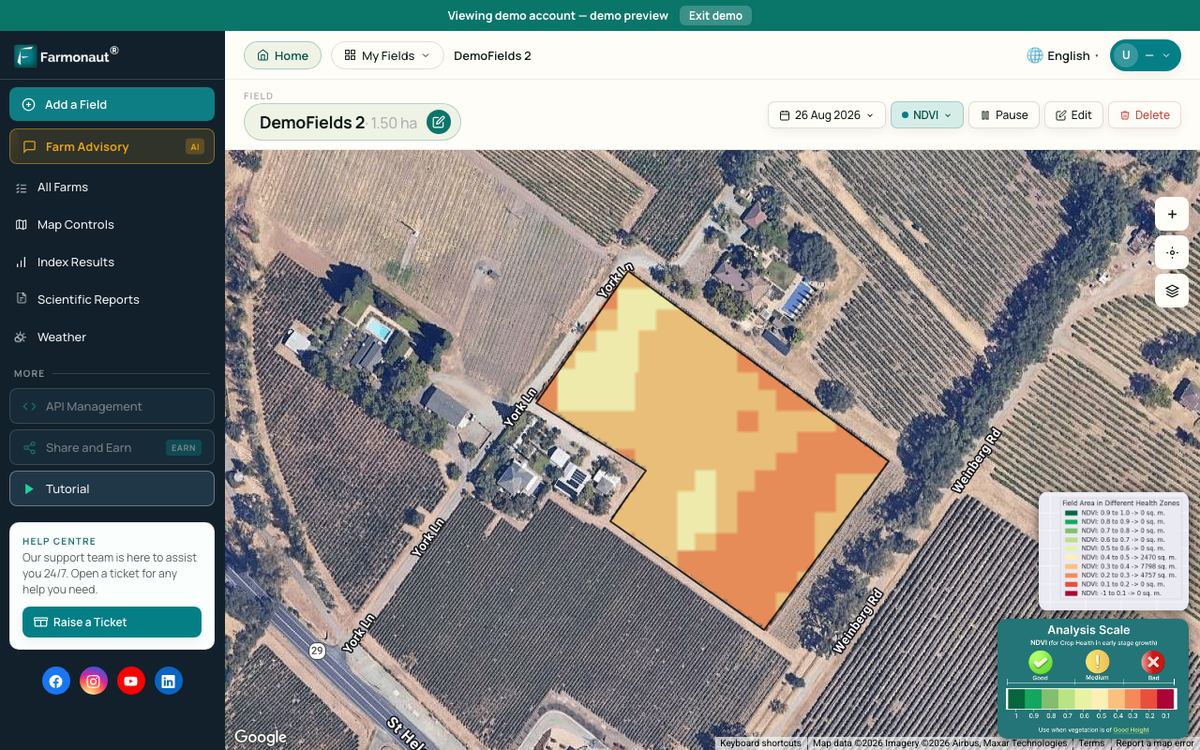
Farmonaut, a US-based company, offers field-level satellite crop health maps that farmers can use to spot stress early and keep a dated record of crop condition. That record does not replace an adjuster’s inspection, but it can help you report damage quickly and with evidence.
▶ How satellite NDVI maps show crop stress across a large farm before it is visible on foot. · 4:09
Limits and common problems
Agriculture insurance does not cover everything. Most plans do not pay for losses caused by poor farming practice, and late planting can cut your guarantee. Index plans carry basis risk. Prices set in spring can leave a gap if input costs rise later.
Premium subsidies cost taxpayers billions a year, and some economists argue the high subsidy on top coverage levels encourages farming on marginal land. Others say broad cover reduces the need for ad hoc disaster payments, the policy reason given for subsidies in the farmdoc article cited above.
Insurance payouts are taxable. The IRS Farmer’s Tax Guide (Publication 225) says you must include crop insurance proceeds in income, though in some cases you can choose to report them the following year. Ask a tax adviser how this applies to you.
Insurance works best alongside other risk tools: diverse crops, good soil and water care, and marketing plans. See our guides to climate-smart farming practices and sustainable farming practices for ideas that cut the size of losses in the first place.
▶ Mixing crops and livestock spreads risk, one way to soften a bad year alongside insurance. · 2:55
FAQ
What is agriculture insurance?
It is insurance that pays farmers when crops, livestock or farm revenue fall below a guaranteed level because of weather, disease, pests or price changes. In the US most crop cover is federally reinsured and subsidized, and sold by private agents.
Is crop insurance required in the US?
No. It has been voluntary since 1996 (ERS). Many lenders require it for operating loans, and some USDA programs ask for cover or a waiver.
How much of the premium does the government pay?
Between 41% and 80% for most policies, depending on coverage level and unit type, under RMA’s rates effective from July 2025. CAT coverage is fully subsidized apart from an admin fee.
What is the difference between private and federal crop insurance?
Federal policies are sold by private companies but follow USDA rules and get subsidies. Private crop-hail and named-peril policies are sold outside the program, carry no subsidy, and can top up a federal policy.
Do tech companies sell agriculture insurance?
Some agtech firms work with insurers by providing satellite, weather and claims data, and a few sell index products. Most US crop policies are still sold by approved insurance providers through licensed agents.
Can satellite images be used in a crop insurance claim?
They can support a claim as a dated record of crop condition, but the insurer’s adjuster makes the loss decision. Keep your own photos and records too.
Related pages on our site: satellite precision agriculture innovations, traceability, carbon footprinting, large-scale farm management, Farmonaut app.
Farmonaut crop monitoring
Keep a dated satellite record of your fields
Draw your fields once and Farmonaut shows satellite crop health maps through the season, on web, Android or iOS.
Keep reading
Sources
- USDA Economic Research Service, Risk Management: Crop Insurance at a Glance (updated 23 September 2025): ers.usda.gov
- USDA Risk Management Agency, MGR-25-006 One Big Beautiful Bill Act Amendment (2025): rma.usda.gov
- USDA Risk Management Agency, Whole-Farm Revenue Protection: rma.usda.gov
- USDA Risk Management Agency, About Crop Insurance: rma.usda.gov
- American Farm Bureau Federation, One Big Beautiful Bill Act: Final Agricultural Provisions (2025): fb.org
- NDSU News, NDSU research explores new farm bill (18 July 2025): ndsu.edu
- farmdoc daily, Understanding the relationship between loss ratios and crop insurance subsidies (21 November 2023): origin.farmdocdaily.illinois.edu
- farmdoc daily, Illinois Crop Budgets for 2027 (September 2026): farmdocdaily.illinois.edu
- Congressional Research Service, The 2026 Farm Bill: Comparison of the House and Senate Bills with Current Law (R48918): everycrsreport.com
- Agriculture and Agri-Food Canada, AgriInsurance program: agriculture.canada.ca
- Internal Revenue Service, Publication 225, Farmer’s Tax Guide (2025): irs.gov
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Mera Farmhouse
 GalaxEye Space
 Sun Palm Australia
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 DnCubed

 Licence holder · Niger · Gold
 Licence holder · Nigeria · Gold + lithium










