

Farm finance · Texas lending guide
Agriculture Business Loan Options in Texas: Rates, Limits
FSA charged 5.625% on direct operating loans and 6.25% on direct ownership loans in November 2026. Bankers in the Dallas Fed survey averaged 7.46% to 8.05% fixed in the third quarter. Compare limits, Texas programs and grants, then test the payment.
Key takeaways
- FSA direct rates, November 2026: 5.625% operating, 6.25% ownership, 4.25% joint financing, 2.25% down payment, 3.75% emergency (USDA).
- Limits: $50,000 microloan, $400,000 direct operating, $600,000 direct ownership, $2,558,000 guaranteed (FSA).
- Average bank rates in the Dallas Fed district: 8.05% fixed on operating and 7.46% on long-term real estate, Q3 2026.
- Texas’s TAFA rate program can lower pricing on loans up to $1,000,000; AgPRO grants reach $500,000 with a 10%-30% match.
- Farm Credit reports $43.5 billion in Texas loans at the end of 2025; FSA’s Texas portfolio is about $1.2 billion.
In this article
- Agriculture business loan rates in Texas
- Who lends to Texas farm businesses
- Federal farm loan limits and terms
- Texas state programs that lower your rate
- Agricultural business grants in Texas
- How to choose the right agriculture business loan
- Compare the main loan programs
- Can your agriculture business loan pay for itself?
- How to apply, step by step
- FAQ
An agriculture business loan in Texas usually comes from one of three places: USDA’s Farm Service Agency (FSA), a Farm Credit association, or a bank. In November 2026 FSA charged 5.625% on direct operating loans and 6.25% on direct farm ownership loans, according to USDA’s November 2026 rate notice. Texas-area bankers reported average fixed rates of 7.46% to 8.05% in the Dallas Fed third-quarter survey.
The right door depends on how much you need, what the money is for and whether a commercial lender will say yes. This guide compares limits and rates, explains Texas state programs and grants, and gives you a calculator to test a payment against your own cash flow. Outside Texas, the FSA programs work under the same federal rules; our guide to ag loans covers the wider picture, and this page on agriculture business loan trends covers the market.
Agriculture business loan rates in Texas
Rates split into two groups. FSA publishes its direct rates each month, so everyone who qualifies for a program in that month sees the same published figure. Banks and Farm Credit associations set their own rates for each borrower, so the survey numbers below are averages and not quotes.
Chart
FSA direct loan rates through 2026
Percent, monthly notices, selected months
FSA rates climbed through 2026. The direct operating rate moved from 4.625% in January to 5.625% in November, one full point in ten months. The direct ownership rate rose from 5.625% to 6.25% over the same period. If you got a quote early in the year, ask for a new one.
Bank rates are lower than a year ago but have turned up. In the Dallas Fed survey of 50 agricultural bankers, collected 1 to 9 September 2026, the average fixed rate on other farm operating loans was 8.05%, against 7.78% in the second quarter and 8.30% in the third quarter of 2025. Long-term farm real estate averaged 7.46% fixed and 7.54% variable. The survey covers the Eleventh Federal Reserve District, which includes Texas, northern Louisiana and southern New Mexico.
Credit is tighter and demand is weaker
The same survey shows why a lender may look harder at your file. Of the bankers who responded, 18.4% said credit standards were up on a year earlier, and none said they were down. Loan demand fell, with 28.3% reporting less demand and 2.9% reporting more. Availability of funds rose slightly. Bankers also described heat and drought hurting yields, and ranchers culling herds, so expect questions about your water, grazing and insurance plans.
Nationally, USDA’s Economic Research Service forecasts farm sector debt up 4.6% to $605.1 billion in 2026. FSA lending has grown as well: American Farm Bureau analysis puts FSA obligations at $6.74 billion across 27,792 loans in fiscal year 2025, up from $5.39 billion in fiscal year 2024. Those are national figures, not Texas ones.
Chart
Average fixed bank rates by loan type
Percent, Eleventh District agricultural bankers, year on year
Who lends to Texas farm businesses
Farm Credit. Farm Credit is a network of borrower-owned lenders. It reports $43.5 billion in loan volume to 51,305 Texas customers as of 31 December 2025, and $356.3 million in patronage dividends. Its Texas list includes AgTexas Farm Credit Services, AgTrust Farm Credit, Capital Farm Credit, Central Texas Farm Credit, Legacy Ag Credit, Plains Land Bank and Texas Farm Credit Services. Each sets its own terms, so compare the rate after any patronage it expects to pay, and ask how that payment has varied.
USDA FSA. FSA is the lender for producers who cannot get enough credit elsewhere at reasonable terms. Its Texas farm loan division reports more than $673.1 million in direct loans and $530.5 million in guaranteed loans through 32 offices statewide.
Banks and credit unions. These write their own farm and agribusiness loans. Some also apply for an FSA guarantee, which lowers the risk they carry. For local searches such as Austin, Dallas, San Antonio or Victoria, start with the nearest FSA office and the Farm Credit association and community banks that serve your county.
Texas Department of Agriculture. Its Texas Agricultural Finance Authority (TAFA) does not replace your lender. It works with one, as the next section explains.
▶ Ten small agriculture business ideas, useful when sizing a first loan · 6:03
Federal farm loan limits and terms
Match the program to the job. The limits below come from FSA program pages checked in November 2026, and the guaranteed limit is adjusted each year for inflation.
Chart
Maximum amount by FSA loan program
US$ per program limit, checked November 2026
Operating and microloans
Direct operating loans go up to $400,000 and cover livestock, equipment, feed, seed, fuel, insurance, minor repairs and family living costs. Terms usually run one to seven years. Applicants need a satisfactory credit history, ability to repay, and no access to credit elsewhere at reasonable terms. Operating microloans go up to $50,000 with terms of one to seven years. They suit beginners, small family farms and niche operations.
Farm ownership, joint financing and down payment
Direct farm ownership loans go up to $600,000, with terms of up to 40 years, for buying land, building or improving. In joint financing FSA covers up to 50% of the cost with another lender. The down payment program helps beginning farmers and ranchers with a 5% down payment, and FSA can lend up to 45% of the purchase price or appraised value. If land is your main goal, read our page on Texas farmland loans.
Guaranteed loans
Here your bank or Farm Credit association makes the loan, and FSA guarantees it up to $2,558,000 and up to 95% against loss. The lender is FSA’s customer and applies with you. Rates are negotiated with the lender but cannot exceed FSA’s maximums. The FSA guarantee fact sheet says most loans carry a fee of 1.5% of the guaranteed portion, which may be passed on to you. Ask for it in writing.
Emergency and storage loans
Emergency loans cover up to 100% of actual production or physical losses, capped at $500,000, in a designated disaster. You must apply within eight months of the designation date. Farm storage facility loans fund on-farm storage and handling equipment. Their November 2026 rates run from 4.875% for three years to 5.25% for twelve years.
Texas state programs that lower your rate
A Texas bill, H.B. 43 (2025), was written to widen TAFA’s two best-known programs. TDA’s pages now reflect the larger sizes and new grant.
The TAFA Interest Rate Reduction program uses a linked deposit: the state places funds with your lender so the lender can price the loan lower. It covers loans of up to $1,000,000 to Texas-based agricultural businesses, with lenders approved as state depositories or Texas-based Farm Credit institutions. TDA lists per-borrower caps of $500,000 under one program version and $1,000,000 under the farmer version, so confirm which applies. It has no listed fee, and it is not a guarantee. TAFA runs a separate Agricultural Loan Guarantee program, which may be used alone or alongside it. Ask your banker first, as the lender and borrower apply together.
Agricultural business grants in Texas
Grants are not repaid, but they are competitive, tied to a project and rarely quick. Treat them as a top-up, not as working capital you can count on.
- AgPRO (Texas). The TDA AgPRO FAQ of April 2026 says awards go up to $500,000 for producers creating or expanding an operation in Texas who earn at least half of gross income from agricultural products. The required match is 10% to 30% depending on size. It pays by reimbursement, so you must spend the money first.
- Value-Added Producer Grant (USDA). The USDA program summary lists about $25 million nationally in fiscal 2026, with up to $200,000 for working capital and $50,000 for planning. That round closed on 22 April 2026, so check for the next one.
- Conservation funding. USDA’s Natural Resources Conservation Service helps pay for conservation work on working land. Ask at your local USDA Service Center.
For a grant, show a clear goal, a budget and measurable results. A reimbursement grant can still need a loan behind it, so plan both together.
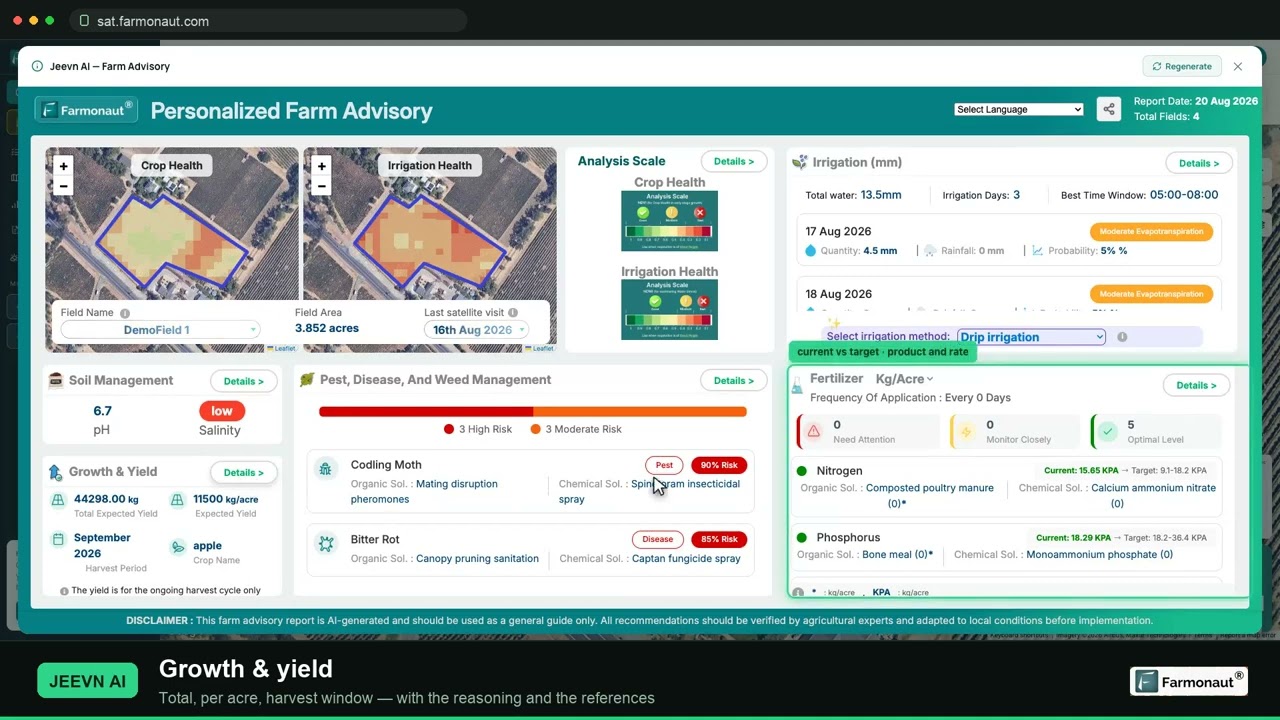
▶ A walkthrough of satellite crop monitoring and field reports · 19:36
How to choose the right agriculture business loan
Four questions narrow the choice quickly. Answer them before you ask anyone for a quote.
- What does the money buy? Seed and feed are used up within a season, so a short operating loan fits. A tractor lasts for years, so an intermediate loan fits. Land suits a long term. A long loan on a short-lived purchase means you are still paying after the asset has gone.
- Can you get commercial credit? If yes, direct FSA loans are probably closed to you, and your choice is between Farm Credit and banks. If a lender says no or only offers part of what you need, ask about a guarantee or go to FSA.
- How large is the need? Under $50,000 points to a microloan if you qualify. Above the direct limits, a guaranteed or commercial loan is the likely route.
- Fixed or variable? In the Dallas Fed table, the third-quarter gap between fixed and variable averages was small, at 0.08 points on long-term real estate. A fixed rate gives you a known payment; a variable rate moves with the market. Ask how often it resets and whether there is a cap.
Also check when payments fall due. A cotton grower and a cow-calf producer earn their income at different times, so ask for payment dates that follow your sales.
Compare the main loan programs
| Program | Limit | Rate, Nov 2026 | Best for |
|---|---|---|---|
| FSA microloan | $50,000 | Ask FSA office | Small and new operations |
| FSA direct operating | $400,000 | 5.625% | Inputs, livestock, equipment when banks decline |
| FSA direct ownership | $600,000 | 6.25% | Land and buildings when banks decline |
| FSA joint financing | Up to 50% of cost | 4.25% | Land with a second lender |
| FSA down payment | Up to 45% of price | 2.25% | Beginning farmers buying land |
| FSA emergency | $500,000 | 3.75% | Losses in a designated disaster |
| FSA guaranteed | $2,558,000 | Set by lender | Larger loans a bank will make with backing |
| Farm Credit or bank | Set by lender | Survey average 7.46%-8.05% fixed, Q3 | Borrowers with commercial credit |
Rates are from USDA’s November notice and the Dallas Fed survey. Survey averages are not offers. Lender fees are extra.
Chart
FSA rates by program
Percent, effective 1 November 2026
Can your agriculture business loan pay for itself?
Many farm loans repay once a year, after harvest or sale, so this tool works on annual payments. Enter the loan and the cash your business can spare for debt in a normal year, after operating costs and family living. Then test a second rate to see what a different lender would cost.
Try the numbers for your own farm below.
Calculator
Does your cash flow cover the yearly payment?
Enter your own loan, rates and spare cash.
- Yearly payment at first rate (US$): $35,351
- Yearly payment at second rate (US$): $38,480
- Left over at second rate (US$): -$2,480
Example values only, not a quote, benchmark or forecast; the defaults are set near break-even on purpose. Rates are examples, use today’s price from your lender. Assumes fixed rates, equal annual payments and no fees. Real loans may differ.
How to apply, step by step
Allow time, because no statewide approval rate or average processing time is published for Texas lenders. Your local FSA office or lender can tell you its current turnaround.
Infographic
Loan route in 4 steps
- 1Size the needSplit operating, equipment and land costs.
- 2Prepare recordsPlan, tax returns, balance sheet, land papers.
- 3Try commercial creditAsk about a guarantee and the TAFA program.
- 4Use FSA if neededApply at your local office.
- Size the need. Separate operating costs from equipment and land. Match the term to the life of what you buy.
- Build the plan. FSA asks for financial and production information and a farm business plan. Banks will want similar facts.
- Gather records. Expect to be asked for tax returns, a balance sheet, lease or deed papers and debts owed. Ask for the lender’s exact list.
- Talk to a commercial lender. Direct FSA credit is for those who cannot get it elsewhere, so a Farm Credit or bank conversation is useful either way. Ask about a guarantee and the TAFA rate program.
- Go to FSA if needed. Find your office through the state page or the USDA farm loan site, which also has a step-by-step assistance tool.
- Compare offers. Set rate, fees, term, collateral and payment dates side by side.
- Keep reporting. After closing, send updates when your lender asks. Contact them early if weather hits your plan.
This is general information, not financial or legal advice. Rates and rules change, so confirm them with the lender and ask an accountant or attorney to review big commitments.
Field records can support your plan
Your yield history and field maps help explain your projections. A satellite service such as the Farmonaut Satellite + AI Farm Monitoring System can keep a season-by-season record of crop condition, through its web and mobile apps. Whether any lender accepts such records is up to that lender, so ask first. For county data to set beside your own numbers, see the USDA NASS Texas statistics bulletin.
Related pages on our site: crop loan and insurance verification, carbon footprint records, product traceability, fleet records, satellite data API and API developer docs.
FAQ
What is an agriculture business loan?
It is credit for a farm, ranch or related business. Common types are operating loans, equipment and livestock loans, and real estate loans. Each has a different term.
What is the FSA farm loan interest rate now?
For November 2026, USDA lists 5.625% for direct operating loans, 6.25% for direct ownership, 4.25% for joint financing, 2.25% for down payment loans and 3.75% for emergency loans. FSA issues new rates monthly.
Can I get a farm loan if a bank turned me down?
Possibly. Direct FSA loans are meant for producers who cannot get credit elsewhere at reasonable terms. You still need a satisfactory credit history and the ability to repay.
Can a Texas agribusiness that is not a farm borrow through these programs?
FSA farm loans are for family farmers and ranchers. TAFA’s rate program covers Texas-based agricultural businesses creating or expanding in the state. Non-farm firms should also ask a bank or Farm Credit association.
Are there grants instead of loans?
Yes, such as AgPRO in Texas and the USDA Value-Added Producer Grant. Both have rules and rounds. AgPRO needs a match and pays you back after you spend.
How much can FSA guarantee?
Up to $2,558,000 on a loan from an approved lender, with coverage of up to 95%. The limit is adjusted each year.
Farmonaut crop monitoring
Keep a season record of your fields
Draw your fields once and Farmonaut shows satellite vegetation maps for them through the season, on web, Android or iOS.




Sources
- USDA FSA, November 2026 lending rates: fsa.usda.gov
- Federal Reserve Bank of Dallas, Agricultural Survey, Q3 2026: dallasfed.org
- USDA ERS, Assets, Debt and Wealth: ers.usda.gov
- American Farm Bureau, Financing the Farm (2026): fb.org
- Farm Credit, Texas state page: farmcredit.com
- USDA FSA Texas, farm programs: fsa.usda.gov
- USDA FSA, Farm Operating Loans: fsa.usda.gov
- USDA FSA, Operating Microloan: fsa.usda.gov
- USDA FSA, Farm Ownership Loans: fsa.usda.gov
- USDA FSA, Guaranteed Farm Loans: fsa.usda.gov
- USDA FSA, Loan guarantee fact sheet (2025): fsa.usda.gov
- USDA FSA, Emergency Farm Loans: fsa.usda.gov
- Texas Legislature, H.B. 43 bill analysis (2025): capitol.texas.gov
- Texas Department of Agriculture, Interest Rate Reduction: texasagriculture.gov
- Texas Department of Agriculture, AgPRO FAQ (April 2026): texasagriculture.gov
- USDA, Value-Added Producer Grant summary (2026): farmers.gov
- USDA, farmers.gov farm loans: farmers.gov
- USDA NASS, Texas Annual Statistical Bulletin: nass.usda.gov
- USDA FSA, January 2026 lending rates: fsa.usda.gov
- USDA FSA, October 2026 lending rates: fsa.usda.gov
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Insignito
 Croptimum
 Dalmia Bharat Sugar
 DnCubed
 Pistachio ST
 Field Capacity
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroGreen Dynamics
 AgroRisk
 Oath Inc
 Reddane Farming
 Esri North East Africa
 Cresol
 MDCV UK
 Etech Consulting Madagascar

 Licence holder · Niger · Gold
 Client · Tanzania · Gold










